GBP/USD trims losses but ends the week lower
- GBP/USD chalked in a fourth consecutive down week.
- Despite early losses, Cable clawed back some ground late in the week.
- Coming up next week: UK and US CPI inflation updates.

GBP/USD wrapped up a fourth straight week in the red, closing lower around four-tenths of one percent despite a late-week recovery from lows below the 1.2700 handle. A thin showing on the economic calendar from the UK side gave GBP traders a breather after the Bank of England (BoE) sparked a broad-market pummeling of the Pound Sterling. Market flows have since rebalanced, and investors have now pivoted towards next week’s upcoming Consumer Price Index (CPI) inflation prints due from both sides of the Atlantic.
Forecasting the Coming Week: US CPI and Fed’s easing should rule the sentiment
The focus in the market is on the likelihood of a rate cut by the Federal Reserve in September. Rate markets have fully factored in the beginning of a cycle of rate cuts when the Federal Open Market Committee (FOMC) meets on September 18. However, expectations for an initial double cut of 50 basis points have slightly diminished from nearly 70% earlier this week. According to the CME’s FedWatch Tool, rate traders are estimating a 53.5% chance of a 50 bps cut in September, with two additional cuts of 25 basis points each projected for the remainder of 2024.
Next week, investors will receive fresh inflation data to consider, with US Producer Price Index (PPI) and Consumer Price Index (CPI) inflation scheduled for Tuesday and Wednesday, respectively. US Retail Sales and an update from the University of Michigan’s Consumer Sentiment Survey Index are also expected later next week. Both core PPI inflation and headline CPI inflation are currently around 3% year over year, and investors will be looking for further easing in headline figures to support the case for rate cuts by the Fed.
UK CPI inflation is expected to tick up to 2.3% YoY in July from the previous 2.0%, while core CPI inflation figures are forecast to tick down to 3.4% from 3.5%. Gross Domestic Product (GDP) growth numbers from the UK are also expected later next week, and Q2 UK GDP is expected to ease to 0.6% from the previous 0.7%.
GBP/USD price forecast
Cable continues to tease a bearish fall back into the 200-day Exponential Moving Average (EMA) at 1.2649, but bidders have thus far stepped up to keep bids from falling any closer toward the 1.2600 handle. However, bullish momentum has evaporated as GBP/USD remains down over 2% from 12-month peaks just above 1.3000 set in July.
GBP/USD daily chart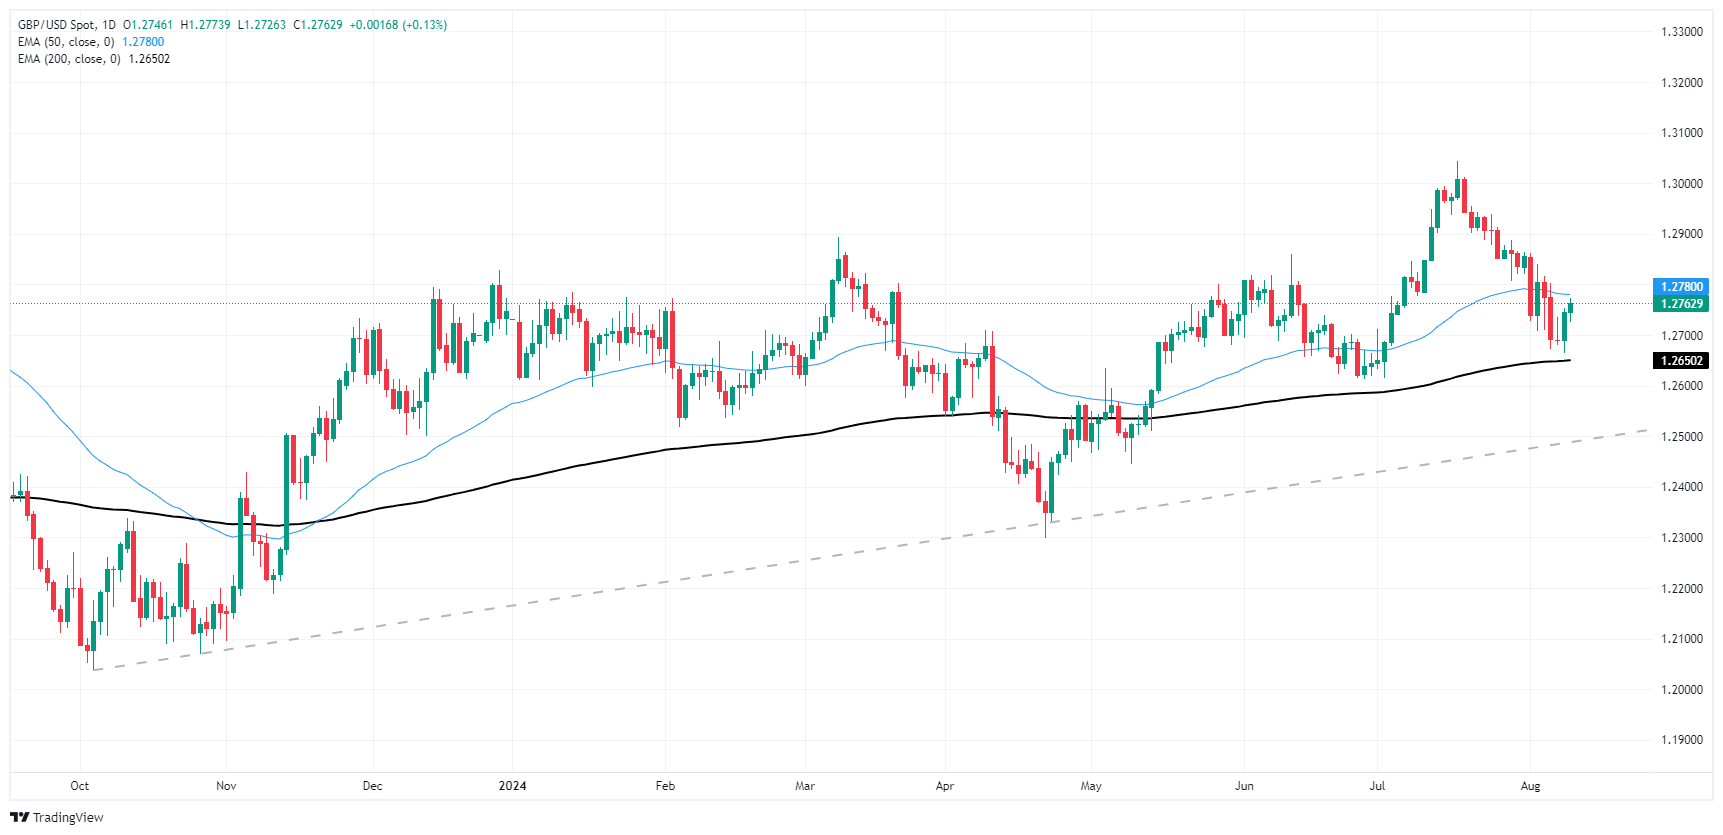
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, aka ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.
















