Week Ahead on Wall Street (SPX) (QQQ): Mr. Market prices inflation as transitory, we know how that worked out
- Inflation spikes again confounding investors and policymakers.
- 100 basis point hike priced to near certainty before Waller and Bostic get all doveish.
- Recession is now priced to near certainty by money and commodity markets but not yet equities.
Interesting to always note how the narrative is twisted to support exactly what the market wants to do. Last month the University of Michigan's Inflation expectations were cited by the Fed for its knee-jerk panic into hiking rates by 75 basis points. In the immediate aftermath, commentators pointed out how limited the survey is in its scope being based as it is on a few hundred survey responses. Now that the same survey this month shows a modest and it is very modest reduction, everyone is citing it as gospel. Inflation is cured, it's transitory, rally back on for risk assets. Excuse the sarcasm but we are not out of the woods by a long long long way. Equity markets are always the last ones to know and it looks like that feat is repeating itself if the latest developments are anything to go by. Inflation remains on fire and in fact rising and broadening its base. That broadening is the most worrying aspect as it means it will likely last longer than most expect. Transitory is now on the lexicon of investors who are pricing inflation to be brought to its knees by a recession in 2023.
US Long-Term #Inflation Expectations Drop to One-Year Low - Bloomberg
— Christophe Barraud (@C_Barraud) July 15, 2022
*Link: https://t.co/yOoHpkDDui pic.twitter.com/6pQpAUxBWu
Money markets currently price in a rate cut in the first quarter of 2023 and hilariously expect 75 basis points of cuts for 2023 in totality. That would make this hiking cycle one of the fastest in history followed by one of the quickest pivots in history. Why bother at all then should be the Fed's decision this July! You guys have figured it out for us!
ding ding ding: One Full Rate Cut priced in For Q1.
— zerohedge (@zerohedge) July 13, 2022
Time to start pricing in QE pic.twitter.com/xYAfd9Ngm6
Market is pricing more than 75bps #fFed rate cut for 2023. pic.twitter.com/BprXdfH46C
— Christophe Barraud (@C_Barraud) July 14, 2022
The commodity markets meanwhile are also in full recession mode with oil prices collapsing, copper in freefall, and everything except European gas prices falling sharply on pricing in a global recession and resultant demand suppression. Oil futures prices are in backwardation and pricing in a recession
Oil still in deep backwardation. The consensus now is a '08 or '20 type commodity crash again? What happens once CB's balance sheets grow (significantly) again? pic.twitter.com/hCEK5bUIYP
— The Passenger (@gordonschuecker) July 15, 2022
Meanwhile copper is in freefall
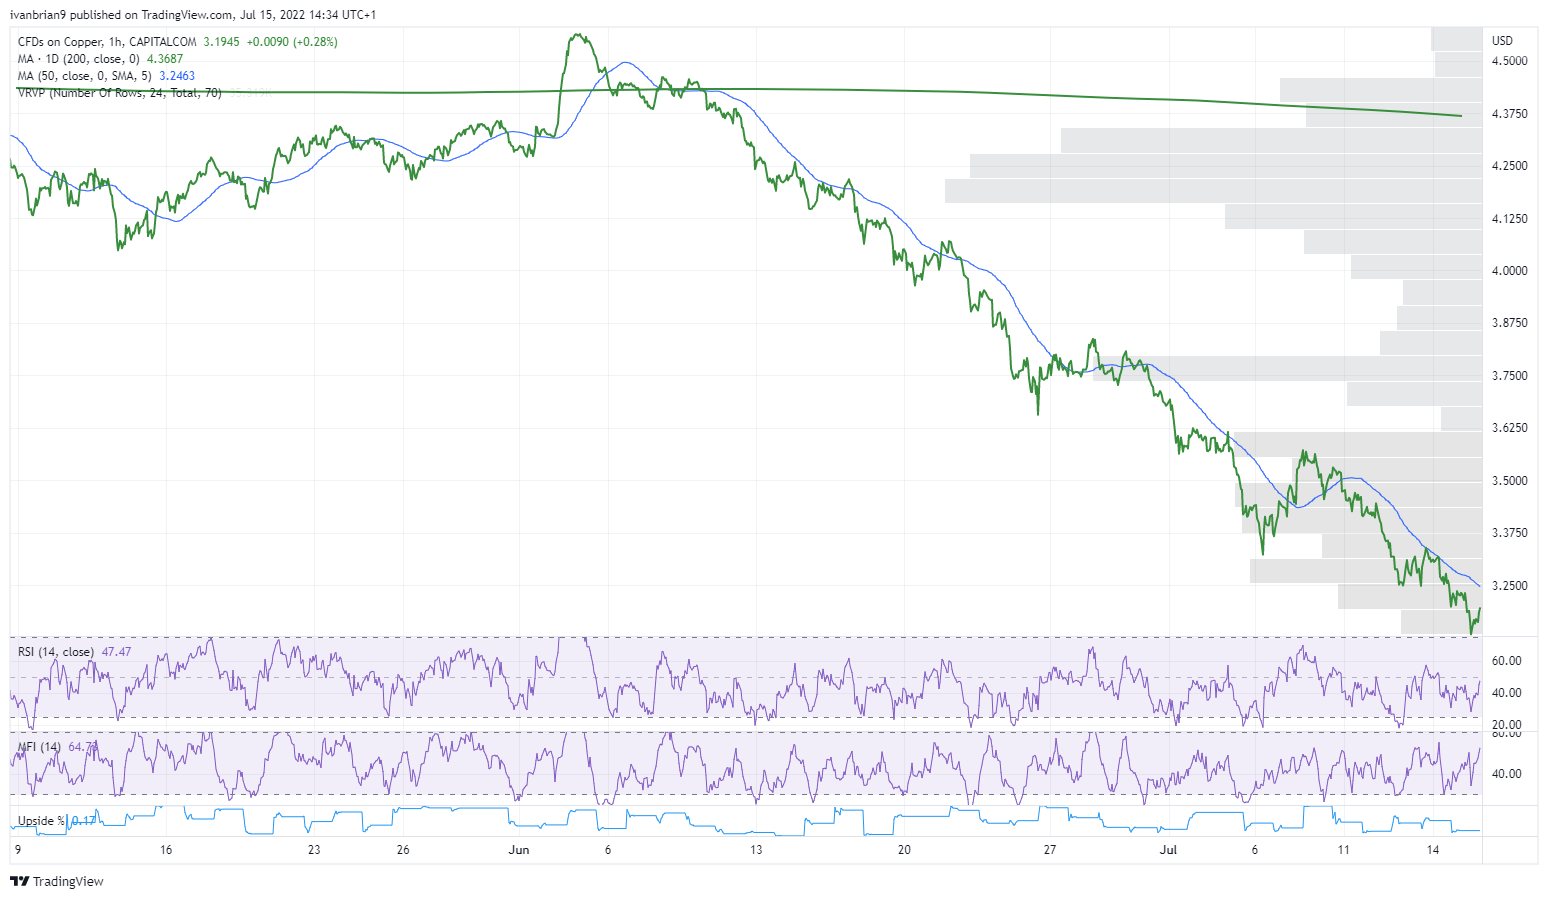
Copper futures, daily
Wheat prices have also collapsed and are now lower than pre-Ukraine invasion levels.
#WHEAT FUTURES ERASE 2022 RALLY TRIGGERED BY WAR IN UKRAINE - BBG pic.twitter.com/9vRJfNmkLd
— Christophe Barraud (@C_Barraud) July 15, 2022
So with money, bond, and commodity markets pricing in a recession what about the equity market?
After the "Surge Comes the Purge" Sales during lockdowns were +2 sigma - likely it goes -2 sigma - not good for EPS! Expected Impact on FAANG shown below... pic.twitter.com/c9tgKI6VnW
— Douglas Orr, CFA (@EquitOrr) July 14, 2022
Not looking too rosy here then and we have posted repeatedly in past editions about how crazily high analyst estimates are for the S&P 500 for 2023. The average earnings estimate for the S&P 500 (SPX) was at $250 but finally, some sense is prevailing and downward revisions have picked up speed. The current forecast is back to $247 for 2023 a step in the right direction but something in the $ 220s is more appropriate for a recession. That should see the S&P 500 (SPX) back to 3,000 or so based on historical P/E averages. Already things are not looking too good with Amazon Prime day being extended to two days rather than the traditional one and look at this for a raft of heavy reductions. Does not bode well for retail or Amazon!
Amazon Prime Day - discounts up to 79% pic.twitter.com/5GATV9wXRW
— zerohedge (@zerohedge) July 15, 2022
Inventories are also being slashed as companies look to ditch stuff they are stuck with. There have been anecdotal reports of Walmart and others just paying you to keep your returns as inventory levels are way too high.
Just keep your returns: Stores weigh paying you not to bring back unwanted items - CNN
We are seeing a significant change in worldwide inventory management, with fewer companies building stocks for safety considerations & more companies (in fact the most since 2009) cutting inventories due to weak sales. Hence weaker demand for commodities. #PMI #supply #inflation pic.twitter.com/mmavBHS5w4
— Chris Williamson (@WilliamsonChris) July 15, 2022
The situation is likely to get worse with the earnings season ramping up. China lockdowns were blamed for a host of tech-related stocks being hit as Tesla (author is short), Apple, and many others rely on China for both manufacturing and demand. Well, the latest news from China is not good with Friday seeing pretty poor economic data and more lockdowns being reported as covid once again becomes a problem.
#China Growth Slows Sharply, Putting GDP Target Out of Reach - Bloomberg
— Christophe Barraud (@C_Barraud) July 15, 2022
*CHINA 2Q GDP GROWS 0.4% Y/Y; EST. 1.2%
*CHINA 2Q GDP -2.6% Q/Q; EST. -2.0%
*Link: https://t.co/nZK5UHMoOk pic.twitter.com/8hIkfc9WjD
China’s credit market is entering a new stage of its distressed cycle. As the world’s No. 2 economy contracts, payment risk is spreading from private developers to a wider variety of borrowers. Global investors have been hardest hit by defaults. 2/6https://t.co/OIJKYngHOr pic.twitter.com/539mvksWJW
— Rebecca Choong Wilkins 钟碧琪 (@RChoongWilkins) July 14, 2022
So we remain with our view that the bottom is not yet in but it may be after the next earnings season. But it may need two earnings seasons for this mess to get sorted out and that would tie in with a late autumn, early winter rally which is a historical feature of mid-term years and even more so when the incumbent loses its majority. So let's see if history repeats itself.
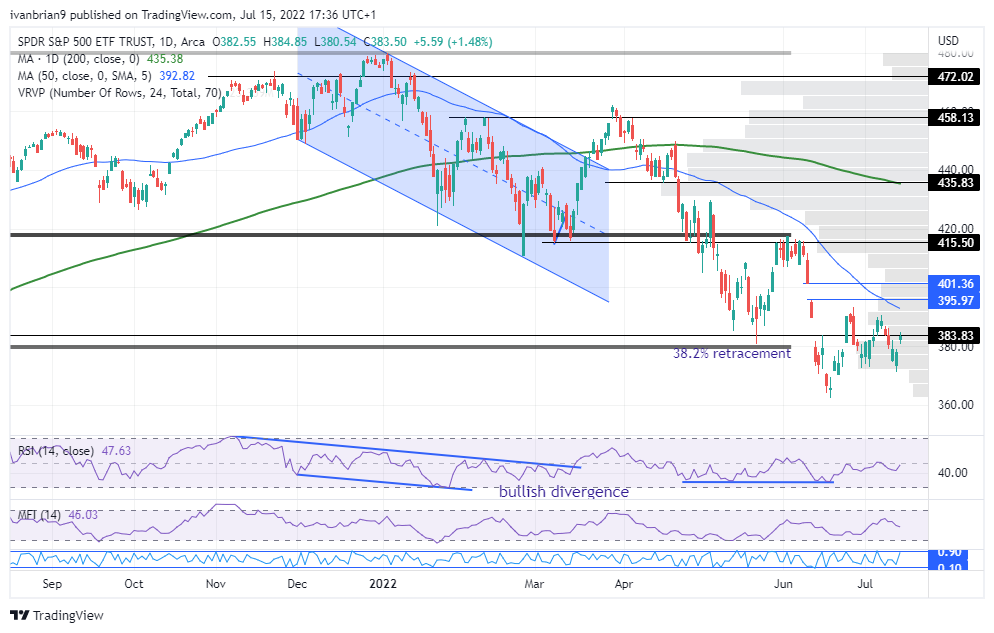
SPY forecast
Still, nothing to get too excited about until the gap at $395 to $401 is filled. That will see a raft of people predicting the bottom is in and set up a nice bear market rally fade. We do see the possibility of an extension to $415 where we would look to go short. Earnings season will be key as it ramps up for the next three weeks.
Earnings week ahead
Earnings season has begun with Jamie Dimon forecasting a hurricane before Citigroup smashed earnings but then Wells Fargo went back to bearish mode as it too missed like JPM after boosting bad debt provisions. It too must see a hurricane on the horizon. Next week things get really interesting as Tesla and Netflix kick off the once fabled FAANGT sector while Goldman Sachs looks to nail down its preeminent investment bank position. Lockheed Martin should see if all the increased defense spending by governments has yet to follow through to bottom line and or forecasts.
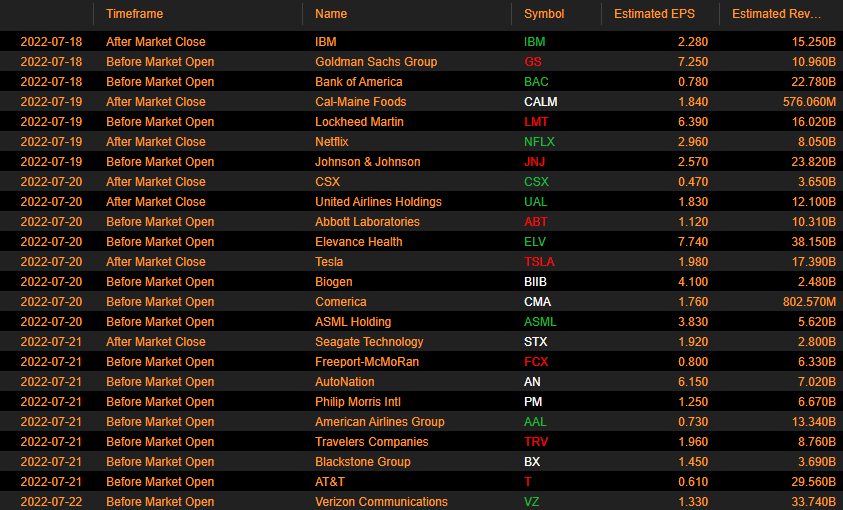
Source: Benzinga Pro
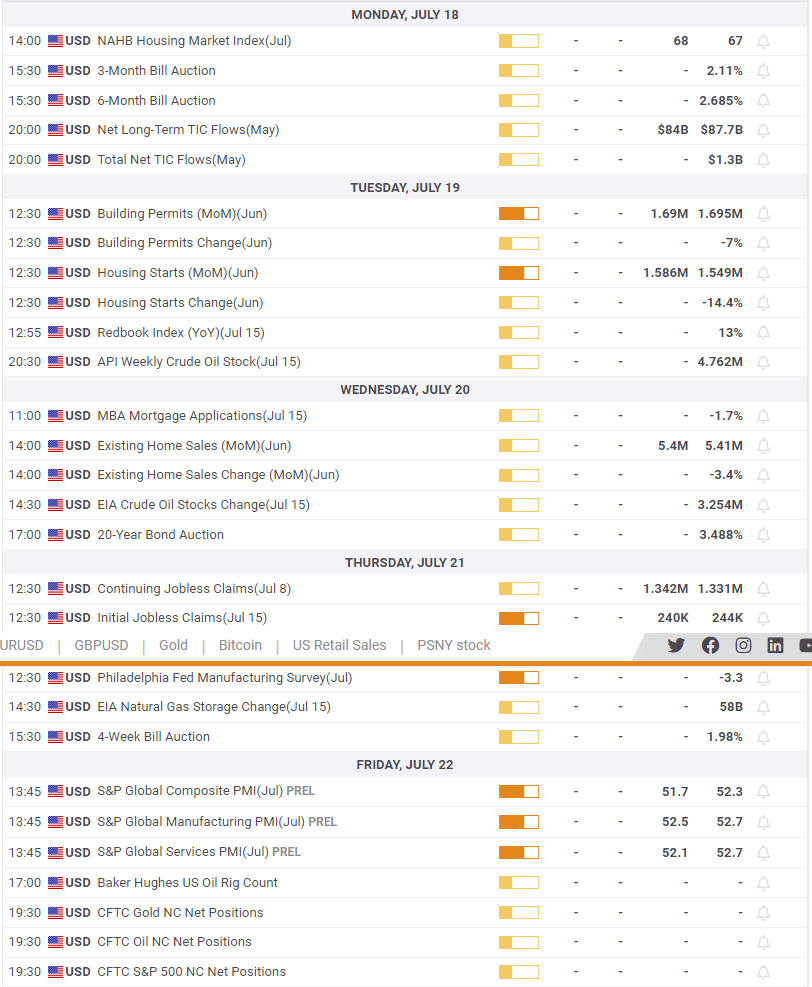
Economic releases
Economic data remains the core focus of most investors due to macroeconomic factors trumping most others in equity valuations currently. None of us active in the markets today have any experience with an inflationary environment, as it last happened in the 70's in any meaningful way. There has been quite a lot of talk re the housing market this week and with perfect timing, we get quite a slew of data next week on that very subject. It seems natural to assume rising rates are going to have an impact the question is just how much.
Author

Ivan Brian
FXStreet
Ivan Brian started his career with AIB Bank in corporate finance and then worked for seven years at Baxter. He started as a macro analyst before becoming Head of Research and then CFO.