USD/JPY Weekly Forecast: View ahead is the same as the view behind
- Prospect of higher US interest rates fade on weak data, Fed dovishness.
- USD/JPY loses 110.00 on Tuesday, stays below on Friday.
- Technical considerations dominate near-term USD/JPY action, bias weakly lower.
- FXStreet Forecast Poll expects a near term decline.

Prospects for higher US interest rates faded further as poor economic data reinforced the Fed’s cautious view and confirmed the retreat of Treasury yields since the June 16 meeting.
The USD/JPY lost altitude on the week, but trading easily remained within the range of the last two months. With weak US statistics and stationary monetary policy, there was no compelling reason to buy the pair and with positive Japanese input absent. There was no substantial logic for selling either.
Comments from Japanese Prime Minister Yoshihide Suga on Friday that the Delta variant of the coronavirus is spreading quickly among the elderly struck a cautionary note on the country’s immediate economic future.
The statement from the Federal Open Market Committee (FOMC) issued with the Wednesday decision noted that “progress” had been made toward the bank's goals but provided no guidance on the timing of a much anticipated reduction in the bond purchase program.
Chair Jerome Powell was equally recitient, leaving markets largely without policy directive until the next Fed meeting on September 21-22.
In his press conference, Mr. Powell said that the withdrawal of monetary support has become an active topic among the governors. He noted the US job market still had “some ground to cover” before the bank would begin the reduction of the $120-billion-a-month in purchases of Treasury and mortgage-backed securities.
Treasury yields were slightly lower on the week, reflecting the lack of a counter view in the credit market to moderating US growth and the still active pandemic induced labor market and supply chain problems.
However, in the comparison of the Japanese and American economies, the US retains a strong advantage and that is the dollar’s main support.
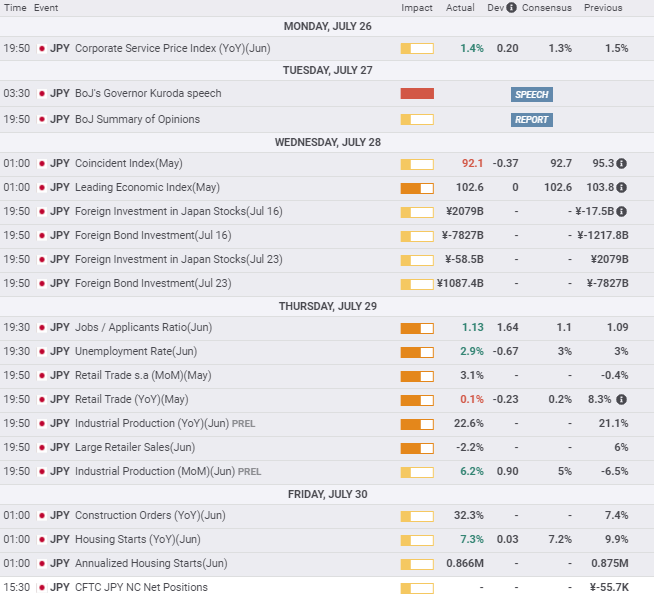
In US economic information, Durable Goods Orders in June were weaker than forecast though the impact was mitigated by substantial positive revision in May. Second quarter GDP came in at 6.5%, well below the 8.5% forecast. The Core PCE reading for June was lower than predicted, but as the Fed has disavowed any policy impact it made no print on the market.
Japanese data saw some improvement with Industrial Production in June bouncing back from May’s loss. Aside from that, Japan seems trapped in a slow moving recovery, unable to shake the COVID sand from its economic gears. The sparsely attended Summer Olympics in Tokyo will likely join the lengthening list of Japanese disappointments.
USD/JPY outlook
There is no present case for buying and only a weak case for selling the USD/JPY.
Relative to its position in late June and early July when the idea of a reduction in the Fed’s bond program seemed probable, the USD/JPY has already lost two figures.
The loss of motivation for pursuing the USD/JPY above 111.00 is not a trend lower. Recent selling in the pair is a reaction to US economic and rate developments. It is not a reflection of yen strength or of a burgeoning Japanese recovery.
Statistics in the coming week will not change the positions of the two economies.
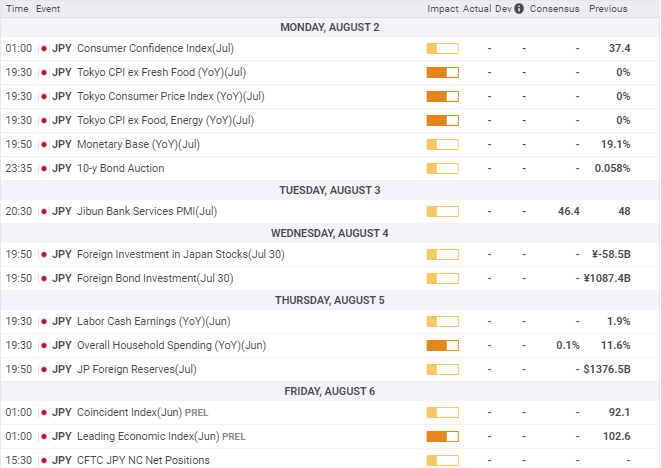
Overall Japanese Household Spending for June should continue the healthy rebound that started in March, but Japan’s economy is driven by exports not domestic consumption. Tokyo CPI, an indicator for national inflation trends, may return from eight months of deflation, but that would hardly convince markets that the Bank of Japan has succeeded in its goal of ending price declines.
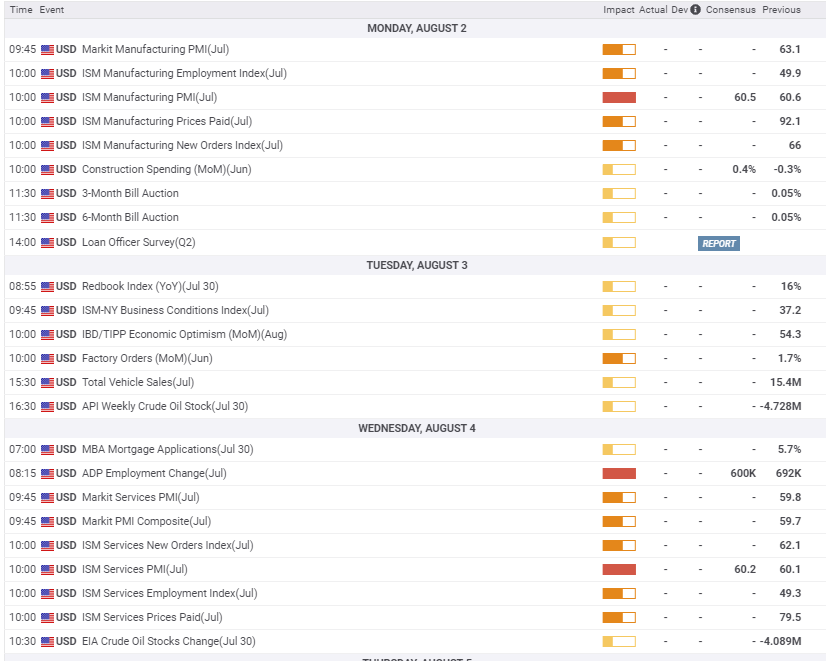
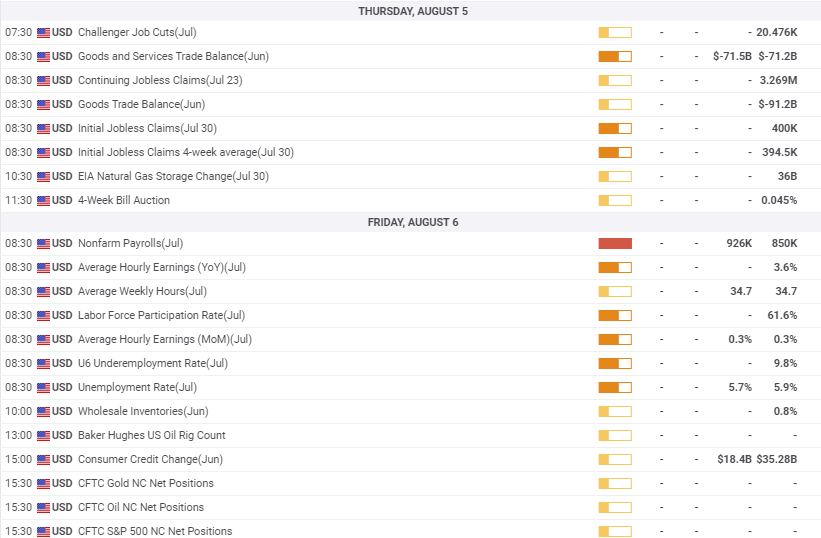
Nonfarm Payrolls for July on Friday, August 6, will order US markets with a strong result capable of giving the dollar a boost. Purchasing Managers Indexes for the service and manufacturing sectors in July could, if better than expected, revive some of the economic optimism lost to GDP.
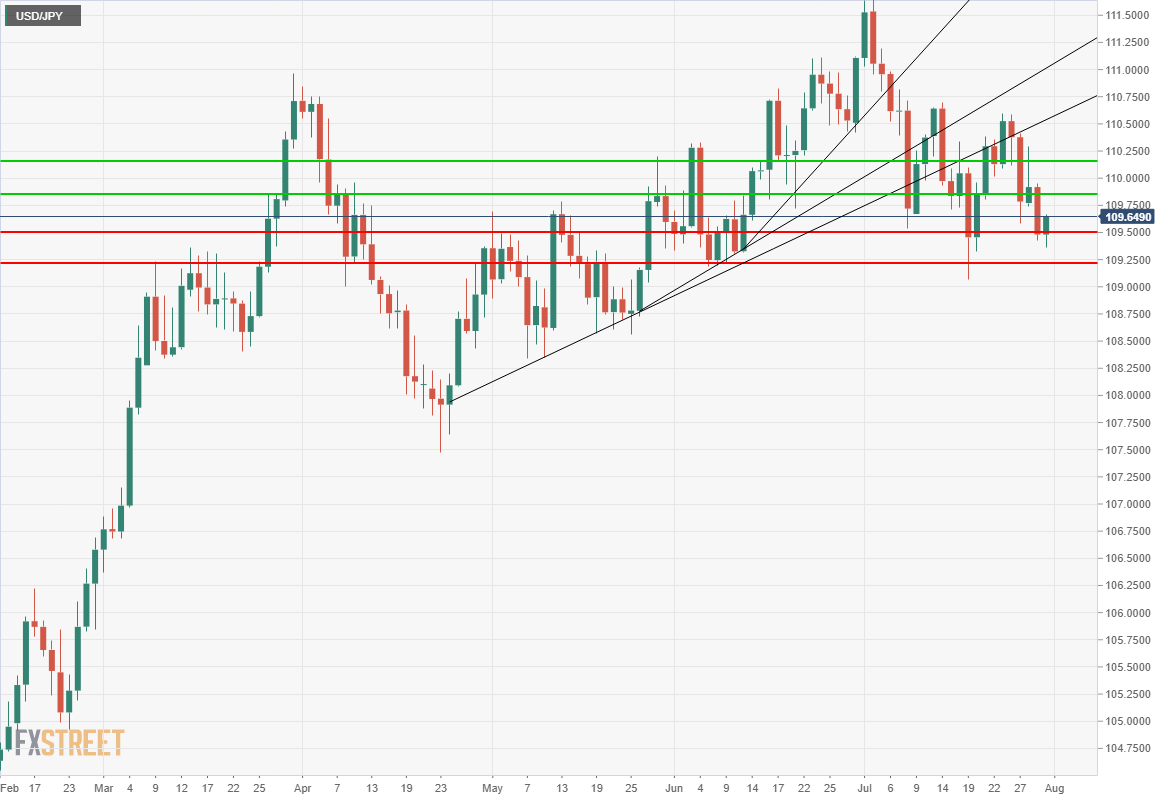
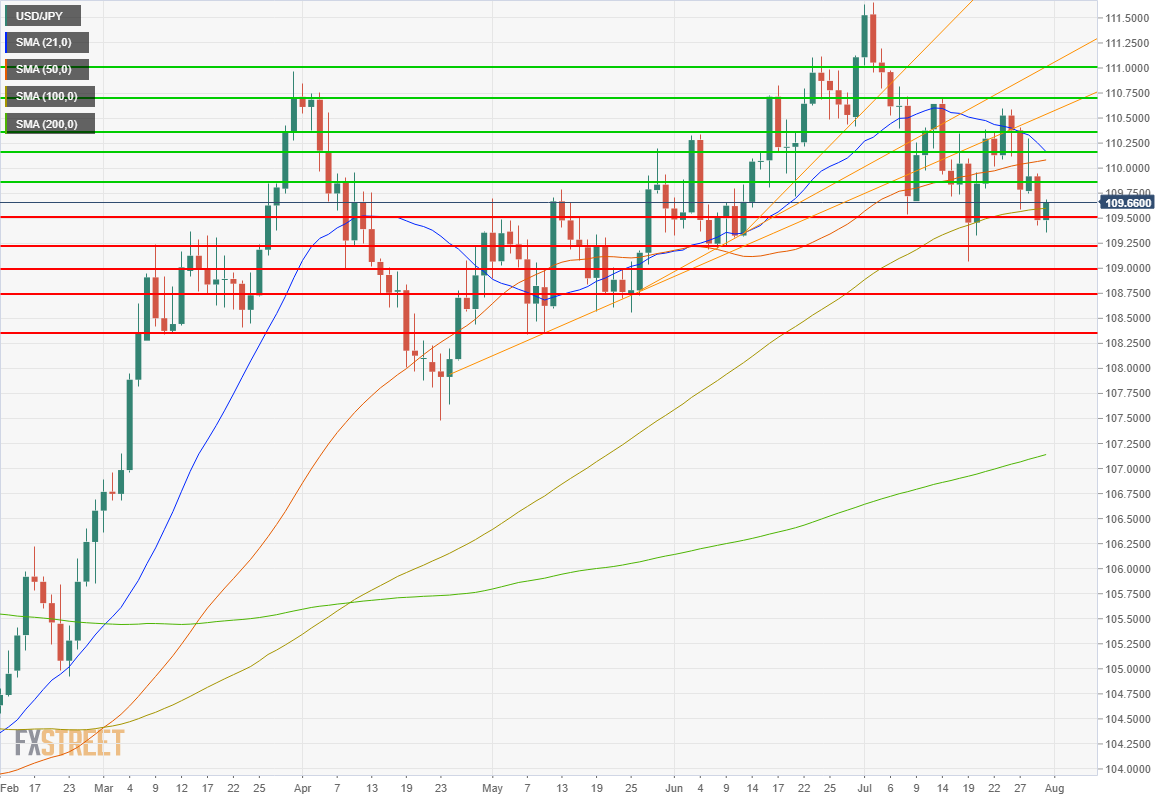
Technical considerations are balanced, with equal representation of support and resistance lines. The loss of the 100-day moving average (MA) on Thursday leaves only the 200-day MA for support, albeit more than two figures below the market.
The drop to 109.50 on Thursday and slight recovery gives a slight downward cast to trading. Expect movement down to be impeded by support lines, which, as they are tested will negate any serious move lower.
Japan statistics July 26–July 30
US statistics July 26–July 30


Japan statistics August 2–August 6
Overall Household Spending and Consumer Confidence will give an update on Japanese domestic consumption, Tokyo CPI on inflation. None of these statistics will move markets.
US statistics August 2–August 6
Nonfarm Payrolls provide market focus. Almost one million hires are expected and if the number surpasses the forecast it could restore some luster to the US economy and the dollar. Purchasing Managers' Indexes will give indications about how much the continuing labor and supply shortages are affecting business optimism.
USD/JPY technical outlook
Overall bias is lower but it is weak and the result of topside failure rather than a substantive argument for selling.
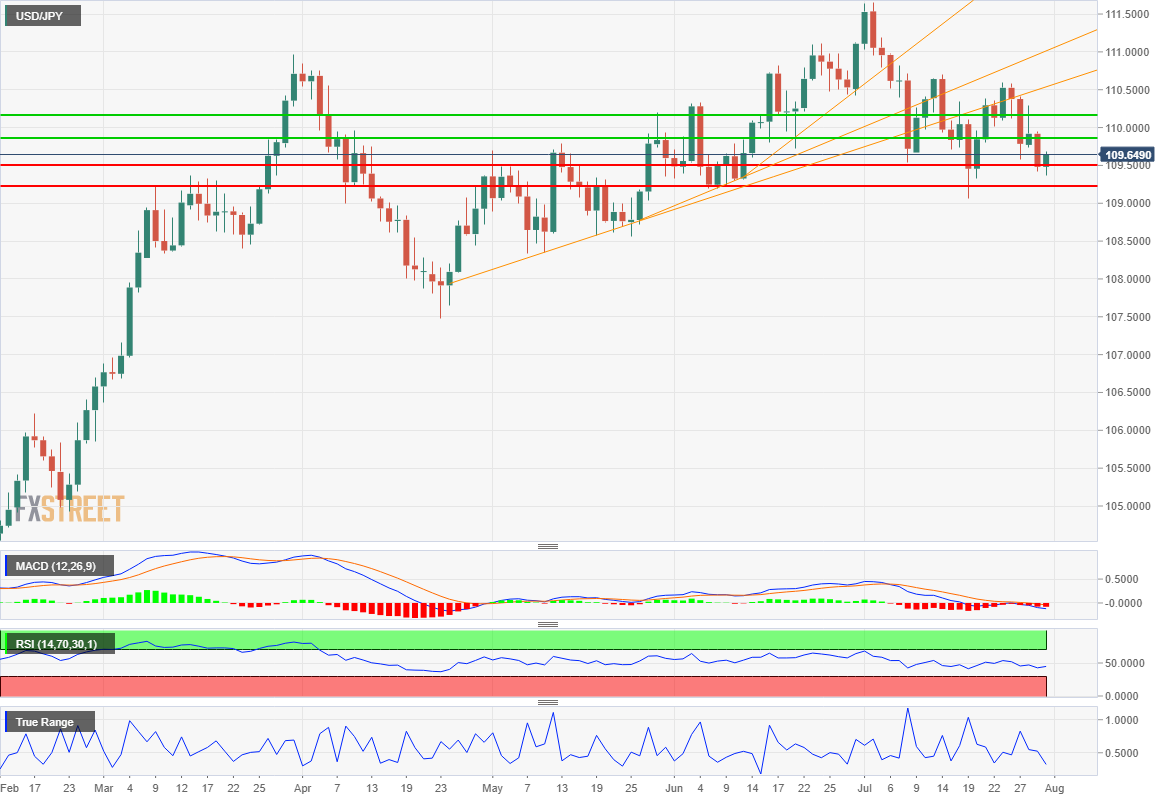
Momentum indicators have moved to the negative. The MACD is a modest sale. The Relative Strength Index (RSI) shows weak selling motion and True Range is slightly more emphatic. The upward trend lines had become ever steeper over the past three months. The last and longest was broken on Monday and it is now resistance at 110.50.
The 21-day and 50-day moving averages (MA), 110.16 and 110.08, join with resistance at 110.15 for a strong band just over 110.00. The 100-day MA at 110.60 is mild support, having been crossed in both directions on Friday. Support and resistance lines are well balanced and equally traded, given the lack of strong fundamental momentum they should control the action.
Resistance: 109.85, 110.15, 110.35, 110.70, 111.00
Support: 109.50, 109.20, 109.00, 108.75, 108.35
FXStreet Forecast Poll
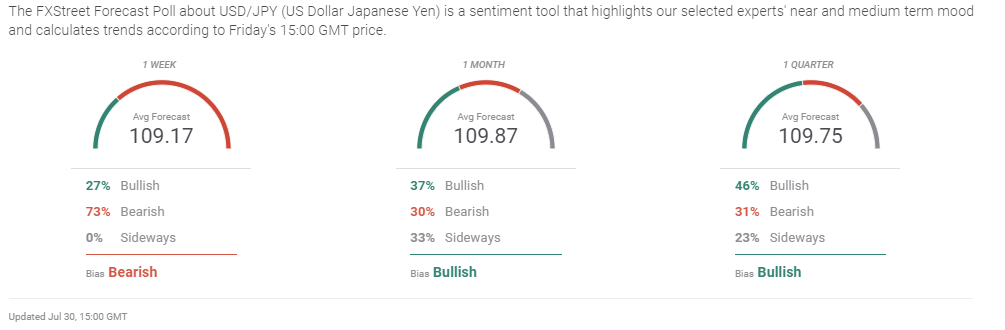
The FXStreet Forecast Poll reflects the immediate technical weakness of the USD/JPY even as the pair retains positive long-term prospects.
Author

Joseph Trevisani
FXStreet
Joseph Trevisani began his thirty-year career in the financial markets at Credit Suisse in New York and Singapore where he worked for 12 years as an interbank currency trader and trading desk manager.

















