Personal Income, Spending and Prices July Preview: The second opinion concurs
- Income decline to moderate, spending to rise for third month.
- Retail sales gained in July, durable good purchases much stronger than forecast.
- Core PCE prices annual rate headed to two-thirds of that in the first quarter.
- Income and spending figures duplicate already released data obviating market impact.

Consumption expenditures and personal income figures for July are expected to reinforce the economic recovery picture already presented in the retail sales and wage data released earlier in August.
Personal spending is forecast to rise 1.5% after adding 5.6% in June and 8.5% in May. To date spending has recovered 72.3% of its 19.5% drop in March and April. If July’s forecast is accurate that will increase to 80%.
PCE
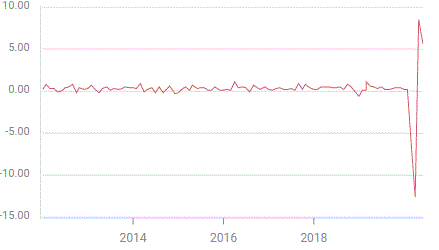
Personal income is predicted to drop 0.2% in July following the 1.1% decline in June. The personal consumption expenditure (PCE) price index is expected to gain 0.1% on the month in July and 1.2% on the year after 0.4% and 0.8% respectively in June. The core PCE price index is forecast to jump 0.5% in July and 1.2% annually. June’s changes were 0.2% and 0.9%.
Personal spending, retail sales and durable goods
Personal spending or more properly, personal consumption expenditures, from the Bureau of Economic Analysis (BEA) is a broader measure of consumer spending than the better known retail sales measure. The main difference is that PCE includes spending on services and is tracked from the household purchases side rather than from store receipts.
Retail sales rose 1.2% in July bringing the three month total to 27.8%, well beyond the 22.9% combined decline in the pandemic months of March and April.
Retail sales
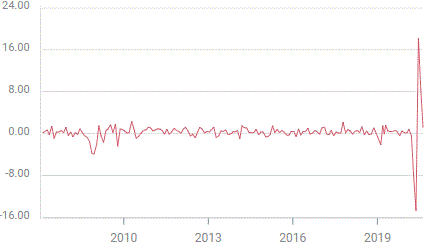
Purchases of long-lasting durable goods, a sub-set of overall sales jumped 11.2% in July, more than double the 4.3% forecast and bringing the three month surge to 34% nearly equal to the 35% plunge in March and April.
Personal income
Income and wage data over the past five months has been skewed by the effects of the massive layoffs in March and April and the subsequent partial rehiring.
The majority of laid-off workers were lower-paid and hourly workers. When their wages and income were subtracted from the remaining better paid employees the average compensation rose. In April personal income jumped 10.8% and average hourly wages climbed 4.7%.
As workers returned the gains reversed—income fell 4.4% in May and 1.1% in June and wages fell 1% in May and 1.3% in June. The July gain in wages of 0.2% is a normal range increase while the -0.2% income forecast is considerably below the average for last year and is probably low.
The personal income figures from the BEA, a division of the Commerce Department, much like their personal spending numbers are a wider category than the older retail sales and average hourly earnings numbers form the Bureau of Labor Statistics and the Census Bureau. The BEA statistics include pensions, unemployment benefits, interest, dividends and all manner of transfer payments rather than simple wages information.
PCE price index
The cascade of consumer price indexes in March and April was caused by retailers attempting to move as much merchandise as possible as the country closed down. The annual core PCE rate fell from 1.9% in February to 0.9% two month later and it returned there in June after edging to 1% in May. If the July forecast is correct at 1.25 if would be the first gain in annual prices since the lockdowns.
The core PCE price index is gauge used by Federal Reserve to chart inflation. It is a more modern measure that uses a different basket of goods than the older CPI and attempts to capture the price impact of substitution, when consumers replace a newly expensive item with a cheaper one and the gain in value from quality improvements.
Conclusion and markets
Personal consumption and income data from July will add details to the available information but are unlikely to alter the economic picture in any substantial way. Consequently their market impact will be limited if at all.
Author

Joseph Trevisani
FXStreet
Joseph Trevisani began his thirty-year career in the financial markets at Credit Suisse in New York and Singapore where he worked for 12 years as an interbank currency trader and trading desk manager.

















