EUR/USD Weekly Forecast: Optimism likely to keep the US Dollar pressured
- The Nonfarm Payroll report showed that the labor market cooled in April.
- The Federal Reserve was less hawkish than anticipated, markets rallied on relief.
- EUR/USD is up for a third consecutive week but buying interest remains reluctant.

The EUR/USD pair advanced for a third consecutive week, accumulating a measly 160 pips in that period. The pair trades around 1.0760 ahead of the close after tumultuous headlines failed to trigger a clear directional path.
What happened with the Fed?
The Federal Reserve (Fed) had a monetary policy meeting, and as widely anticipated, policymakers held interest rates steady at the range between 5.25% and 5.5%. The decision was no surprise as inflation has shown signs of picking up in the first quarter of 2024, while growth slowed. The central bank has emphasised inflation remained stubbornly high and repeated interest rate cuts will have to wait until policymakers are confident enough it will move sustainably towards their 2% goal.
Chairman Jerome Powell dropped some hawkish comments in the following press conference, but not as hawkish as feared. On the one hand, Powell noted interest rates are restrictive enough, dismissing the odds for a rate hike. On the other hand, Powell said that there are multiple scenarios in which they may go for cuts, although he remarked that an unexpected weakening in the labor market could speed up the first cut. Regarding growth, Powell did not show concerns about the recent setback in Gross Domestic Product (GDP), but on the contrary, seemed confident about growth.
Unfortunately, after the event was set and done, speculative interest only added to the uncertainty on when and for how much the Fed will cut rates. On a positive note, traders felt relieved that there were no rate hikes in sight. Stock markets rallied, and investors dropped the US Dollar on the back of optimism.
The United States employment situation
The US released multiple employment-related figures this past week, and there are good news for the economy, but bad news for those waiting for the Fed to act promptly. The ADP survey indicated that the private sector added 192K new positions in April while the number of job openings remained little changed at 8.5 million on the last business day of March, according to the JOLTS Job Openings report. Furthermore, Nonfarm Productivity in the first quarter rose a modest 0.3%, while Unit Labor Cost in the same period was up 4.7%, higher than the 3.2% forecast. Finally, the Employment Cost Index rose 1.2% in the first quarter, higher than anticipated. Overall, data signalled the labor market remained tight, fueling concerns.
However, things changed on Friday, when the US released the April Nonfarm Payrolls (NFP) report. The country added 175K new jobs in April, below the revised 315K from March and the expected 238K, according to the Bureau of Labor Statistics (BLS). Also, the Unemployment Rate increased to 3.9% from 3.8%, while the Labor Force Participation Rate held steady at 62.7%. Finally, Average Hourly Earnings declined to 3.9% YoY, below the 4% anticipated.
The NFP report was almost “Fed-perfect.” It showed weaker job creation, a higher level of unemployment, and easing inflationary pressures from wages. As a result, financial markets turned greedy. The US Dollar edged sharply lower against most major rivals, and stock markets rallied.
What data has to say
The US also published the ISM Manufacturing PMI, which showed the sector’s output “contracted in April after one month of expansion following 16 consecutive months of contraction”, according to the latest Manufacturing ISM report. Finally, S&P Global confirmed the Manufacturing PMI for the same month at 50 above the 49.9 expected and preliminary reading but below the previous 51.9. The ISM Services PMI for the same month unexpectedly shrank to 49.4 from 51.4, missing the 52 expected, cooling down optimism ahead of the weekly close but not enough to spur US Dollar’s demand.
At the end of the day, hopes prevailed. Market players are now relieved the Fed’s road may be bumpy, but the path is more or less clear.
Across the pond, the Eurozone reported that Consumer Confidence held steady at -14.7 in April, while the Harmonized Index of Consumer Prices (HICP) rose 2.4% YoY, while the core annual reading printed at 2.7%, declining from the previous 2.9% although higher than the 2.6% expected. The annualized EU Gross Domestic Product (GDP) was up 0.4% in the first quarter, doubling expectations.
Germany, the EU’s largest economy, reported that the HICP was up 2.4% YoY in April, surpassing the anticipated 2.3%. However, the economy contracted in the first quarter of the year, with the Q1 GDP printing at -0.2% as expected.
The Hamburg Comercial Bank (HCOB) upwardly revised the EU Manufacturing PMIs, although the German and Eurozone indexes remained within contraction territory in April. Still, the generally positive European data back the case for a European Central Bank (ECB) rate cut in June.
The upcoming week will bring the final HCOB April Services and Composite PMIs for the EU. The EU will also release the March Producer Price Index (PPI) and Retail Sales for the same month, while the US most relevant figure will be the preliminary estimate of the May Michigan Consumer Sentiment Index. Given that the Fed has already announced its monetary policy decision, officials’ speeches will also capture some attention.

EUR/USD technical outlook
The EUR/USD pair peaked at 1.0811 for the week in the NFP aftermath but retreated towards the 1.0760 price zone ahead of the close. From a technical point of view, the weekly chart shows the pair recovered from near a flat 100 Simple Moving Average (SMA), providing dynamic support at around 1.0630. But at the same time, the pair seems unable to recover beyond a mildly bearish 20 SMA, acting as dynamic resistance in the 1.0840 region. Technical indicators have recovered further from their recent lows but remain within negative levels. Bottom line, additional gains are yet to be confirmed.
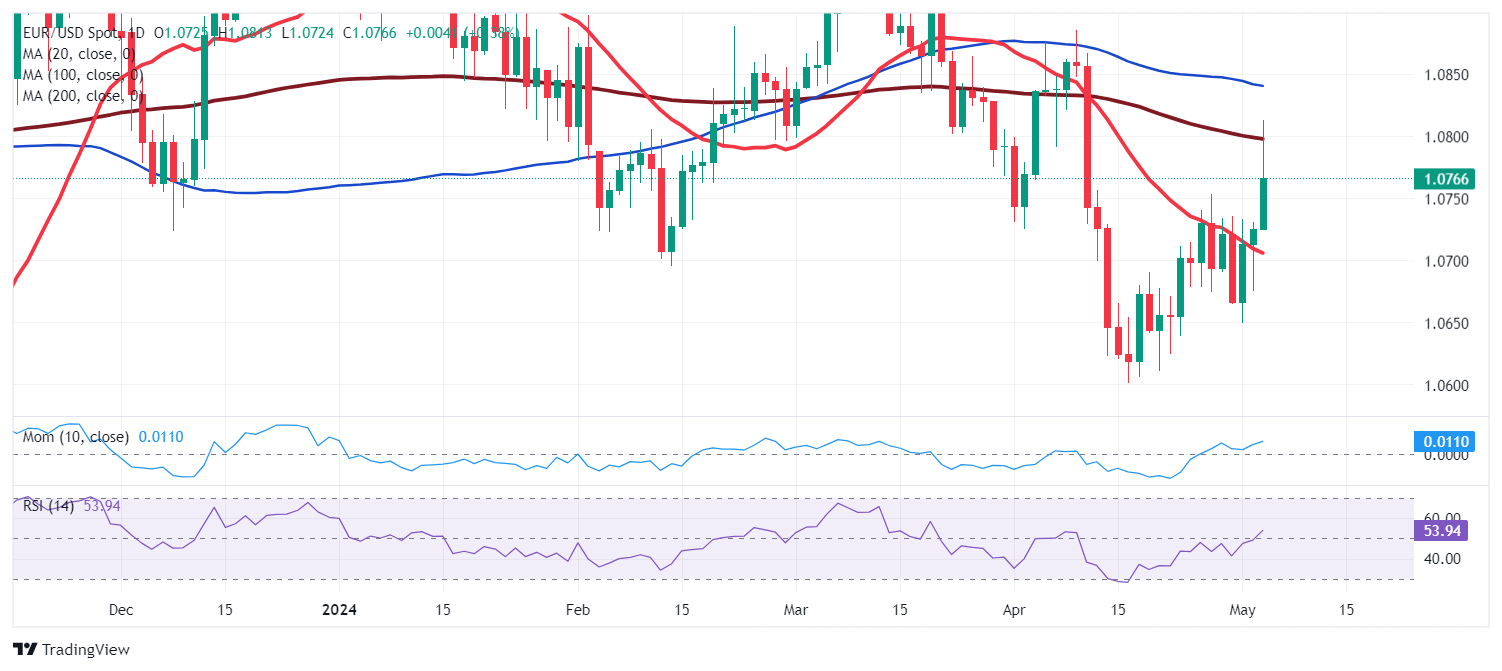
The technical picture in the daily chart favors an upward extension but falls short of confirming it. EUR/USD is indeed developing above its 20 SMA, which anyway maintains a bearish scope. The intraday rally was quickly rejected around a bearish 200 SMA, while the 100 SMA aims marginally lower above the longer one, all of which suggest reluctant buying interest. Finally, technical indicators aim north above their midlines, reflecting the latest run rather than anticipating a bullish continuation.
Beyond 1.0840, bulls will have more chances. The next resistance area comes around 1.0900, followed by the 1.0960 level. Support comes at 1.0700, followed by 1.0660 ahead of the 1.0600 mark.
Employment FAQs
Labor market conditions are a key element to assess the health of an economy and thus a key driver for currency valuation. High employment, or low unemployment, has positive implications for consumer spending and thus economic growth, boosting the value of the local currency. Moreover, a very tight labor market – a situation in which there is a shortage of workers to fill open positions – can also have implications on inflation levels and thus monetary policy as low labor supply and high demand leads to higher wages.
The pace at which salaries are growing in an economy is key for policymakers. High wage growth means that households have more money to spend, usually leading to price increases in consumer goods. In contrast to more volatile sources of inflation such as energy prices, wage growth is seen as a key component of underlying and persisting inflation as salary increases are unlikely to be undone. Central banks around the world pay close attention to wage growth data when deciding on monetary policy.
The weight that each central bank assigns to labor market conditions depends on its objectives. Some central banks explicitly have mandates related to the labor market beyond controlling inflation levels. The US Federal Reserve (Fed), for example, has the dual mandate of promoting maximum employment and stable prices. Meanwhile, the European Central Bank’s (ECB) sole mandate is to keep inflation under control. Still, and despite whatever mandates they have, labor market conditions are an important factor for policymakers given its significance as a gauge of the health of the economy and their direct relationship to inflation.
Author

Valeria Bednarik
FXStreet
Valeria Bednarik was born and lives in Buenos Aires, Argentina. Her passion for math and numbers pushed her into studying economics in her younger years.

















