US Dollar steady despite softer PMI data
- The US Dollar trades in the green at the start of the US trading session.
- European PMIs collapsed in September, while US PMI's are holding up for now.
- The US Dollar Index pops higher and tries to reclaim 101.00.

The US Dollar (USD) gets to keep its gains booked already in early Monday trading during European trading hours. The Greenback saw substantial inflow after traders fled the Euro which got punished after substantially weaker Purchase Manager data (PMI's) out of Germany and France. The US PMI's are looking resilient with even a slight beat on expectations for the Services sector.
On the economic data front, the comparison thus has been made when it comes to both the Services and Manufacturing sectors for Europe, the United Kingdom and the US. Europe is lagging with both sectors deeper into contraction or at least at the brink of falling into it. The UK and US PMI's are outpacing the European ones, with a punished Euro and a positive US Dollar as result.
Daily digest market movers: Gloomy Europe
- The preliminary US S&P Global PMIs for September have been released:
- Services data came in at 55.4, above the expected 55.2 and a touch softer than the 55.7 previously.
- Manufacturing reading came in lower at 47, below the expected 48.5 and lower than the previous 47.9 number.
- The Composite number came in at 54.4 against 54.6 previously.
- US Federal Reserve speakers are set to shine their light with some comments on the current monetary policy stance:
- At 12:00 GMT, Federal Reserve Bank of Atlanta President Raphael Bostic delivered a virtual speech about the US economic outlook at the Distinguished Speakers Seminar convened by the European Economics and Financial Centre at the University of London. Bostic confirmed he supported a 50 basis point rate cut, but does not confirm the size of a future move.
- Near 14:15 GMT, Federal Reserve Bank of Chicago President Austan Goolsbee delivers a speech about monetary policy and the US economy at the annual National Association of State Treasurers meeting in Chicago.
- Around 17:00 GMT, Federal Reserve Bank of Minneapolis President Neel Kashkari participates in a Q&A hosted by the Greater Kansas City Chamber of Commerce at the Science Museum of Minnesota.
- Equity markets are starting to turn green in the assumption that in Europe, the European Central Bank (ECB) will need to cut more and turn more dovish in order to support growth. This is seen as positive for equities. European equities are up on the day by less than 0.50% while US equities are in the green as well.
- The CME Fedwatch Tool shows a 50.6% chance of a 25-basis-point rate cut at the next Fed meeting on November 7, while 49.4% is pricing in another 50-basis-point rate cut.
- The US 10-year benchmark rate trades at 3.78 and prints a fresh two-week high.
US Dollar Index Technical Analysis: Data driven moves
The US Dollar Index (DXY) seemed incapable of making a move higher last week when the Fed pulled the trigger on that 50 basis point rate cut. The Greenback could be the comeback kid this week, with the PMI releases on Monday probably painting a whole other picture for traders to consider. The European performance might be far bleaker than the US one, which means that the US Dollar deserves an upgrade (appreciation) to where it was trading last week.
The upper level of the September range remains at 101.90. Further up, the index could go to 103.18, with the 55-day Simple Moving Average (SMA) at 102.59 along the way. The next tranche up is very misty, with the 100-day SMA at 103.71 and the 200-day SMA at 103.78, just ahead of the big 104.00 round level.
On the downside, 100.62 (the low from December 28, 2023) is the first support, which could point to more weakness ahead. Should that take place, the low from July 14, 2023, at 99.58, will be the next level to look out for. If that level gives way, early levels from 2023 are coming in near 97.73.
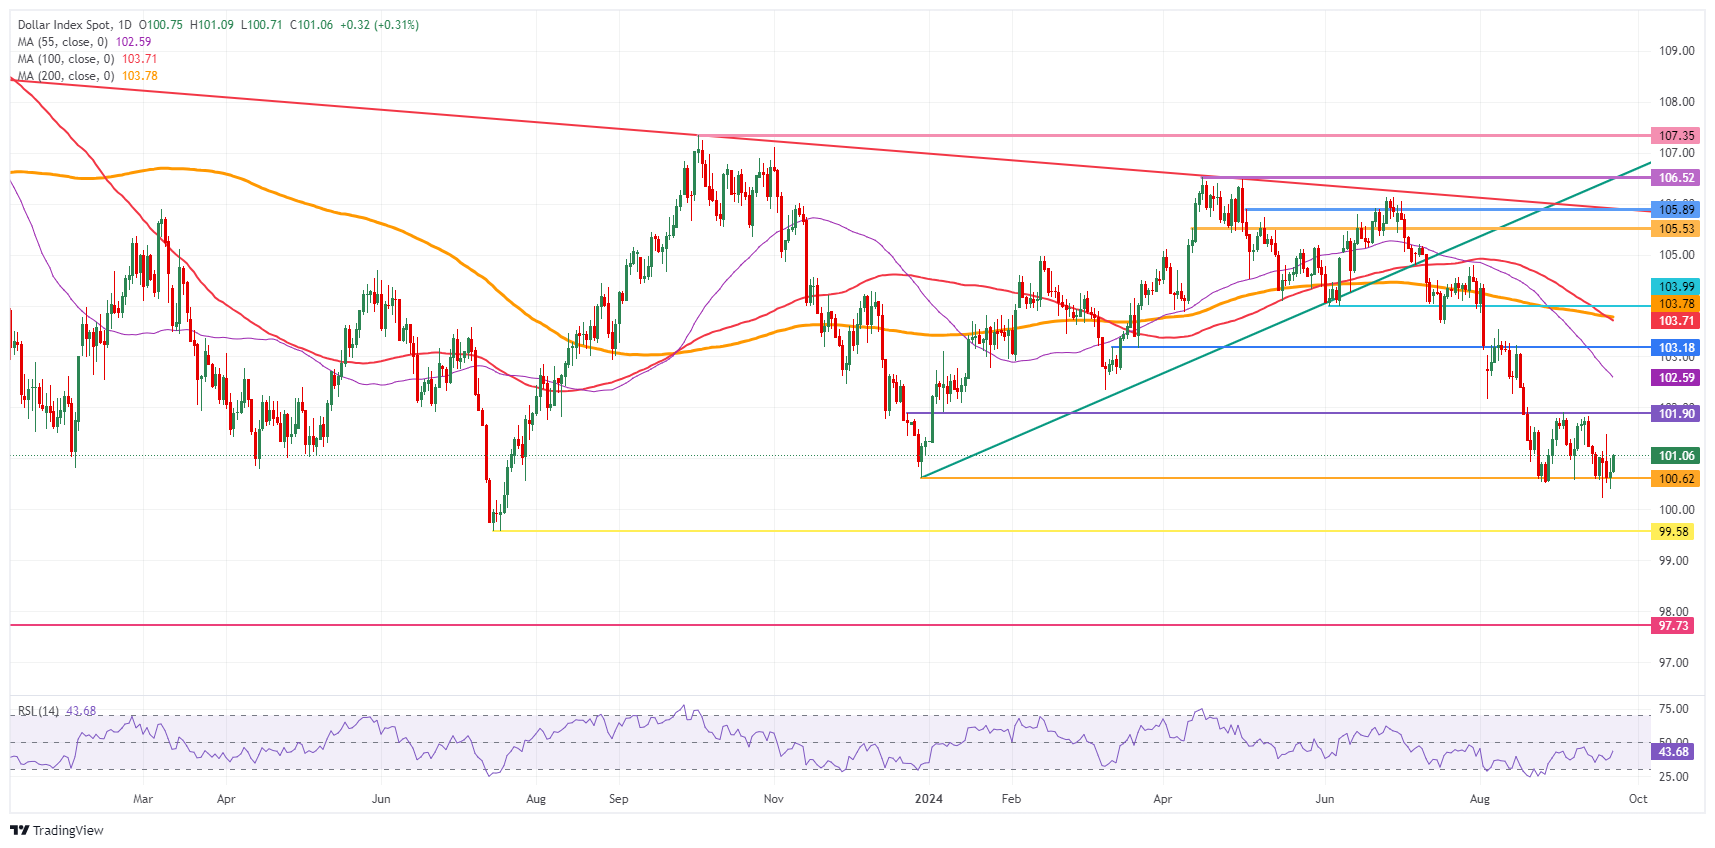
US Dollar Index: Daily Chart
ECB FAQs
The European Central Bank (ECB) in Frankfurt, Germany, is the reserve bank for the Eurozone. The ECB sets interest rates and manages monetary policy for the region. The ECB primary mandate is to maintain price stability, which means keeping inflation at around 2%. Its primary tool for achieving this is by raising or lowering interest rates. Relatively high interest rates will usually result in a stronger Euro and vice versa. The ECB Governing Council makes monetary policy decisions at meetings held eight times a year. Decisions are made by heads of the Eurozone national banks and six permanent members, including the President of the ECB, Christine Lagarde.
In extreme situations, the European Central Bank can enact a policy tool called Quantitative Easing. QE is the process by which the ECB prints Euros and uses them to buy assets – usually government or corporate bonds – from banks and other financial institutions. QE usually results in a weaker Euro. QE is a last resort when simply lowering interest rates is unlikely to achieve the objective of price stability. The ECB used it during the Great Financial Crisis in 2009-11, in 2015 when inflation remained stubbornly low, as well as during the covid pandemic.
Quantitative tightening (QT) is the reverse of QE. It is undertaken after QE when an economic recovery is underway and inflation starts rising. Whilst in QE the European Central Bank (ECB) purchases government and corporate bonds from financial institutions to provide them with liquidity, in QT the ECB stops buying more bonds, and stops reinvesting the principal maturing on the bonds it already holds. It is usually positive (or bullish) for the Euro.
Author

Filip Lagaart
FXStreet
Filip Lagaart is a former sales/trader with over 15 years of financial markets expertise under its belt.

















