EUR/USD drifts into familiar midranges after Friday goes nowhere
- EUR/USD wraps up trading week at familiar technical levels near 1.0700.
- German data broadly missed the mark early Friday.
- US PCE inflation met expectations, but good mood was brief.

EUR/USD pivoted into a sideways grind on Friday, wrapping up a flat trading week after Fiber traders found little reason to push the pair meaningfully in either direction. German import prices and labor figures broadly miss the mark, and US Personal Consumption Expenditure Price Index (PCE) inflation failed to spark a meaningful bid despite printing at forecasts.
German Unemployment Change clocked in higher than expected, showing 19K German consumers were added to unemployment figures in June. This is more than the forecast 15K, but still below the previous month’s 25K. The German Unemployment Rate also ticked higher to 6.0% versus the forecast hold at 5.9%.
Forecasting the Coming Week: Data, politics and the ECB Forum take centre stage
On the US side, Core PCE Price Index inflation ticked down for the year ended May, cooling to 2.6% from the previous 2.8%. While the decline in key inflation readings will be a welcome addition to recent inflation data, it failed to spark a meaningful risk-on bid for investors as the figure was nowhere near cool enough to drive the Federal Reserve (Fed) towards an accelerated pace of interest rate cuts.
US Personal Income rose 0.5% MoM in May compared to the forecast 0.4% and previous 0.3%, but US Personal Spending came in at 0.2% versus the forecast 0.3%, and the previous print saw a slight downside revision to 0.1% from the initial 0.2%.
The University of Michigan (UoM) Consumer Sentiment Index rose to 68.2 in June, up from the previous 65.6 and climbing over the forecast 65.8. However, UoM 5-year Consumer Inflation Expectations ticked down to 3.0% in June, down from the previous 3.1% but inflation expectations continue to ride well above the Fed’s inflation target of 2% annually.
Coming up next week, European inflation numbers will be landing on markets early in the week with German Harmonized Index of Consumer Prices (HICP) figures on Monday, followed by pan-EU HICP inflation on Tuesday. Next week also marks the next US Nonfarm Payrolls (NFP) labor data dump, slated for next Friday.
EUR/USD technical outlook
The Fiber ran directly into technical barriers on Friday, getting swamped out at the 200-hour Exponential Moving Average (EMA) at 1.0715. The pair continue to battle with the 1.0700 handle, and bidders have been thus far failing to throw off a near-term pattern of lower highs.
EUR/USD daily candlesticks continue to grind out a rough consolidation pattern as the pair struggles on the low side of the 200-day EMA at 1.0788. As buyers continue to show signs of exhaustion, a downside break to 2024’s bottom bids at 1.0600 becomes increasingly likely.
EUR/USD hourly chart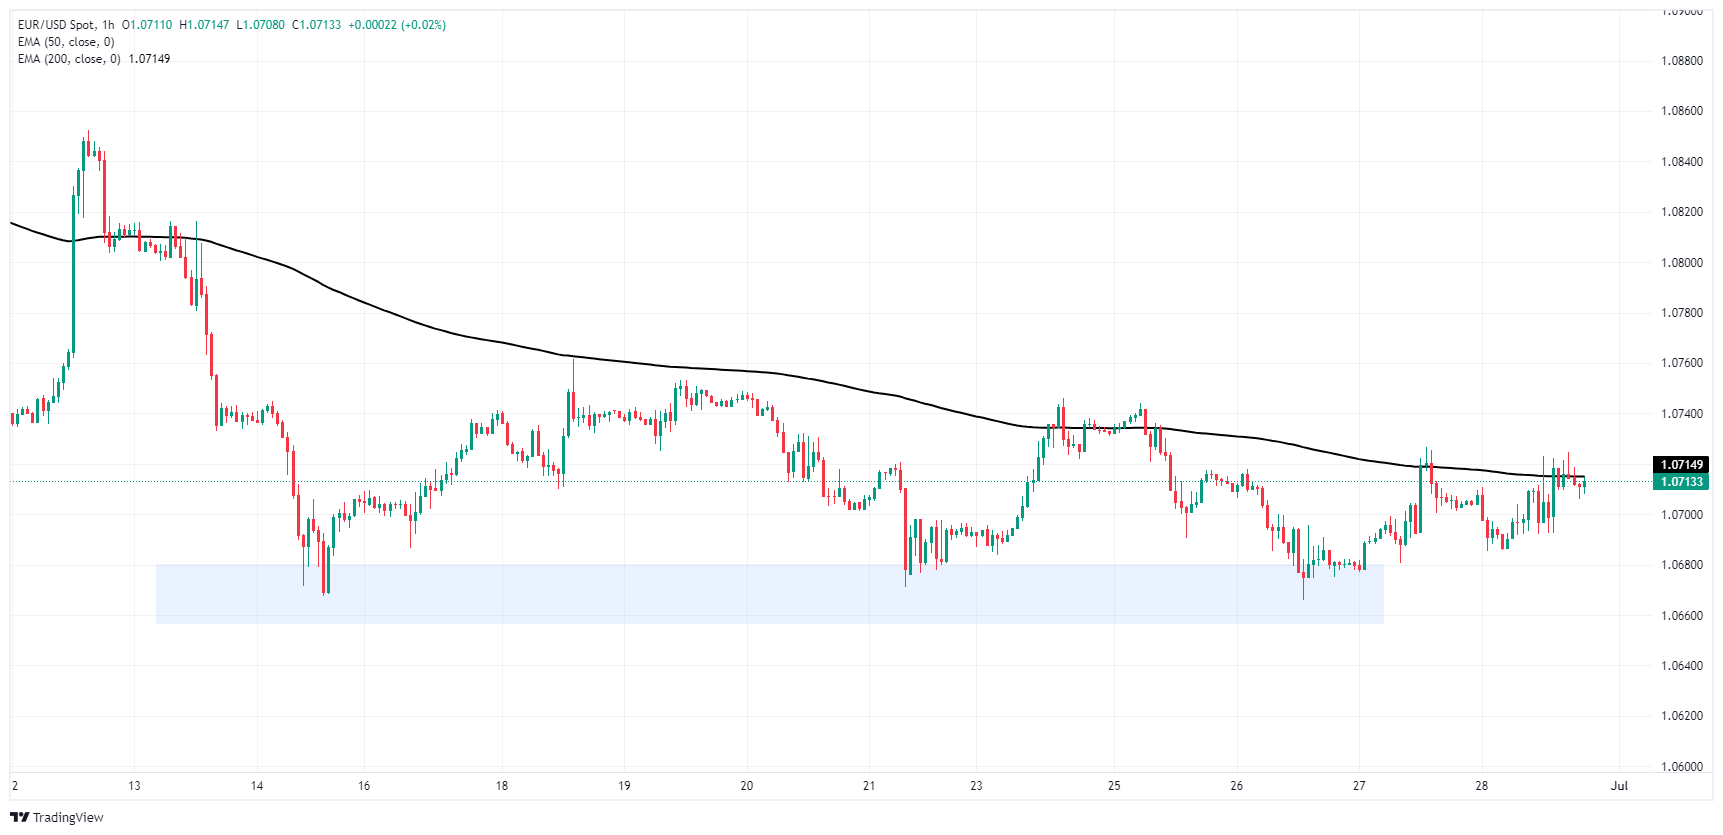
EUR/USD daily chart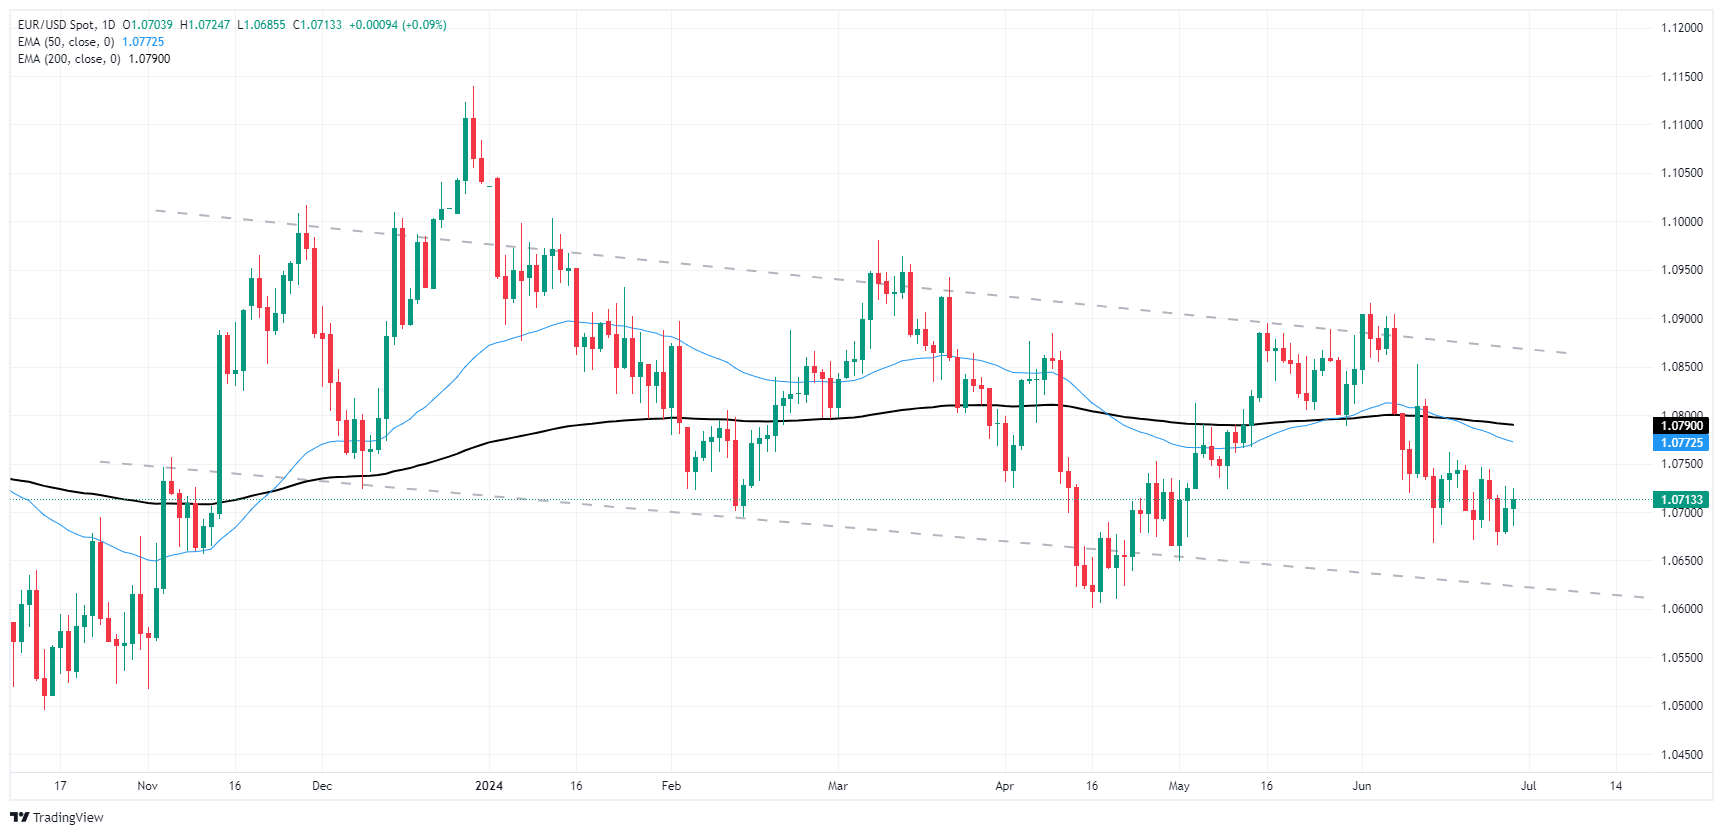
Euro FAQs
The Euro is the currency for the 20 European Union countries that belong to the Eurozone. It is the second most heavily traded currency in the world behind the US Dollar. In 2022, it accounted for 31% of all foreign exchange transactions, with an average daily turnover of over $2.2 trillion a day. EUR/USD is the most heavily traded currency pair in the world, accounting for an estimated 30% off all transactions, followed by EUR/JPY (4%), EUR/GBP (3%) and EUR/AUD (2%).
The European Central Bank (ECB) in Frankfurt, Germany, is the reserve bank for the Eurozone. The ECB sets interest rates and manages monetary policy. The ECB’s primary mandate is to maintain price stability, which means either controlling inflation or stimulating growth. Its primary tool is the raising or lowering of interest rates. Relatively high interest rates – or the expectation of higher rates – will usually benefit the Euro and vice versa. The ECB Governing Council makes monetary policy decisions at meetings held eight times a year. Decisions are made by heads of the Eurozone national banks and six permanent members, including the President of the ECB, Christine Lagarde.
Eurozone inflation data, measured by the Harmonized Index of Consumer Prices (HICP), is an important econometric for the Euro. If inflation rises more than expected, especially if above the ECB’s 2% target, it obliges the ECB to raise interest rates to bring it back under control. Relatively high interest rates compared to its counterparts will usually benefit the Euro, as it makes the region more attractive as a place for global investors to park their money.
Data releases gauge the health of the economy and can impact on the Euro. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the single currency. A strong economy is good for the Euro. Not only does it attract more foreign investment but it may encourage the ECB to put up interest rates, which will directly strengthen the Euro. Otherwise, if economic data is weak, the Euro is likely to fall. Economic data for the four largest economies in the euro area (Germany, France, Italy and Spain) are especially significant, as they account for 75% of the Eurozone’s economy.
Another significant data release for the Euro is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought after exports then its currency will gain in value purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















