|

USD/JPY analysis: steady around 111.00 ahead of Japanese Q2 GDP

USD/JPY Current price: 110.99

  • Japanese Q2 GDP and US inflation to be a make it or break it for bears.
  • Dollar´s broad strength offset by slipping T-yields when it comes to USD/JPY.
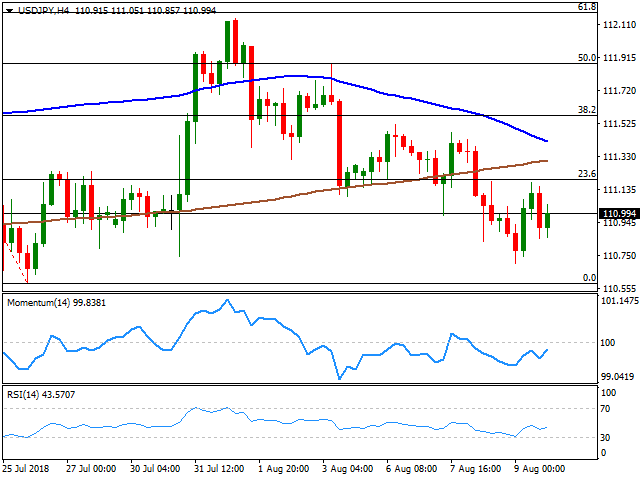
The USD/JPY pair fell to 110.70 at the beginning of the day, a fresh weekly low, bouncing from the level to be capped again by selling interest aligned around the 111.20 level. The lack of relevant macroeconomic releases combined with risk-related political headlines, which have benefited only partially the safe-haven yen, keep the pair within familiar levels, although the risk remains skewed to the downside, as the Japanese currency is finding support is slipping US Treasury yields, with the yield on the benchmark 10-year Treasury note down to 2.93%.  Japanese data released early Thursday was generally discouraging, as Machinery Orders posted a larger-than-expected decline of -8.8% in June, well below the expected -1.3%, leaving the annual reading up at 0.3% vs. the expected 0.5% The Machine Tool Orders preliminary for July, however, came above the previous month reading, advancing from 11.4% to 13.0%. The country will start Friday offering preliminary Q2 GDP figures, seen bouncing from the -0.2% printed in Q1 to 0.3%. The annualized reading is foreseen at 1.4% after the -0.6% from the previous quarter. The pair trades around the 111.00 figure, and the 4 hours chart shows that the 100 SMA continues heading south above the current level and above the 200 SMA, indicating an increasing downward potential without confirming it. Technical indicators in the mentioned chart have recovered from their daily lows, but are unable to define a direction, hovering right below their midlines. US inflation could be a make it or break it for bears, who can't seem to be able to fully take over the pair.

Support levels: 110.55 110.20 109.80

Resistance levels: 111.20 111.60 111.90

View Live Chart for the USD/JPY

Author

Valeria Bednarik

Valeria Bednarik was born and lives in Buenos Aires, Argentina. Her passion for math and numbers pushed her into studying economics in her younger years.


More from Valeria Bednarik
Share:

Editor's Picks

AUD/USD consolidates above 0.7000; remains close to monthly top

AUD/USD holds steady above 0.7000 during the Asian session on Friday, trading just below the previous day's monthly low amid diverging forces. A hawkish RBA continues to support the Aussie, while the recent decline in US bond yields keeps the US Dollar depressed near a three-week low. However, oil-driven inflation fears reinforce Fed hike bets, which, along with geopolitical risks, could benefit the safe-haven buck and cap the currency pair.

USD/JPY bounces off one-month low; climbs to 157.00 amid reviving USD demand

USD/JPY rebounds from the 156.00 neighborhood, or a one-month low touched during Friday’s Asian session, with bulls looking to extend momentum beyond 157.00 amid the emergence of some US Dollar buying. Meanwhile, Japan's National CPI rose to a nine-month peak and reaffirmed BoJ rate-hike bets, which could support the Japanese Yen and cap gains for the currency pair.

Gold treads water around $4,000

Gold prices maintain its offered stance in place at the end of the week, hovering around the key $4,000 threshold per troy ounce. The persistent selling bias in the precious metal comes amid decent gains in the US Dollar and an acceptable rebound in US Treasury yields across the curve, all alongside further upside traction in crude oil prices.

Week ahead: Central bank and earnings bonanza could roil markets

After joining the rate-hike club in September, the Federal Reserve looks set to stand pat in October, waiting to assess more data before deciding to hike again. Whilst this isn’t an unusual move for a central bank, it somewhat contradicts Fed Chair Kevin Warsh’s new mantra of data dependency and zero forward guidance.

CFTC Report: WTI rally runs ahead of positioning
The week in one sentence: WTI prices surged while speculative longs were cut in the week to October 20, creating the clearest price/positioning divergence. Sterling and the Canadian Dollar led the constructive currency shift, while Yen longs also rebuilt. Speculators turned less constructive on the WTI, reducing their net exposure to around 89.3K contracts.
What November 3 means for the Fed's rate path and the US Dollar

The USD faces a decisive period ahead of the November 3 midterm elections. While markets anticipate another interest rate increase from the Fed in December, the battle for control of Congress could reshape fiscal policy expectations and, indirectly, the path of US monetary policy in 2027.















