US Dollar Weekly Forecast: Markets’ focus now looks at US CPI data
- The US Dollar Index clinches its sixth weekly gain in a row.
- The Federal Reserve cut its primary interest rate by 25 bps on Thursday.
- Investors will closely follow potential Trump policies and data.

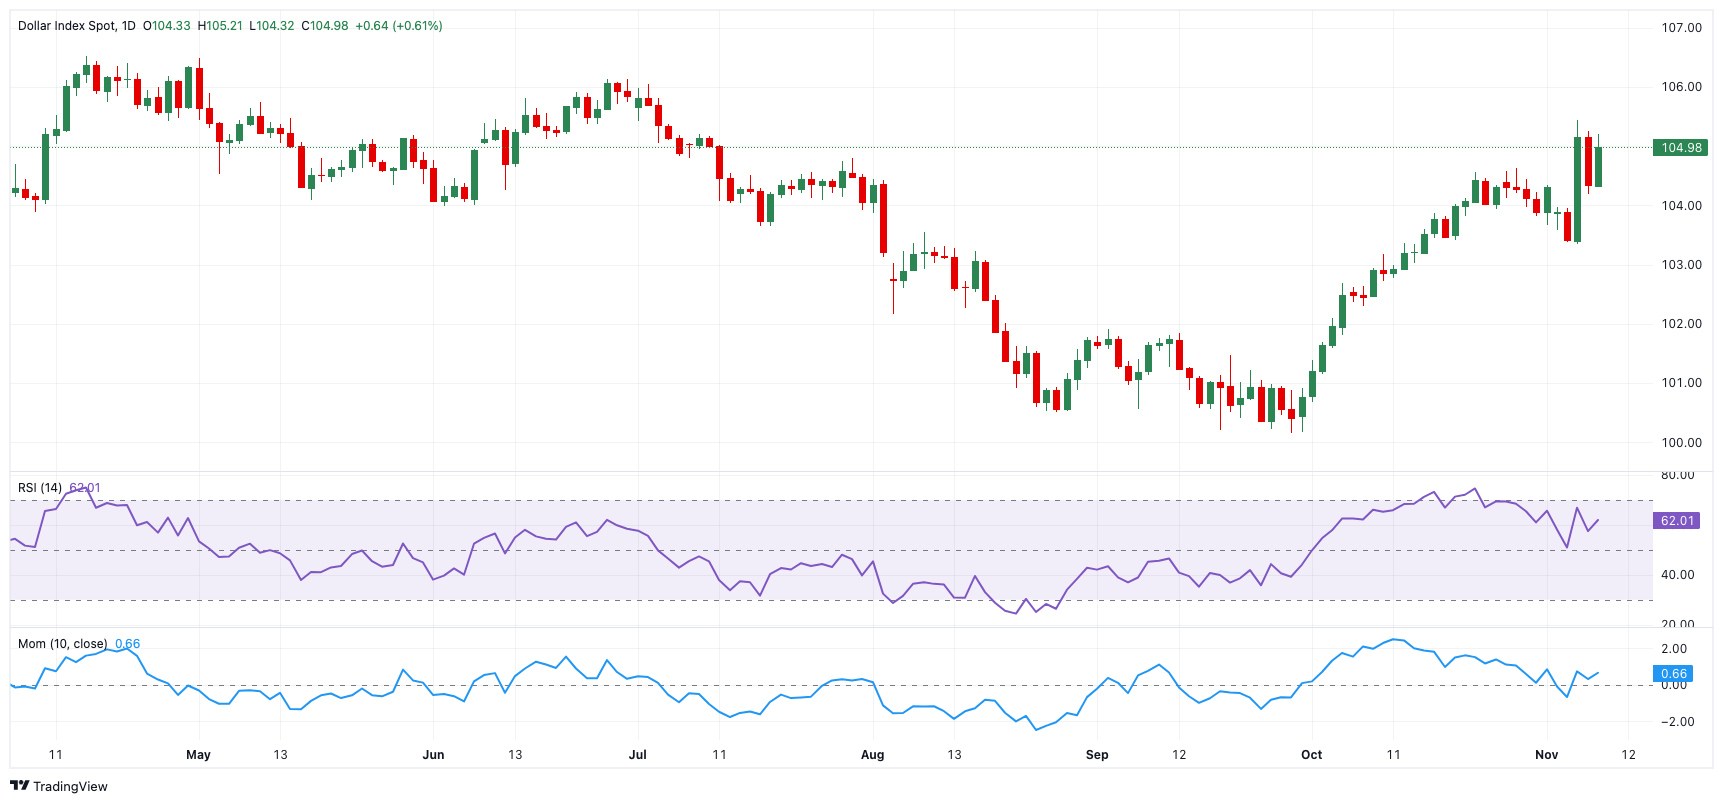
The US Dollar (USD) has been on a roll for yet another week, notching up a solid performance over the past few days and extending its winning streak to a sixth straight week. The Greenback even surpassed the critical 200-day Simple Moving Average (SMA) at 103.85 when measured by the Dollar Index (DXY) — a level we haven't seen since early July.
The ongoing rally kicked off early in October, and it was constantly fed by firm results from US fundamentals and, more recently, by the so-called “Trump trade” and the Federal Reserve’s (Fed) interest rate cut at its November 7 gathering.
As we look ahead, the US Dollar's outlook could turn even more bullish if it manages a decisive breakout above the key 200-day SMA.
And back to inflation!
Following the widely anticipated quarter-point interest rate reduction by the Fed earlier this week, Chair Jerome Powell acknowledged that recent inflation figures have been higher than expected. However, he also pointed out that downside risks remain, noting that the Fed might need to adjust its pace of rate cuts.
Powell also suggested that if inflation continues to surprise on the upside, rate cuts could be more gradual, while a faster deterioration in the labour market might prompt the central bank to cut rates more aggressively.
Against that, Powell once again reiterated that the US economy remains in a “very” good place, and substantially more so if we bring its G10 peers into focus.
The “Trump trade” should initially be supportive of the Dollar
In light of the return of Donald Trump to office, with Republican control in both the Senate and possibly the House, we could see a major shake-up in US economic policy.
In fact, President-elect Trump has over and over voiced his intentions to increase tariffs on Chinese and European goods, a move that is expected to drive up inflation while putting a brake on economic growth in the longer run.
On the flip side, tax cuts and deregulation from a Republican-led Congress might help cushion the potential impact on economic growth, but their consequences might increase the budget deficit, fanning the flames of the resurgence of inflationary pressure.
As the Fed has started shifting its focus away from inflation to take a closer look at the labour market, the overall performance of the US economy is now playing a key role in shaping future policy moves.
In October, the Nonfarm Payrolls (NFP) report showed a modest gain of just 12K jobs, with the Unemployment Rate steady at 4.1%. While the ADP report beat expectations, weekly jobless claims have been suggesting that the labour market remains strong, although it's cooling off at a snail’s pace.
Recent GDP data also paints a positive picture, countering fears of an impending recession. At this point, neither a soft landing nor a hard landing seems likely.
Compared to other G10 economies, the US stands out, which could keep the US Dollar on a stronger footing against its peers over the medium to long term.
Deciphering rate moves: A global outlook
The Eurozone, Japan, Switzerland, and the United Kingdom are grappling with increasing deflationary pressure and economic activity becoming increasingly unpredictable.
In response, the European Central Bank (ECB) cut interest rates by 25 basis points on October 17, though officials refrained from providing additional details or forward guidance on the central bank's future actions.
Similarly, the Swiss National Bank (SNB) also reduced rates by 25 basis points on September 26.
The Bank of England (BoE) recently reduced its policy rate by 25 basis points to 4.75%, as the MPC believes the new budget will boost both growth and inflation, which means they can’t afford to lower interest rates too quickly or by too much. However, they still expect inflation to come under control by the end of 2025.
The Reserve Bank of Australia (RBA) held rates steady at its November 5 meeting but struck a cautious note, with markets anticipating a potential cut to the official cash rate (OCR) by May 2025.
Over in Japan, the Bank of Japan (BoJ) stuck to its dovish approach at the October 31 meeting, with markets expecting only a modest 25-basis-point rate hike over the coming year.
What’s up next week?
The highlight of next week will once again be the release of October's inflation data, as tracked by the Consumer Price Index (CPI). Meanwhile, the regular weekly updates on the labour market will also be in focus. They will take a backseat but still be relevant.
Additionally, it will be worth watching for any comments from Fed officials, especially in light of the recent rate cut by the central bank.
Techs on the US Dollar Index
As the US Dollar Index (DXY) continues its upward climb, the next key target is the November high of 105.44 (November 6), seconded by the June top of 106.13 (June 13).
On the downside, the November low at 103.37 (November 5) comes first prior to the provisional 100-day and 55-day SMAs at 103.07 and 102.35, respectively, ahead of the 2024 bottom of 100.15 (September 27).
Additionally, the Relative Strength Index (RSI) on the daily chart rose past the 63 level, while the Average Directional Index (ADX) has inched up to above 38, indicating that the current trend has moderate strength.
Economic Indicator
Consumer Price Index (MoM)
Inflationary or deflationary tendencies are measured by periodically summing the prices of a basket of representative goods and services and presenting the data as The Consumer Price Index (CPI). CPI data is compiled on a monthly basis and released by the US Department of Labor Statistics. The MoM figure compares the prices of goods in the reference month to the previous month.The CPI is a key indicator to measure inflation and changes in purchasing trends. Generally, a high reading is seen as bullish for the US Dollar (USD), while a low reading is seen as bearish.
Read more.Next release: Wed Nov 13, 2024 13:30
Frequency: Monthly
Consensus: 0.2%
Previous: 0.2%
Source: US Bureau of Labor Statistics
The US Federal Reserve has a dual mandate of maintaining price stability and maximum employment. According to such mandate, inflation should be at around 2% YoY and has become the weakest pillar of the central bank’s directive ever since the world suffered a pandemic, which extends to these days. Price pressures keep rising amid supply-chain issues and bottlenecks, with the Consumer Price Index (CPI) hanging at multi-decade highs. The Fed has already taken measures to tame inflation and is expected to maintain an aggressive stance in the foreseeable future.
US Dollar PRICE Today
The table below shows the percentage change of US Dollar (USD) against listed major currencies today. US Dollar was the strongest against the Australian Dollar.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 0.81% | 0.56% | -0.15% | 0.40% | 1.48% | 1.04% | 0.50% | |
| EUR | -0.81% | -0.25% | -0.93% | -0.41% | 0.66% | 0.23% | -0.31% | |
| GBP | -0.56% | 0.25% | -0.69% | -0.16% | 0.91% | 0.48% | -0.06% | |
| JPY | 0.15% | 0.93% | 0.69% | 0.55% | 1.62% | 1.19% | 0.64% | |
| CAD | -0.40% | 0.41% | 0.16% | -0.55% | 1.06% | 0.64% | 0.11% | |
| AUD | -1.48% | -0.66% | -0.91% | -1.62% | -1.06% | -0.42% | -0.96% | |
| NZD | -1.04% | -0.23% | -0.48% | -1.19% | -0.64% | 0.42% | -0.54% | |
| CHF | -0.50% | 0.31% | 0.06% | -0.64% | -0.11% | 0.96% | 0.54% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the US Dollar from the left column and move along the horizontal line to the Japanese Yen, the percentage change displayed in the box will represent USD (base)/JPY (quote).
Author

Pablo Piovano
FXStreet
Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.
















