Three fundamentals for the week: Two central bank decisions and one sensitive US
- The Reserve Bank of Australia is set to strike a more hawkish tone, reversing its dovish shift.
- Policymakers at the Bank of England may open the door to a rate cut in June.
- Economists fear a stagflationary picture from a measure of US consumer confidence.

Will hawks or doves have the upper hand? The tug-of-war between the camps triggers action in all financial markets, which await a clear turning point. Decisions from two central banks in Australia and the UK, and a sneak peek into US consumer sentiment in May could provide some answers.
1) RBA set for a hawkish shift, boosting the Aussie and the Kiwi
Tuesday, 4:30 GMT, press conference at 5:30 GMT. Stubborn inflation is not only an American thing – but also a phenomenon weighing on the land down under. The most recent Consumer Price Index (CPI) data for the first quarter came out at 1% QoQ and 3.5% YoY, above expectations and boosting the Aussie.
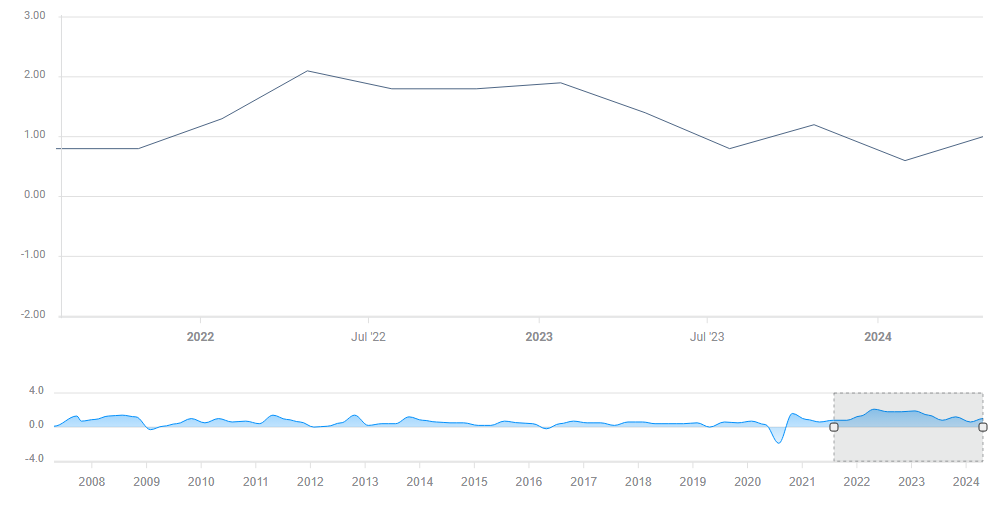
Australian CPI QoQ. Source: FXStreet
The figures came only two weeks after Reserve Bank of Australia Governor Michelle Bullock opened the door to easing monetary policy. Inflation seemed to have been beaten, allowing for a more dovish tone, and that may change now.
The RBA is set to leave its Cash Rate unchanged at 4.35%, but push back against imminent rate cuts. Governor Bullock will meet the press after the decision, and will likely refrain from any commitments to immediate action given uncertainty about Chinese growth and other factors moving the Australian economy. Nevertheless, a rejection of rate cuts could prop up the Aussie.
The Kiwi may be another beneficiary of any RBA hawkishness. The New Zealand economy is closely tied to the Australian one. A tougher stance could dampen broader markets by painting a picture of resistance to cutting rates worldwide.
2) BoE's Super Thursday may open the door to rate cuts
Thursday, 11:00 GMT, press conference at 11:30 GMT. There is no support among the Monetary Policy Committee to raise rates – that is what we learned last time, but is there more appetite to cut interest rates? That is the key question for markets.
The BoE is likely to leave rates unchanged but signal its next moves. Another member may join Swati Dhingra in backing lower borrowing costs, which would instantly weigh on the Pound. Afterward, the quarterly Monetary Policy Report (MPR) would move markets.
The UK economy is slowing down, and unemployment is creeping up. These factors may push Governor Andrew Bailey and his colleagues to lower their forecasts and signal an initial rate cut in the summer.
UK Unemployment hits 4.2%
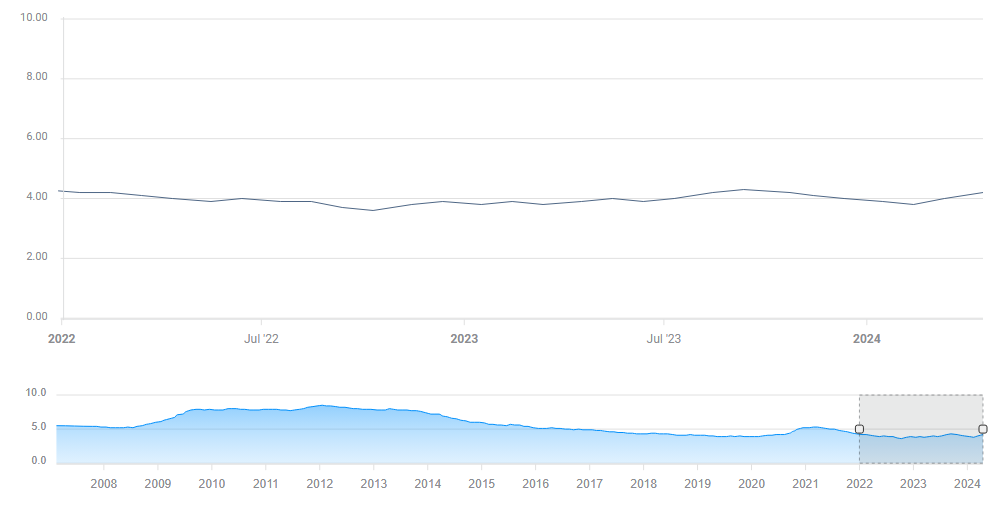
UK unemployment. Source: FXStreet
Then, Governor Bailey takes the stage. He tends to be gloomy, and he could further signal that rate cuts are coming. An upcoming cut is priced in, so Sterling's retreat would be minimal unless the outlook is for a disaster.
However, the slow retreat in UK inflation could trigger a pushback against cuts. Headline CPI dropped to 3.2%, down from 3.4% but above 3.1% expected.
If Bailey surprises with a tougher tone, he would lift not only the Pound but also the Euro. The European Central Bank is set to kick off an easing cycle next month, and a hawkish BoE could raise some second thoughts about it. Like with Australia and New Zealand, Britain and Europe are closely linked.
3) US Consumer Sentiment to show lower confidence, stubborn inflation concerns
Friday, 14:00 GMT. The University of Michigan publishes its preliminary read of Consumer Sentiment for May – and it does not promising. Fed Chair Jerome Powell rejected the term stagflation, which refers to the 1970s. The economy is not stagnating and inflation at under 4% is ways below levels seen back then.
Nevertheless, the closely watched survey is set to reflect a drop in confidence and higher inflation expectations – the worst of most of the world. I expect markets to focus on the inflation component and dismiss the headline confidence measure. Why?
While the central bank is watching employment more than before, the fight against inflation is the main offer. Moreover, headline consumer sentiment also reflects politics, with supporters of the current president always being happier than those backing the other party.

UoM 5-year inflation expectations. Source: FXStreet.
This release is the last one of the week and tends to unleash volatility as investors close trades ahead of the weekend. However, moves triggered by the data tend to be short-lived, occasionally providing opportunities to go against the trend.
Author

Yohay Elam
FXStreet
Yohay is in Forex since 2008 when he founded Forex Crunch, a blog crafted in his free time that turned into a fully-fledged currency website later sold to Finixio.

















