Forecasting the Coming Week: Focus remains on data and rate cut bets

Another gloomy week saw the Greenback tumble to five-month lows near 103.20, extending its breach of the key 200-day SMA as investors continued to assess the probability of a 50 bps rate cut in September following the disappointing US NFP in July, the FOMC event, and renewed and rising concerns over a potential slowdown of the US economy. A glimpse at next week’s docket highlights the RBA interest rate decision, some Fed speakers, and key releases in the service sector.
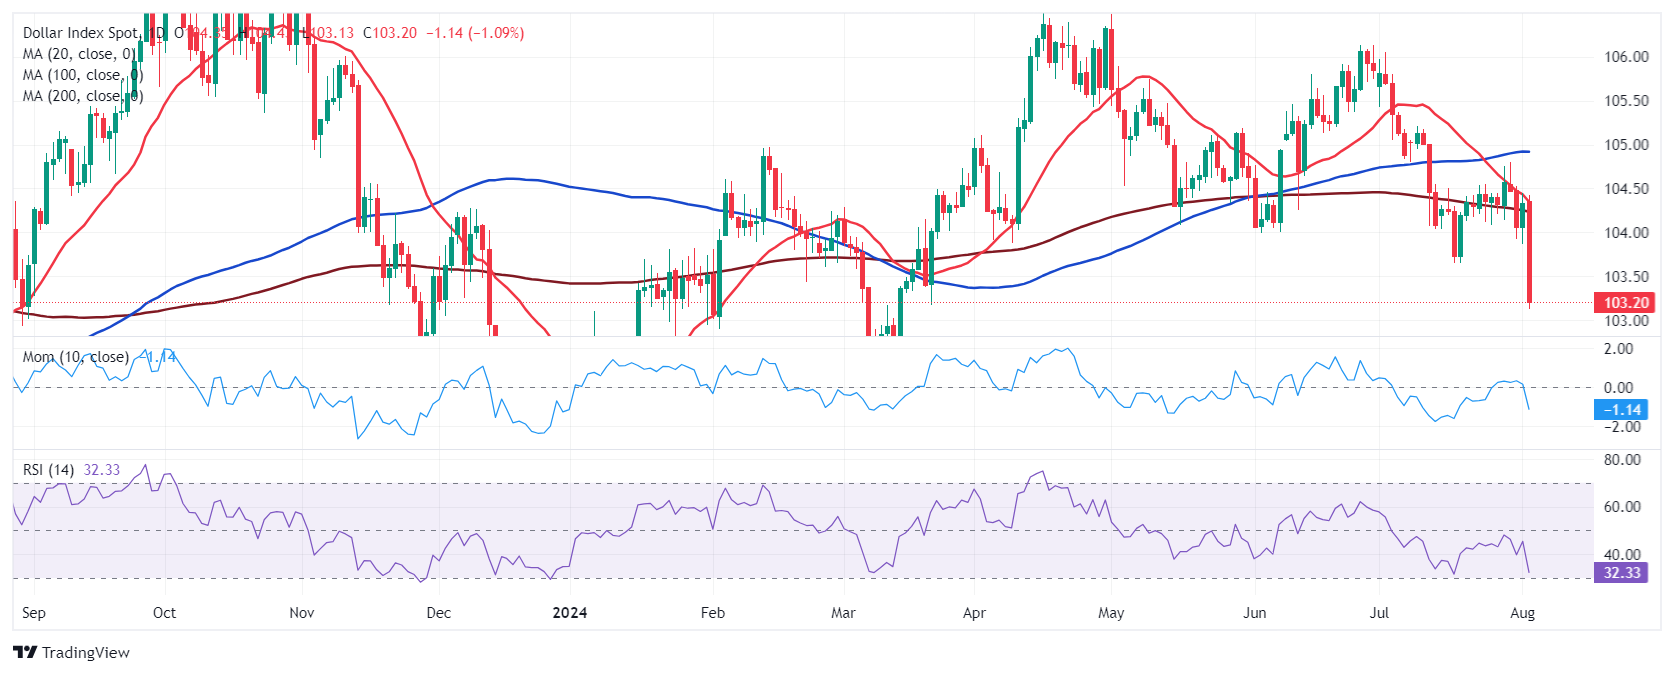
The US Dollar Index (DXY) maintained its downward bias in place well south of the 104.00 barrier, retreating for the second week in a row. The final S&P Global Services PMI is due on August 5, seconded by the ISM Services PMI. The Balance of Trade results are expected on August 6, along with the RCM/TIPP Economic Optimism Index and the API report on US crude oil inventories. Next on the calendar are the weekly Mortgage Applications tracked by MBA, followed by the EIA report on US crude oil stockpiles on August 7, while the weekly Initial Jobless Claims and Wholesale Inventories will be published on August 8.
EUR/USD met much-needed oxygen in the wake of poor US NFP and advanced to fresh tops near the 1.0900 region, turning positive on the weekly chart. The final HCOB Services PMIs in Germany and the euro area are due on August 5, seconded by Producer Prices in the bloc. On August 6, the HCOB Construction PMIs in the Euroland and Germany are due, along with Factory Orders in Germany. Still in Germany, Balance of Trade figures and Industrial Production are expected on August 7. The final Inflation Rate in Germany will close the docket on August 9.
GBP/USD rose markedly and reclaimed the area beyond 1.2800 the figure in response to the intense sell-off in the Greenback post-NFP. The final S&P Global Services PMI comes on August 5, while the BRC Retail Sales Monitor and the S&P Global Construction PMI are expected on August 6. The Halifax House Price Index will be unveiled on August 7, and the RICS House Price Balance is due on August 8.
USD/JPY collapsed to five-month lows and retested the 147.00 neighbourhood following the strong decline in the US Dollar and declining US yields. The final Jibun Bank Services PMI is due on August 5 followed by the BoJ Minutes. August 6 will feature Household Spending and Average Cash Earnings. The flash Coincident Index and Leading Economic Index will be published on August 7, while Bank Lending results, weekly Foreign Bond Investment, the BoJ Summary of Opinions, and the Eco Watchers Survey are all due on August 8.
AUD/USD partially reversed the weekly retracement and managed to flirt with the 0.650 region at the end of the week. The final Judo Bank Services PMI comes on August 5, seconded by the RBA meeting on August 6. The Ai Group Industry index comes on August 7, followed by the NAB Business Confidence index on August 8.
Anticipating Economic Perspectives: Voices on the Horizon
- The Fed’s Daly is due to speak on August 5.
- The Fed’s Barkin and the RBA’s Bullock speak on August 8.
Central Banks: Upcoming Meetings to Shape Monetary Policies
- The RBA is expected to keep its policy rate at 4.35% on August 6.
- The Reserve Bank of India (RBI) and Banxico meet on August 8.
Author

Pablo Piovano
FXStreet
Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.
















