EUR/USD Weekly Forecast: US PCE inflation as a first hint to Fed’s next move
- The Federal Reserve trimmed the benchmark rate by 50 basis points.
- United States Personal Consumption Expenditures Price Index under scrutiny.
- EUR/USD eases ahead of the weekly close, but bulls aim for higher highs.
The EUR/USD pair flirted once again with the 1.1200 threshold this week but finally settled at around 1.1160, holding onto modest gains. The pair has been trying to conquer the mark since mid-August in anticipation of the Federal Reserve’s (Fed) monetary policy announcement.
Federal Reserve’s new monetary cycle
The Fed delivered a 50-basis-point (bps) rate cut, kick-starting a new policy cycle in an aggressive manner. As a result, the US Dollar (USD) fell sharply, albeit then, Chair Jerome Powell poured enough cold water to avert panic action across financial boards.
The decision was made not only because inflation levels are closer to the Fed’s goal of around 2% but also to support the economy. The Federal Open Market Committee (FOMC) noted they have “gained greater confidence that inflation is moving sustainably” towards their goal.
As a result, the Summary of Economic Projections (SEP), more commonly known as dot plot, showed FOMC members are anticipating another 50 bps this year, 100 bps trims in 2025, and 50 bps more in 2026 to a terminal rate of 2.9%. As Powell noted, they are on their way to a more neutral rate.
Powell, however, clarified that future decisions will continue to depend on macroeconomic data and that those will made meeting by meeting. His cautious words kept fears in check. Following the initial rallies in Wall Street, US indexes closed with modest losses, while the USD recovered the lost ground, only to resume its slide when a new day started. And it is quite logical: Federal Reserve’s officials opted for an aggressive move amid unexpressed concerns about economic progress. The Fed’s decision to maintain rates at record highs for longer has posed a significant risk for growth. Luckily for Powell & co, it worked pretty well, as the United States (US) will likely dodge a recession.
Easing government bond yields, with the 2-year Treasury note yielding less than the 10-year one, is a good sign of confidence about a potential recovery.
The Fed key rate is now between 4.75% and 5%. It is worth remembering the European Central Bank (ECB) has already trimmed interest rates, with the benchmark rate on the Deposit Facility now standing at 3.5%. Despite the Fed’s aggressive measure, it’s still better to hold USD than Euro.
Europe keeps struggling
Other than that, European data kept disappointing. The German ZEW Survey showed a sharp contraction in Economic Sentiment, with the index plummeting in the country to 3.6 and in the Eurozone to 9.3 in September. The assessment of the current situation in Germany worsened to -84.5 from -77.3. Additionally, the EU confirmed that the Harmonized Index of Consumer Prices (HICP) rose by 2.2% in the year to August, while the monthly increase was downwardly revised to 0.1%. Finally, on Friday, the EU reported that September’s preliminary Consumer Confidence improved to -12.9 from -13.5 in August.
Across the pond, the US reported that Retail Sales increased by 0.1% in August, better than the 0.2% decline expected.
Focus shifts to inflation
The upcoming week will start with the Hamburg Commercial Bank (HCOB) and S&P Global releasing the preliminary estimates of the September Purchasing Managers Indexes (PMIs) for European economies and the US on Monday.
Additionally, on Thursday, the US will release the final estimate for the second quarter of Gross Domestic Product (GDP) and August Durable Goods Orders. Finally on Friday, the country will publish the August Personal Consumption Expenditures (PCE) Price Index, the Fed’s favorite inflation gauge. Investors will be looking for divergences in the figure to rush to price in what the Fed may do in November. Financial markets are counting on a 25 bps rate cut, yet if inflation falls much more than anticipated, it will open the door for speculation of another 50 bps trim.

EUR/USD technical outlook
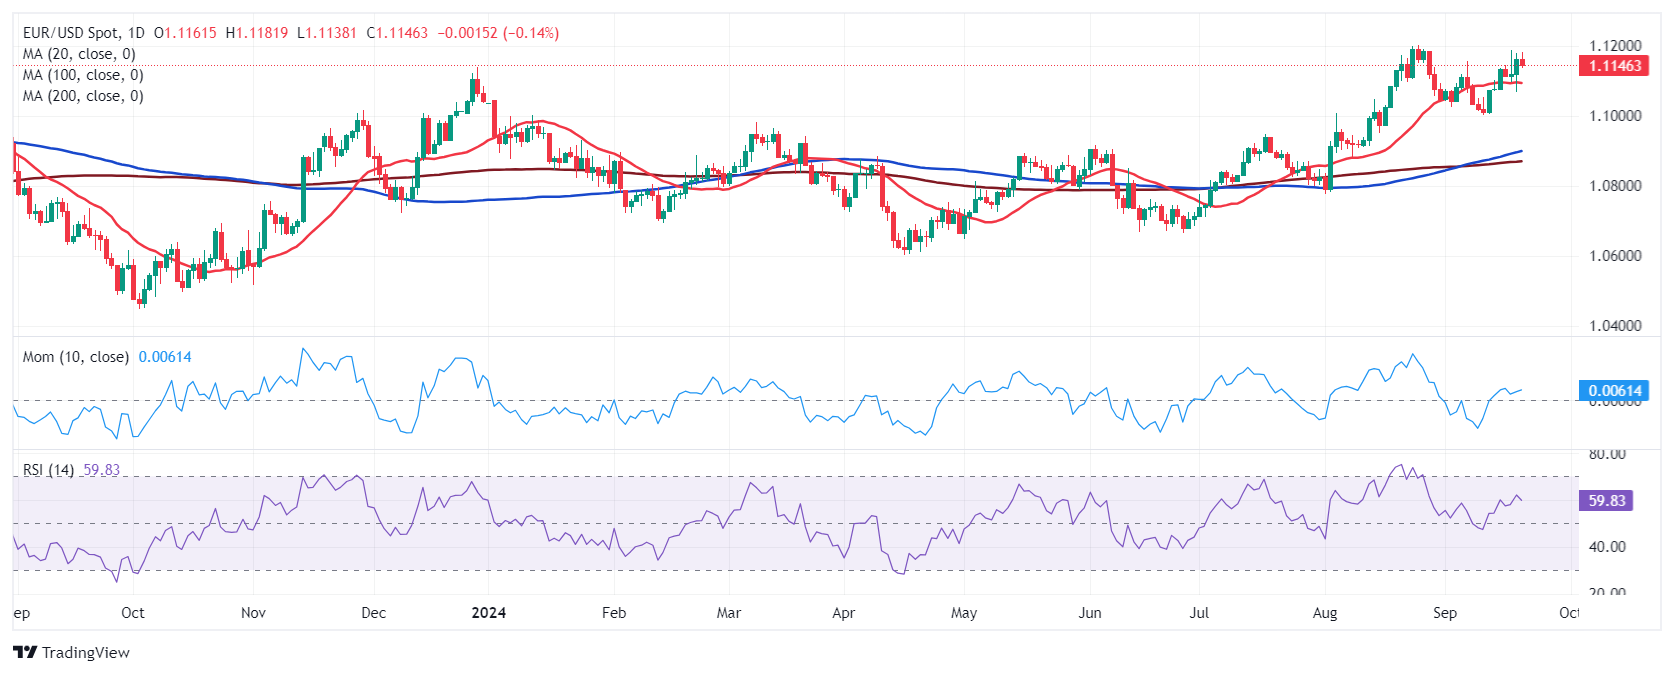
The EUR/USD pair needs to clearly conquer the 1.1200 mark to confirm what technical readings suggest: That is, buyers are in control. In the weekly chart, technical indicators have extended their upward slopes within positive levels, maintaining their upward strength. At the same time, the pair met buyers around a flat 200 Simple Moving Average (SMA), providing dynamic support in the 1.1050 price zone. The 20 and 100 SMAs, in the meantime, grind north below the longer one, reflecting increased buying interest.
EUR/USD is also bullish in its daily chart despite the bullish momentum receding. The 20 SMA provides support in the 1.1090 region, while the longer moving averages grind higher far below the shorter one. Finally, technical indicators have turned marginally lower but remain within positive levels.
Support, beyond the mentioned 1.1090 and 1.1050, comes at the 1.1000 mark, while once above 1.1200, the pair could run towards 1.1240 and 1.1300, with a longer-term aim of 1.1470.
Fed FAQs
Monetary policy in the US is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability and foster full employment. Its primary tool to achieve these goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, it raises interest rates, increasing borrowing costs throughout the economy. This results in a stronger US Dollar (USD) as it makes the US a more attractive place for international investors to park their money. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates to encourage borrowing, which weighs on the Greenback.
The Federal Reserve (Fed) holds eight policy meetings a year, where the Federal Open Market Committee (FOMC) assesses economic conditions and makes monetary policy decisions. The FOMC is attended by twelve Fed officials – the seven members of the Board of Governors, the president of the Federal Reserve Bank of New York, and four of the remaining eleven regional Reserve Bank presidents, who serve one-year terms on a rotating basis.
In extreme situations, the Federal Reserve may resort to a policy named Quantitative Easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used during crises or when inflation is extremely low. It was the Fed’s weapon of choice during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy high grade bonds from financial institutions. QE usually weakens the US Dollar.
Quantitative tightening (QT) is the reverse process of QE, whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing, to purchase new bonds. It is usually positive for the value of the US Dollar.
Economic Indicator
Personal Consumption Expenditures - Price Index (YoY)
The Personal Consumption Expenditures (PCE), released by the US Bureau of Economic Analysis on a monthly basis, measures the changes in the prices of goods and services purchased by consumers in the United States (US). The YoY reading compares prices in the reference month to a year earlier. Price changes may cause consumers to switch from buying one good to another and the PCE Deflator can account for such substitutions. This makes it the preferred measure of inflation for the Federal Reserve. Generally, a high reading is bullish for the US Dollar (USD), while a low reading is bearish.
Read more.Next release: Fri Sep 27, 2024 12:30
Frequency: Monthly
Consensus: -
Previous: 2.5%
Source: US Bureau of Economic Analysis
Author

Valeria Bednarik
FXStreet
Valeria Bednarik was born and lives in Buenos Aires, Argentina. Her passion for math and numbers pushed her into studying economics in her younger years.

















