US Dollar steady after Jobless Claims opens door for Fed easing in December
- The US Dollar flattens on Thursday after Fed’s Williams said he sees inflation cooling and interest rates falling.
- Investors see Jobless Claims data come in softer while further comments from Fed officials are expected.
- The US Dollar Index trades flat around 106.50, still looking for support to bounce off from.

The US Dollar (USD) is trading flat on Thursday at around 106.50 when tracked by the DXY US Dollar Index, afterNew York Fed President John Williams said that inflation continues to cool down, opening the door for a further drop in interest rates. The US Dollar has traded broadly sideways in recent days, influenced by swings coming from the war between Russia and Ukraine and, more recently, disappointing earnings from Nvidia.
The US economic calendar features on Thursday the weekly Jobless Claims data and the Philadelphia Fed Manufacturing Survey for November came in under expectations. In the Jobless Claims the Continuing Claims part is starting to near the 2 million head count. Meanwhile the Philadelphia Manufacturing number for November fell in contraction, and adds weight to the call for a rate cut in December.
Daily digest market movers: US data softens
- New York Fed President John Willams delivered some dovish comments.Williams said that inflation is heading lower and interest rates should fall further.
- Fed’s Williams meanwhile received additional support from Richmond Fed President Tom Barkin who said in an interview on Thursday with the Financial Times that inflation will continue to drop, Bloomberg reports.
- On the geopolitical front, Ukraine reports that Russia has launched a ballistic missile, Bloomberg reports.
- At 13:30 GMT, the Weekly Jobless Claims for the week ending November 15 came in at 213,000, lower than the expected 220,000. Main concern though is the surge in Continuing Claims where the head count is jumping to 1.908 million people against 1.872 million last week.
- The Philadelphia Fed Manufacturing Survey for November tumbled lower into contraction by -5.5, substantially lower than the positive 8 and 10.3 seen previously.
- Existing Home Sales data for October jumped to 3.96 million units, beating the 3.93 million expectation and the previous 3.83 million.
- A batch of Fed speakers are due this Thursday:
- Near 13:45 GMT, Federal Reserve Bank of Cleveland President Beth Hammack delivers welcome remarks at the 2024 Financial Stability Conference organized by the Cleveland Fed. Hammack will speak again at 17:30 GMT at the same event.
- At 17:25 GMT, Federal Reserve Bank of Chicago President Austan Goolsbee participates in a moderated Q&A session at an event organized by the Central Indiana Corporate Partnership in Indianapolis.
- Federal Reserve Bank of Kansas City President Jeffrey Schmid delivers a speech about economic growth and monetary policy at an event organized by the Fairfax Industrial Association in Kansas City at 17:40 GMT.
- Federal Reserve Vice Chair for Supervision Michael Barr closes off at 21:40 GMT, participating in a discussion about banks and artificial intelligence at the 2024 FinRegLab AI Symposium in Washington DC.
- Equities are whipsawing through the day between gains and losses. The Nasdaq is the main loser, down near 0.50%.
- The CME FedWatch Tool is pricing in another 25 basis points (bps) rate cut by the Fed at the December 18 meeting by 55.5%. A 44.5% chance is for rates to remain unchanged. While the interest-rate cut scenario is still the most probable, traders have significantly pared back some of the rate-cut bets compared with a week ago, when a rate-cut possibility was still at 72%.
- The US 10-year benchmark rate trades at 4.38%, sliding further away from the high printed on Friday at 4.50%.
US Dollar Index Technical Analysis: Stay away if you can
The US Dollar Index (DXY) is supported by the constant safe-haven inflow on the geopolitical tensions escalating between Russia and Ukraine. Traders should keep in mind that if the recent escalation eases and both parties head into any kind of ceasefire talks, the Greenback could retreat.
After a brief test and a firm rejection last Thursday, the 107.00 round level remains in play on the topside. A fresh yearly high has already been reached at 107.07, which is the statistical level to beat. Further up, a fresh two-year high could be reached if 107.35 is broken.
The first level on the downside is 105.93, the closing from November 12. A touch lower, the pivotal 105.53 (April 11 high) should avoid any downturns towards 104.00. Should the DXY fall all the way towards 104.00, the big figure and the 200-day Simple Moving Average at 103.95 should catch any falling knive formation.
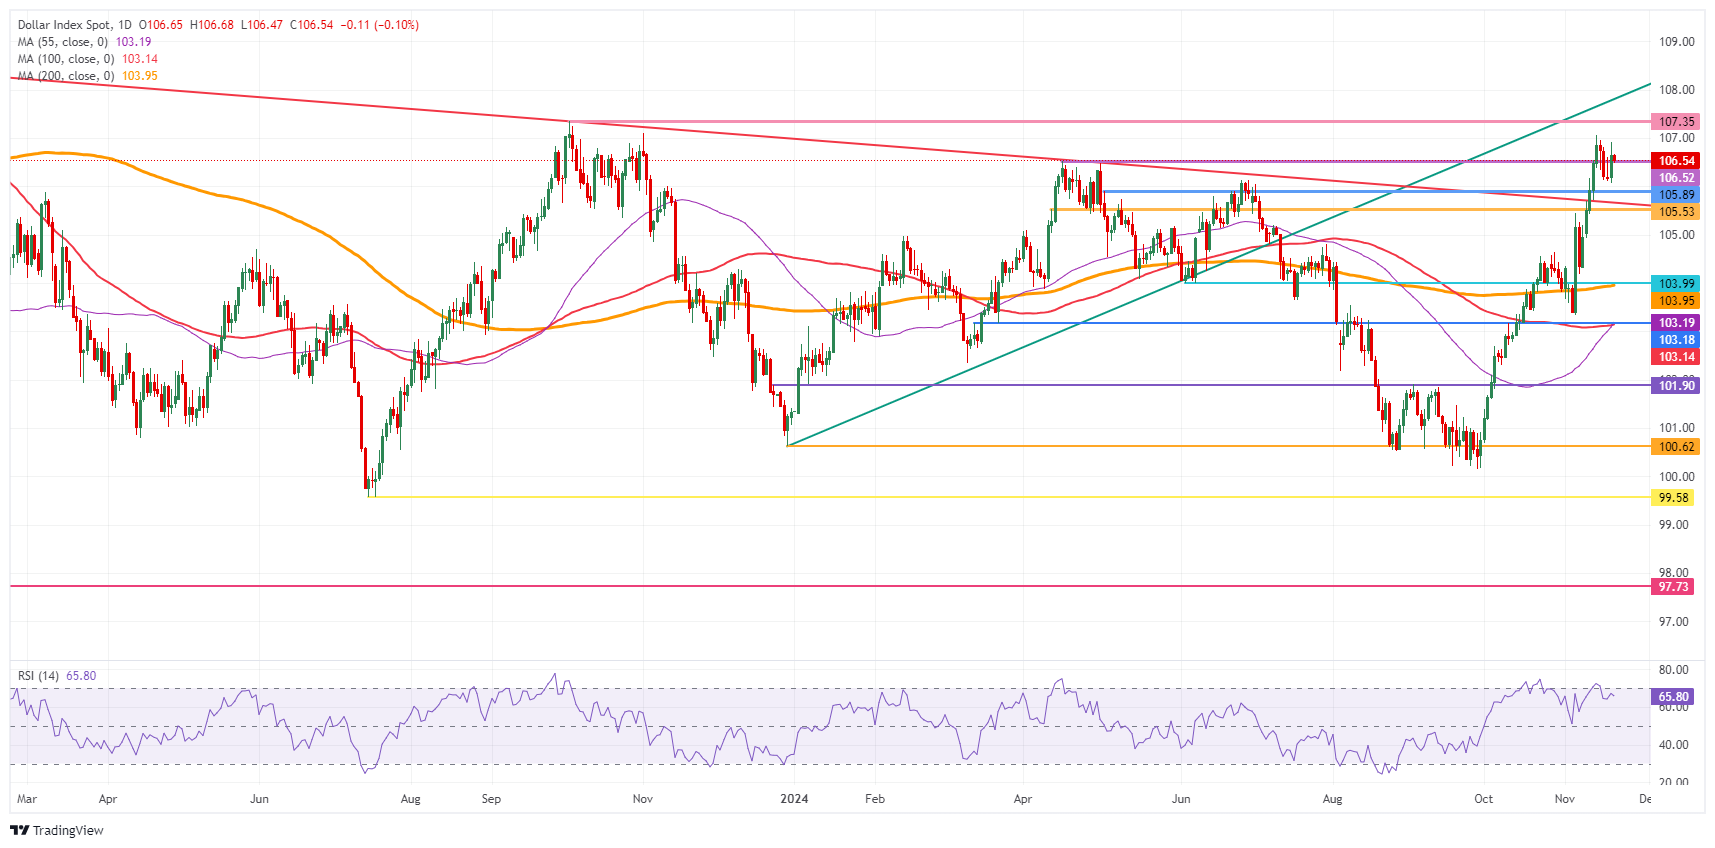
US Dollar Index: Daily Chart
Central banks FAQs
Central Banks have a key mandate which is making sure that there is price stability in a country or region. Economies are constantly facing inflation or deflation when prices for certain goods and services are fluctuating. Constant rising prices for the same goods means inflation, constant lowered prices for the same goods means deflation. It is the task of the central bank to keep the demand in line by tweaking its policy rate. For the biggest central banks like the US Federal Reserve (Fed), the European Central Bank (ECB) or the Bank of England (BoE), the mandate is to keep inflation close to 2%.
A central bank has one important tool at its disposal to get inflation higher or lower, and that is by tweaking its benchmark policy rate, commonly known as interest rate. On pre-communicated moments, the central bank will issue a statement with its policy rate and provide additional reasoning on why it is either remaining or changing (cutting or hiking) it. Local banks will adjust their savings and lending rates accordingly, which in turn will make it either harder or easier for people to earn on their savings or for companies to take out loans and make investments in their businesses. When the central bank hikes interest rates substantially, this is called monetary tightening. When it is cutting its benchmark rate, it is called monetary easing.
A central bank is often politically independent. Members of the central bank policy board are passing through a series of panels and hearings before being appointed to a policy board seat. Each member in that board often has a certain conviction on how the central bank should control inflation and the subsequent monetary policy. Members that want a very loose monetary policy, with low rates and cheap lending, to boost the economy substantially while being content to see inflation slightly above 2%, are called ‘doves’. Members that rather want to see higher rates to reward savings and want to keep a lit on inflation at all time are called ‘hawks’ and will not rest until inflation is at or just below 2%.
Normally, there is a chairman or president who leads each meeting, needs to create a consensus between the hawks or doves and has his or her final say when it would come down to a vote split to avoid a 50-50 tie on whether the current policy should be adjusted. The chairman will deliver speeches which often can be followed live, where the current monetary stance and outlook is being communicated. A central bank will try to push forward its monetary policy without triggering violent swings in rates, equities, or its currency. All members of the central bank will channel their stance toward the markets in advance of a policy meeting event. A few days before a policy meeting takes place until the new policy has been communicated, members are forbidden to talk publicly. This is called the blackout period.
Author

Filip Lagaart
FXStreet
Filip Lagaart is a former sales/trader with over 15 years of financial markets expertise under its belt.
















