US Dollar falls below 103 ahead of US CPI release Wednesday
- The US Dollar eases on the back of softer PPI release.
- Carry and high-beta currencies are pushing back against the US Dollar.
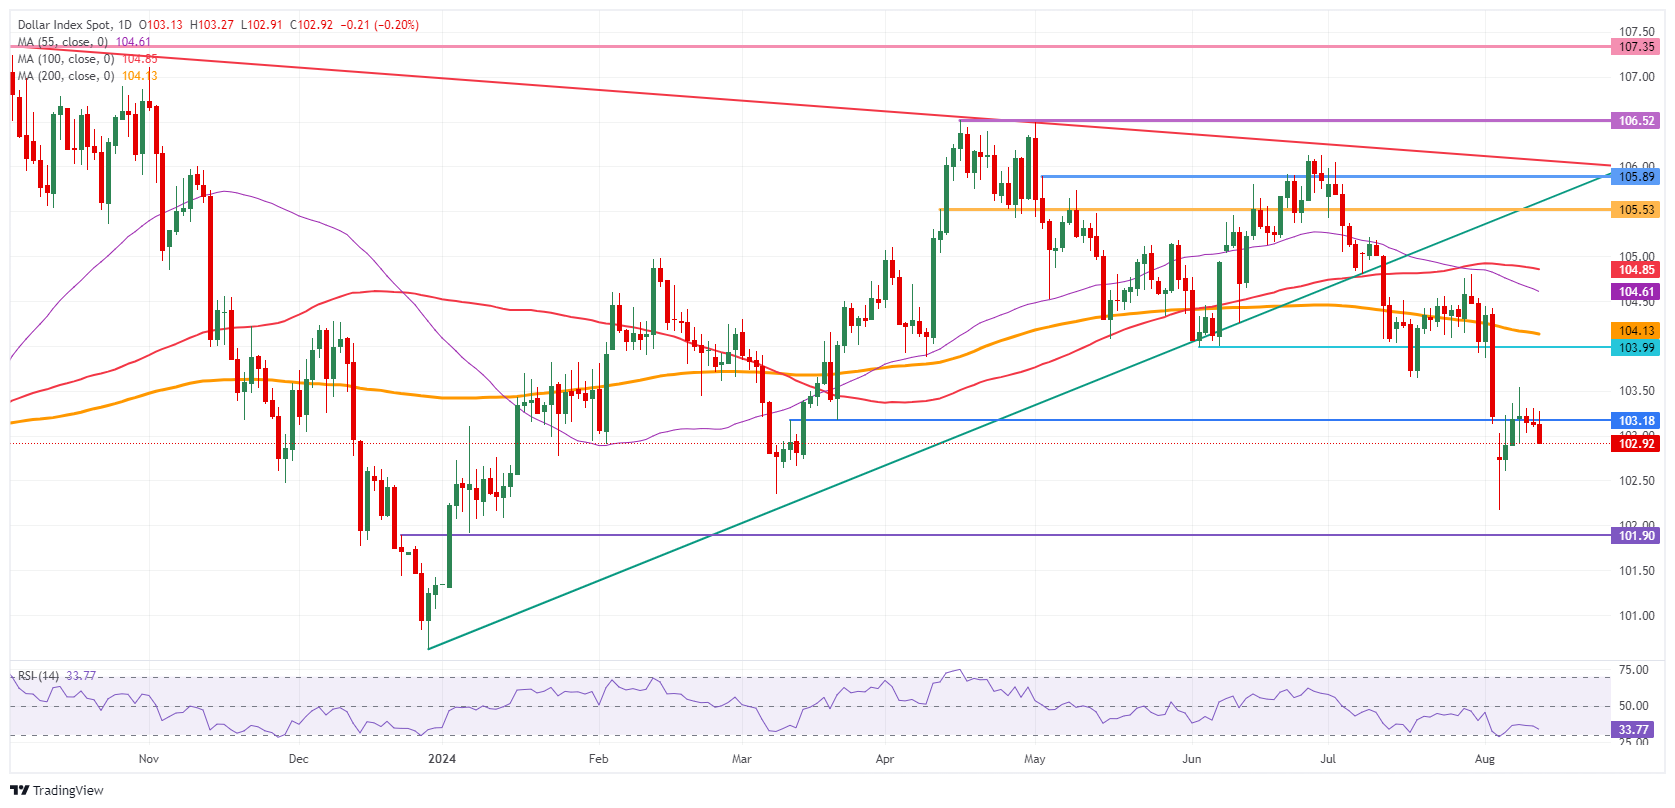
- The US Dollar index orbits around the 103.18 pivotal level.

The US Dollar (USD) trades softer on Tuesday, after the July Producer Price Index (PPI) numbers came in softer than expected. The hurted carry and high-beta trades that were on the fence last week are currently outperforming against the Greenback, with the Polish Zloty (PLN), Australian Dollar (AUD), New Zealand Dollar (NZD) and Czech Koruna (CZK) as main gainers. Still, these moves are not visible at all in the DXY chart because the US Dollar is outperforming against the Japanese Yen (JPY).
On the economic data front, the calendar is starting to pick up a bit. The Producer Price Index (PPI) came in much softer on all fronts for both the monthly and yearly figure in both the core and headline release. This adds up to expectations for Wednesday where a further disinflationary print in the US Consumer Price Index (CPI) is now the minimum base case expectation.
Daily digest market movers: PPI was too soft
- The NFIB Business Optimism Index for July came in at 93.7, coming from the 91.5 reported in June.
- At 12:30 GMT, the US Producer Price Index data for July has been released:
- Monthly headline PPI fell from 0.2% to only 0.1%. The yearly figure went from 2.7% to 2.2%.
- As for the core readings, monthly Core PPI fell to 0%, coming from 0.3%, while the yearly timeframe fell from 3% to 2.4%.
- Around 17:15 GMT, Federal Reserve Bank of Atlanta President Raphael Bostic participates in a moderated conversation at the Conference of African American Financial Professionals in Atlanta, United States.
- European and US equities are jumping in the green after the very soft PPI print for July.
- The CME Fedwatch Tool shows a 52.5% chance of a 25 basis points (bps) interest rate cut by the Fed in September against a 47.5% chance for a 50 bps cut. Another 25 bps cut (if September is a 25 bps cut) is expected in November by 38.5%, while there is a 49.7% chance that rates will be 50 bps below the current levels and and a 11.7% probability of rates being 75 basis points lower.
- The US 10-year benchmark rate trades at 3.87%, and dives lower after the soft PPI print
US Dollar Index Technical Analysis: Wash out ahead of CPI
The US Dollar Index (DXY) is getting torn between two forces. One element is that the high beta and carry traders are regaining strength after their substantially weak performance since the beginning of August. Though, the US Dollar is gaining against the Japanese Yen in the meantime.The Yen accounts for 13.6% of the DXY against no weighting at all for the Australian Dollar or the Polish Zloty, which paints a standstill picture on the DXY chart.
Still, the first level to recover, which gains importance every day, is 103.18, a level held on August 2 though snapped on August 5 in the Asian hours. Once the DXY closes above that level, next up is 104.00, which was the support from June. If the DXY can return above that level, the 200-day Simple Moving Average (SMA) at 104.15 is the next resistance to look out for.
On the downside, the oversold condition in the Relative Strength Index (RSI) indicator has eased in the daily chart and holds room again for a small leg lower. Support nearby is the March 8 low at 102.35. Once through there, pressure will start to build on 102.00 as a big psychological figure before testing 101.90, which was a pivotal level in December 2023 and January 2024.
US Dollar Index: Daily Chart
Central banks FAQs
Central Banks have a key mandate which is making sure that there is price stability in a country or region. Economies are constantly facing inflation or deflation when prices for certain goods and services are fluctuating. Constant rising prices for the same goods means inflation, constant lowered prices for the same goods means deflation. It is the task of the central bank to keep the demand in line by tweaking its policy rate. For the biggest central banks like the US Federal Reserve (Fed), the European Central Bank (ECB) or the Bank of England (BoE), the mandate is to keep inflation close to 2%.
A central bank has one important tool at its disposal to get inflation higher or lower, and that is by tweaking its benchmark policy rate, commonly known as interest rate. On pre-communicated moments, the central bank will issue a statement with its policy rate and provide additional reasoning on why it is either remaining or changing (cutting or hiking) it. Local banks will adjust their savings and lending rates accordingly, which in turn will make it either harder or easier for people to earn on their savings or for companies to take out loans and make investments in their businesses. When the central bank hikes interest rates substantially, this is called monetary tightening. When it is cutting its benchmark rate, it is called monetary easing.
A central bank is often politically independent. Members of the central bank policy board are passing through a series of panels and hearings before being appointed to a policy board seat. Each member in that board often has a certain conviction on how the central bank should control inflation and the subsequent monetary policy. Members that want a very loose monetary policy, with low rates and cheap lending, to boost the economy substantially while being content to see inflation slightly above 2%, are called ‘doves’. Members that rather want to see higher rates to reward savings and want to keep a lit on inflation at all time are called ‘hawks’ and will not rest until inflation is at or just below 2%.
Normally, there is a chairman or president who leads each meeting, needs to create a consensus between the hawks or doves and has his or her final say when it would come down to a vote split to avoid a 50-50 tie on whether the current policy should be adjusted. The chairman will deliver speeches which often can be followed live, where the current monetary stance and outlook is being communicated. A central bank will try to push forward its monetary policy without triggering violent swings in rates, equities, or its currency. All members of the central bank will channel their stance toward the markets in advance of a policy meeting event. A few days before a policy meeting takes place until the new policy has been communicated, members are forbidden to talk publicly. This is called the blackout period.
Author

Filip Lagaart
FXStreet
Filip Lagaart is a former sales/trader with over 15 years of financial markets expertise under its belt.