Mexican Peso retreats as market focus on Fed, Banxico meetings
- Mexican Peso continues its decline, impacted by disappointing Retail Sales, ahead of the Banxico rate cut.
- US Retail Sales outperform expectations, contrasting Mexico’s economic challenges and supporting the US Dollar.
- Banxico’s rate decision looms with potential for a divided vote on policy direction amid inflation concerns.
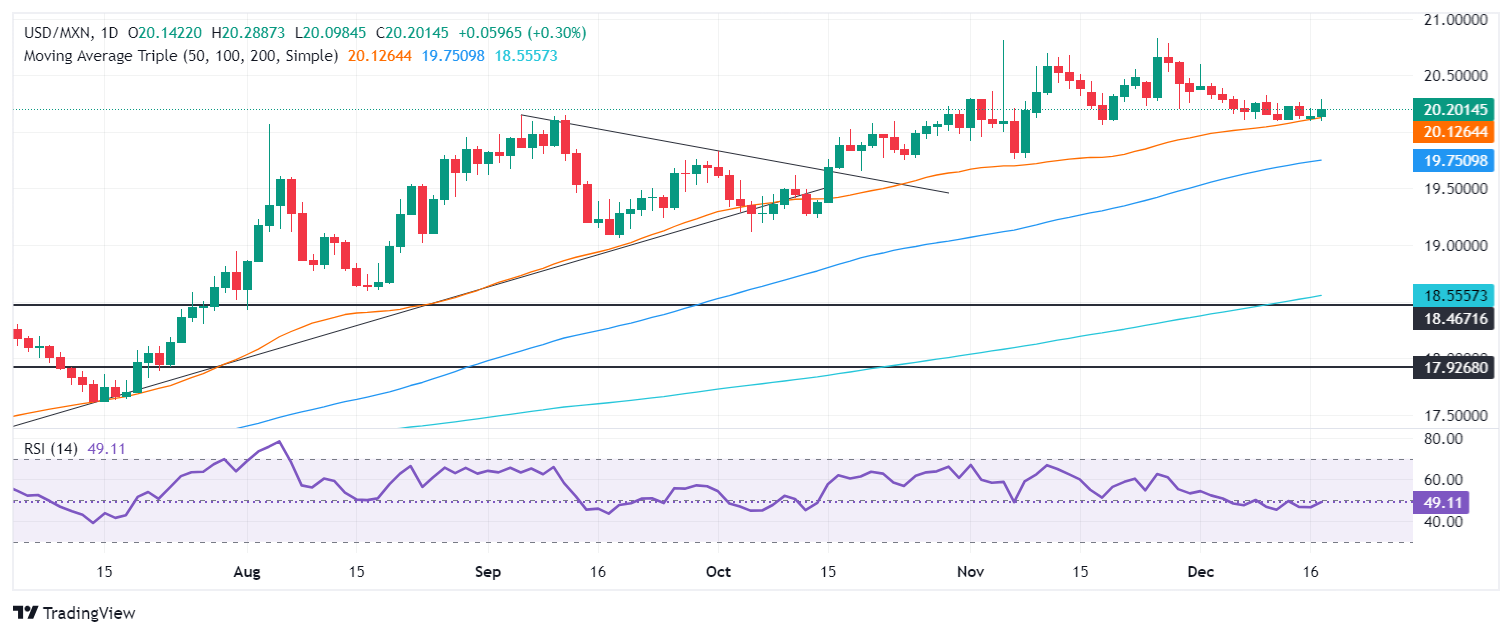
The Mexican Peso extended its losses against the Greenback for the second straight day after Mexican economic data showed that consumer spending shrank in November, an indication that the economy is slowing. This and an upbeat Retail Sales report in the United States (US) keep the USD/MXN underpinned, trading at 20.20, gaining 0.43%.
Mexican Retail Sales for October fell annually and monthly, revealed the Instituto Nacional de Estadistica Geografia e Informatica (INEGI). The date came two days short of Banco de Mexico's (Banxico) monetary policy on December 19. The institution is expected to slash the main interbank lending rate by 25 basis points (bps) to 10.00%.
Pamela Diaz Loubet, BNP Paribas Economist in Mexico, said, “Although we continue to anticipate that there will be a 25 basis point cut in December, it does seem to me that this inflation reading could open the door to a split vote (among the Banxico Governing Board). I think that it will be a debate that will be very lively in the December decision and that may begin to take shape towards 2025.”
In the US, Retail Sales in November came in strong, though Industrial Production disappointed economists. The Federal Reserve (Fed) began its two-day meeting and is expected to cut rates and release the Summary of Economic Projections (SEP). The SEP updates Fed officials' forecasts of inflation, growth, employment and interest rates with the so-called “dot plot”. The dot plot is expected to provide guidance on the Fed funds rate path.
So far, the swaps market has priced in the US Central Bank, which is projected to lower rates by 100 basis points toward the end of 2025. However, the upcoming Trump administration's inflation-prone policies could prevent the Fed from being aggressive in its easing cycle.
This week, Mexico will feature Aggregate Demand data, Private Spending, and Banxico’s interest rate decision. In the US, Building Permits, the Federal Open Market Committee (FOMC) decision, and the Fed’s preferred inflation gauge, the Core Personal Consumption Expenditures (PCE) Price Index, could dictate the monetary policy path for the US central bank.
Daily digest market movers: Mexican Peso retreats but remains at familiar levels
- Mexico’s Retail Sales dropped from 0.1% to -0.3% MoM in October, below estimates for a 0.2% growth. In the twelve months to October, sales plunged -1.2% YoY, less than the -1.6% contraction expected and improved compared to September figures of -1.5%.
- Banxico’s December private sector survey showed that most economies expect inflation to end at 4.37% in 2024 and underlying prices at 3.60%, down from November’s 3.69%. The economy is expected to grow 1.60%, up from 1.53%, and the USD/MXN exchange rate is foreseen at 20.25.
- For 2025, the Mexican CPI is projected to drop to 3.80% and the core CPI to rise to 3.72%. Gross Domestic Product (GDP) is expected at 1.12%, down from 1.20% estimated in November, and the USD/MXN spot price would end at 20.53.
- The Peso has been pressured by harsh rhetoric by US President-elect Donald Trump, who threatened to impose 25% tariffs on Mexican imports if the government doesn’t help fight illegal immigration and fentanyl trafficking.
- Analysts at JPMorgan hinted that Banxico could lower rates by 50 basis points as inflation data shows that prices are edging lower faster than expected.
- US Retail Sales rose by 0.7% MoM in November, accelerating from 0.5% in October and surpassing expectations. On a yearly basis, sales climbed to 3.8%, up from 2.9%.
- Industrial Production showed improvement in November but remained negative, coming in at -0.1% MoM, up from October's -0.4% but falling short of the 0.3% forecast.
- The CME FedWatch Tool suggests that traders had priced in a 99% chance of a quarter-point rate cut on Wednesday.
USD/MXN technical outlook: Mexican Peso falls as USD/MXN climbs toward 20.20
The USD/MXN uptrend remains in place as the pair carved a series of higher highs and higher lows, even though the pair retreated from yearly tops. However, for a bullish continuation, buyers must clear the 20.32, the December 10 high, before challenging the psychological 20.50. On further strength, the next resistance would be the December 2 daily high of 20.59, followed by the year-to-date peak of 20.82, followed by the 21.00 mark.
On the downside, if USD/MXN drops below the 50-day Simple Moving Average (SMA) at 20.10, the next support would be the 20.00 figure. Further downside is seen at the 100-day SMA at 19.73. A breach of the latter will expose 19.50.
Mexican Peso FAQs
The Mexican Peso (MXN) is the most traded currency among its Latin American peers. Its value is broadly determined by the performance of the Mexican economy, the country’s central bank’s policy, the amount of foreign investment in the country and even the levels of remittances sent by Mexicans who live abroad, particularly in the United States. Geopolitical trends can also move MXN: for example, the process of nearshoring – or the decision by some firms to relocate manufacturing capacity and supply chains closer to their home countries – is also seen as a catalyst for the Mexican currency as the country is considered a key manufacturing hub in the American continent. Another catalyst for MXN is Oil prices as Mexico is a key exporter of the commodity.
The main objective of Mexico’s central bank, also known as Banxico, is to maintain inflation at low and stable levels (at or close to its target of 3%, the midpoint in a tolerance band of between 2% and 4%). To this end, the bank sets an appropriate level of interest rates. When inflation is too high, Banxico will attempt to tame it by raising interest rates, making it more expensive for households and businesses to borrow money, thus cooling demand and the overall economy. Higher interest rates are generally positive for the Mexican Peso (MXN) as they lead to higher yields, making the country a more attractive place for investors. On the contrary, lower interest rates tend to weaken MXN.
Macroeconomic data releases are key to assess the state of the economy and can have an impact on the Mexican Peso (MXN) valuation. A strong Mexican economy, based on high economic growth, low unemployment and high confidence is good for MXN. Not only does it attract more foreign investment but it may encourage the Bank of Mexico (Banxico) to increase interest rates, particularly if this strength comes together with elevated inflation. However, if economic data is weak, MXN is likely to depreciate.
As an emerging-market currency, the Mexican Peso (MXN) tends to strive during risk-on periods, or when investors perceive that broader market risks are low and thus are eager to engage with investments that carry a higher risk. Conversely, MXN tends to weaken at times of market turbulence or economic uncertainty as investors tend to sell higher-risk assets and flee to the more-stable safe havens.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















