Mexican Peso depreciates on overall US Dollar strength on risk-aversion
- USD/MXN climbs 0.43% as US employment strength dampens hopes for imminent Fed rate reductions, boosting the Greenback.
- 10-year US Treasury yield hits a high of 4.801%, adding pressure on emerging market currencies like the Mexican Peso.
- Economic forecasts are bleak for Mexico with potential recession and credit rating concerns despite some positive industrial data.

The Mexican Peso prolongs its agony against the US Dollar, dropping for the fifth consecutive session on Monday amid a risk-off impulse following a robust US employment report that might deter the US Federal Reserve (Fed) from cutting interest rates. The USD/MXN trades at 20.80, up 0.43%.
Market participants remain risk-averse after last week’s Nonfarm Payrolls (NFP) report for December showed a jump in hiring. Consequently, the Greenback advanced as traders grew less optimistic that the Fed would lower interest rates anytime soon. Besides this, US Treasury yields remained elevated with the 10-year T-note reaching 4.801% for the first time since November 2023.
Mexico's economic docket remains absent, yet industrial production has improved in monthly and annual figures. However, the economy is not out of the woods yet. Former Deputy Finance Minister Alejandro Werner said in an article by El Economista that the Mexican economy would enter a recession this year and could lose its investment-grade status before 2027.
This week, Mexico's docket will feature Gross Fixed Investment and Retail Sales reports. In the US, key data releases include inflation figures on the producer and consumer sides, alongside Retail Sales and jobless claims for the week ending January 11.
Daily digest market movers: Mexican Peso drops as traders flee to safety
- The Mexican Peso weakened last Friday after December’s NFP said the US economy added over 256K employees to the workforce. Estimates were around 160K, and November's figures were revised to 212K from 227K.
- The Unemployment Rate slipped to 4.1%, and Average Hourly Earnings dropped below 4%.
- Although money markets expect the Fed to cut rates once, Wednesday's US inflation data will be crucial. Elevated readings would confirm investors' speculation that rates will be held through 2025. Otherwise, they could adjust their expectations.
- Last week, Banco de Mexico (Banxico) revealed December's meeting minutes. The minutes showed that inflation continues to trend lower, suggesting that the easing cycle might continue. Banxico's Governing board stated that "larger downward adjustments could be considered in some meetings."
- Mexico's central bank improved the inflation outlook due to the headline and core inflation progress. Officials acknowledged that services inflation decreased and expect CPI to converge to its 3% goal in Q3 2026.
- The Fed's latest Meeting Minutes showed that despite reducing rates, some policymakers supported keeping the fed funds rate unchanged as worries had grown that inflation risks were skewed to the upside.
- Consequently, they adopted a more gradual approach as Fed officials opened the door to slowing the pace of interest rate cuts.
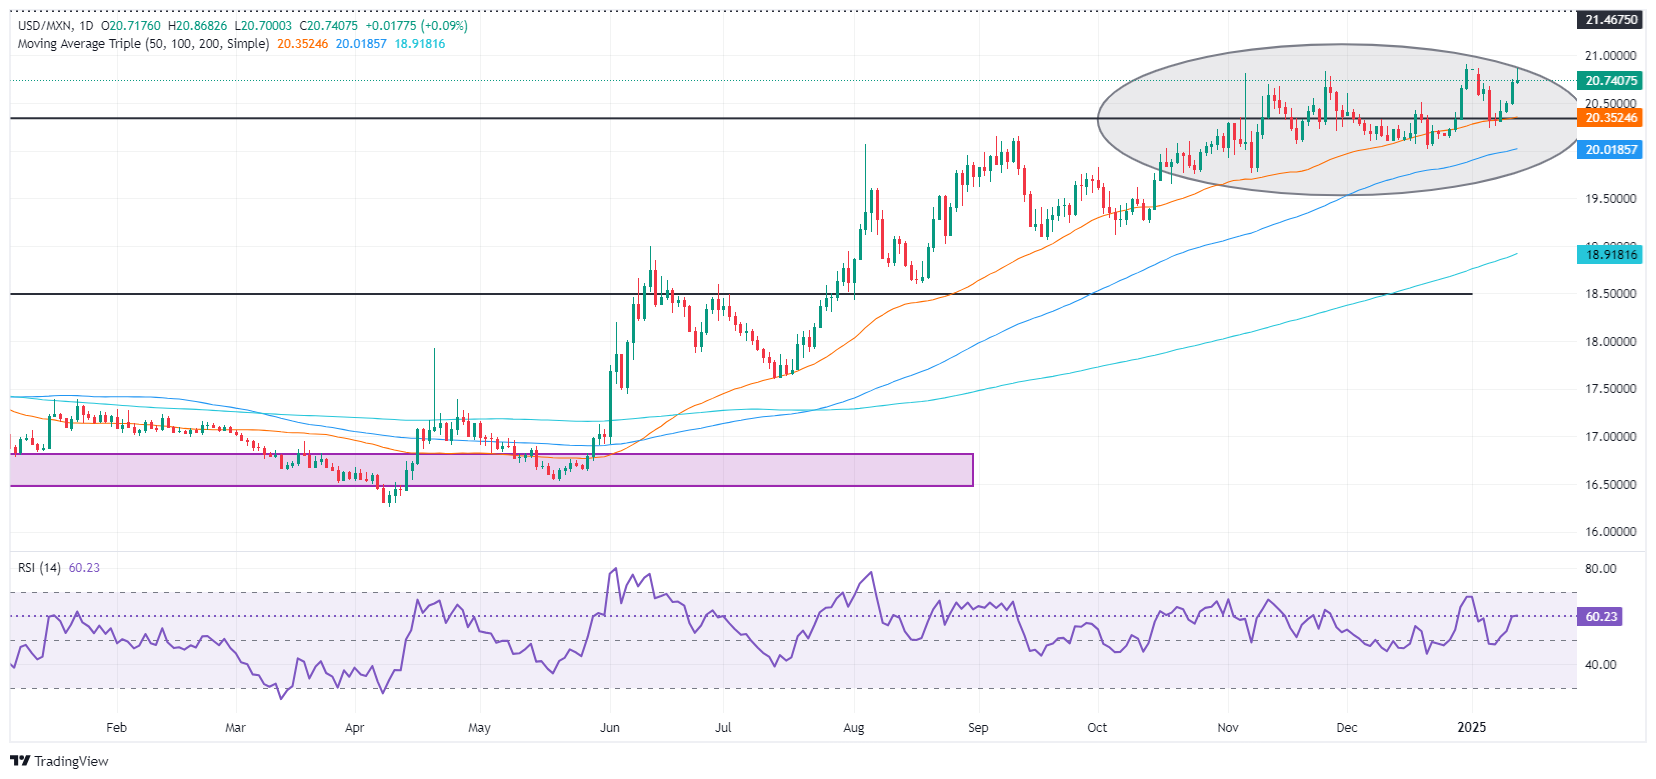
USD/MXN technical outlook: Mexican Peso plunges as USD/MXN rises above 20.75
The USD/MXN uptrend remains intact. Traders had turned bullish on the US Dollar to the detriment of the Peso. If the Peso remains bid, they could test the current year-to-date (YTD) peak of 20.90. If surpassed, the next stop would be the March 8, 2022 high of 21.46, ahead of 21.50 and the 22.00 psychological level.
Conversely, if USDMXN drops below 20.50, this will expose the 50-day Simple Moving Average (SMA) at 20.30. Once surpassed the next stop is the psychological 20.00 level, followed by the 100-day SMA at 19.96.
Mexican Peso FAQs
The Mexican Peso (MXN) is the most traded currency among its Latin American peers. Its value is broadly determined by the performance of the Mexican economy, the country’s central bank’s policy, the amount of foreign investment in the country and even the levels of remittances sent by Mexicans who live abroad, particularly in the United States. Geopolitical trends can also move MXN: for example, the process of nearshoring – or the decision by some firms to relocate manufacturing capacity and supply chains closer to their home countries – is also seen as a catalyst for the Mexican currency as the country is considered a key manufacturing hub in the American continent. Another catalyst for MXN is Oil prices as Mexico is a key exporter of the commodity.
The main objective of Mexico’s central bank, also known as Banxico, is to maintain inflation at low and stable levels (at or close to its target of 3%, the midpoint in a tolerance band of between 2% and 4%). To this end, the bank sets an appropriate level of interest rates. When inflation is too high, Banxico will attempt to tame it by raising interest rates, making it more expensive for households and businesses to borrow money, thus cooling demand and the overall economy. Higher interest rates are generally positive for the Mexican Peso (MXN) as they lead to higher yields, making the country a more attractive place for investors. On the contrary, lower interest rates tend to weaken MXN.
Macroeconomic data releases are key to assess the state of the economy and can have an impact on the Mexican Peso (MXN) valuation. A strong Mexican economy, based on high economic growth, low unemployment and high confidence is good for MXN. Not only does it attract more foreign investment but it may encourage the Bank of Mexico (Banxico) to increase interest rates, particularly if this strength comes together with elevated inflation. However, if economic data is weak, MXN is likely to depreciate.
As an emerging-market currency, the Mexican Peso (MXN) tends to strive during risk-on periods, or when investors perceive that broader market risks are low and thus are eager to engage with investments that carry a higher risk. Conversely, MXN tends to weaken at times of market turbulence or economic uncertainty as investors tend to sell higher-risk assets and flee to the more-stable safe havens.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















