Mexican Peso starts to weaken against USD due to Trump factor

Most recent article: Mexican Peso is flat against US Dollar following mixed US NFP data
- The Mexican Peso reverses earlier gains against the US Dollar and weakens against European counterparts.
- Poor US data had initially weighed on USD, however, the increasing liklihood of a Trump presidency leads to a rebound.
- In Europe, political risk eases, taking pressure off the Euro and the Pound.
The Mexican Peso (MXN) reverses earlier gains and trades lower in its most traded pairs on Friday, with mixed results in the US Nonfarm Payrolls report confusing markets and a "Trump put" pushing down US Treasuries but keeping the US Dollar bid – seemingly against the odds. In Europe, the Peso’s gains are more muted due to reduced political risk as elections indicate moderates holding onto power despite the rise of the far-right.
MXN is supported by comments from the Deputy Governor of the Bank of Mexico (Banxico), Jonathan Heath, who said he was skeptical about interest rates falling in Mexico in the near term, comparing his stance to that of Federal Reserve (Fed) Chairman Jerome Powell.
At the time of writing, one US Dollar (USD) buys 18.17 Mexican Pesos, EUR/MXN trades at 19.65, and GBP/MXN at 23.23.
Mexican Peso reverses early gains against USD
The Mexican Peso rose against the US Dollar during the European session on Friday as traders digested the recent run of weak US economic data and its implications for interest rates going forward, a key driver of FX flows.
Weak jobs data released earlier in the week showed Initial Jobless Claims rising and Continuing Claims hitting 1.858 million in the week ending June 22, its highest since November 2021.
The hitherto buoyant services sector showed signs of contraction in June too, after ISM Services Purchasing Managers Index (PMI) data came out at 48.8, falling below the 50 level that separates growth from contraction and its lowest level since 2020.
This has weakened USD, as falling inflation expectations make the Fed more inclined to cut interest rates, and lower interest rates are negative for the Dollar as they attract less foreign capital inflows.
NFP temporarily weakened USD before a bounce back
The release of the US Nonfarm Payrolls (NFP) report on Friday further temporarily weakened the US Dollar after the Unemployment Rate showed a rise to 4.1% from 4.0% previously. Economists had not expected this and it indicates a cooling labor market that could make it even more likely the Fed will cut interest rates in order to stimulate hiring.
However, overall the NFP report was mixed. The headline Nonfarm Payrolls result showed 206K new employees joined the workforce in June beating consensus estimates of 190K. Average Hourly Earnings, meanwhile, a metric that can influence inflationary pressures and the Fed's policy on interest rates remained unchanged on a monhtly basis, showing 0.3% growth as expected. On a year-over-year basis wage inflation cooled to 3.9% from 4.1% previously as expected, according to data from the US Bureau of Labor Statistics.
"Trump put" helps US yields and USD recover
The Mexican Peso was unable to sustain its gains against the US Dollar during the US session, however, as US traders returned to their desks after the July 4 holiday, with many contemplating a "Trump put" weighing on bond markets due to his reputation for lowering taxes and borrowing more to cover the shortfall.
Former President Donald Trump is viewed as having bested his rival President Joe Biden in the recent televised debate in Atlanta when Biden seemed confused at times and struggled to provide coherent answers to some of the questions. Critics put this down to his advanced age and argue he is unfit for office. This, and a Supreme Court ruling giving Trump partial immunity from charges he incited the storming of Capitol Hill after he election loss in 2020, having increassed bets Trump could win the elections in November.
Some economists are arguing a Trump presidency will lead to lower taxes but still-high spending, pushing the US deficit and rising public debt even higher.
"Yields have risen sharply after President Joe Biden's stumbling performance against Republican rival Donald Trump in the first presidential debate last month, which increased speculation about a second Trump win when voters go to the polls on Nov. 5. The benchmark 10-year yield rose about six points to 4.34% following the debate," says Davide Barbuscia, US Investment Correspondent for Reuters.
"Some investors are betting on higher inflation under Trump because of trade and economic policies such as higher tariffs on imports, and profligate government spending along with lower tax revenues, which would boost fiscal deficits and U.S. debt levels," he adds.
Mexican Peso’s muted versus European counterparts
The Mexican Peso is edging lower against the Euro (EUR) and the Pound Sterling (GBP) due to easing political risk. It now seems likely that the far-right French National Rally (RN) party will not get enough seats for a majority in the second round of French elections on Sunday, which, in turn, supports the Euro.
Across the channel, meanwhile, the Pound Sterling (GBP) has been lifted slightly after the Labour Party’s landslide victory in Thursday’s general election. Some analysts have cited a more stable political climate, as well as stronger prospects for growth, as key drivers for expecting some post-election strengthening in GBP.
Technical Analysis: USD/MXN continues sliding to key low
USD/MXN continues edging lower towards the key June 24 swing low at 17.87. It is possible the pair is entering a sideways trend, although it is still a little too early to be sure.
USD/MXN 4-hour Chart
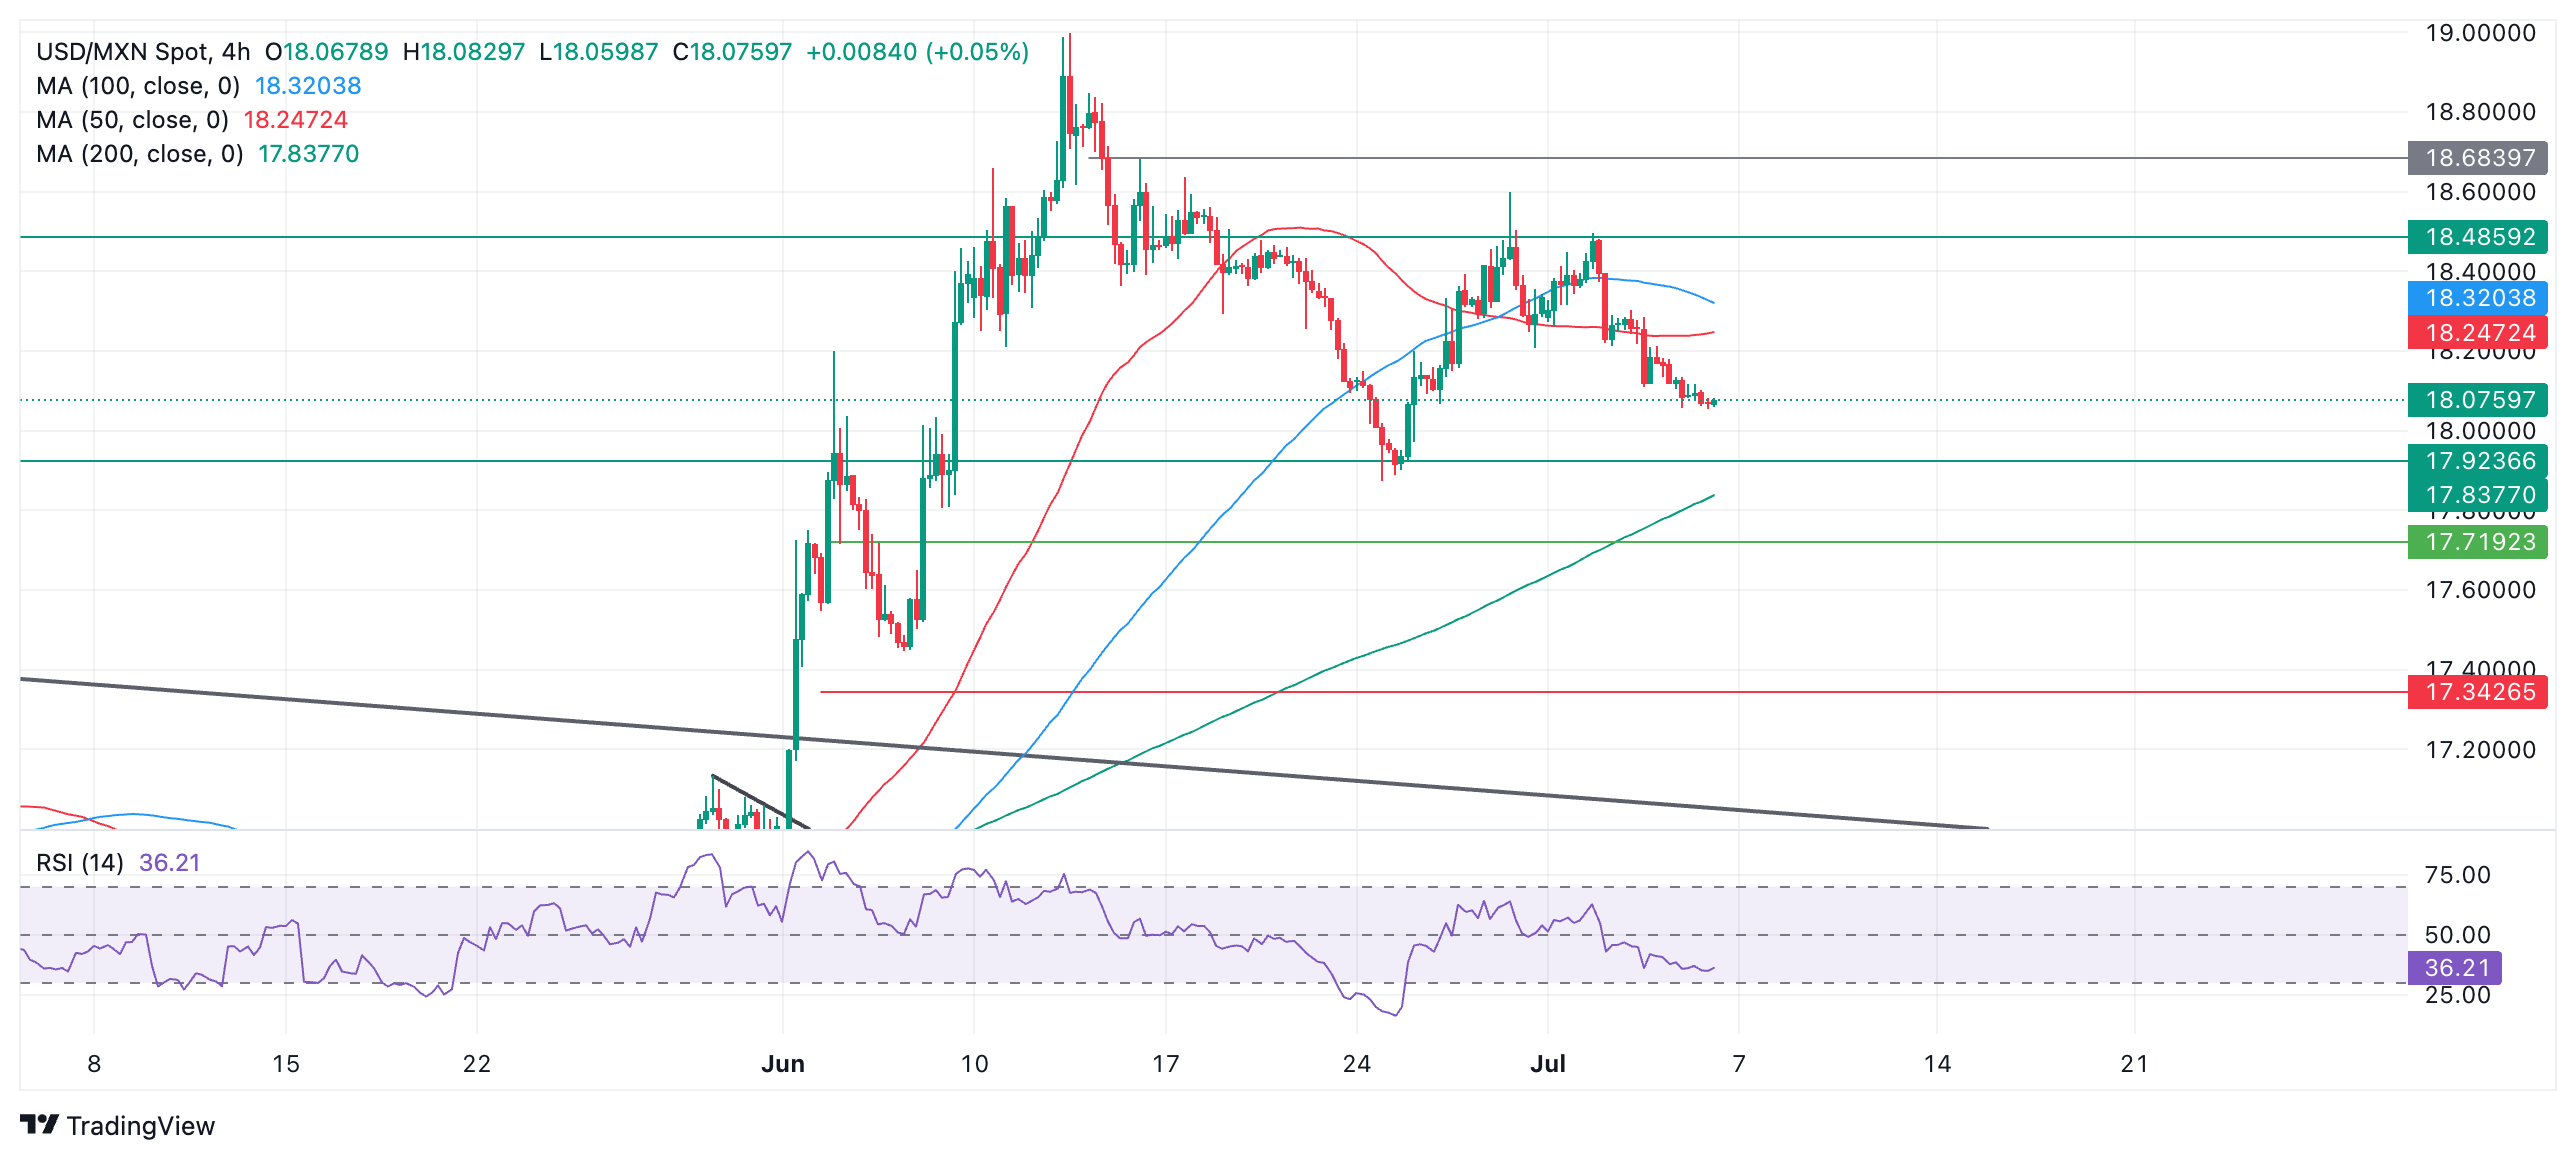
There is a chance that once the June 24 low is achieved, the pair will begin to consolidate. If it begins a leg higher, it could be a sign that the pair is entering a sideways trend. Alternatively, a decisive break below 17.87 would likely suggest a new downtrend, with the next target lying at 17.50 (50-day Simple Moving Average).
A rally back above 18.59, however, would suggest a continuation up to 18.68 (June 14 high), followed by 19.00 (June 12 high). A break above 19.00 would provide strong confirmation of a resumption of the short-and-intermediate term uptrends.
The direction of the long-term trend remains in doubt.
Banxico FAQs
The Bank of Mexico, also known as Banxico, is the country’s central bank. Its mission is to preserve the value of Mexico’s currency, the Mexican Peso (MXN), and to set the monetary policy. To this end, its main objective is to maintain low and stable inflation within target levels – at or close to its target of 3%, the midpoint in a tolerance band of between 2% and 4%.
The main tool of the Banxico to guide monetary policy is by setting interest rates. When inflation is above target, the bank will attempt to tame it by raising rates, making it more expensive for households and businesses to borrow money and thus cooling the economy. Higher interest rates are generally positive for the Mexican Peso (MXN) as they lead to higher yields, making the country a more attractive place for investors. On the contrary, lower interest rates tend to weaken MXN. The rate differential with the USD, or how the Banxico is expected to set interest rates compared with the US Federal Reserve (Fed), is a key factor.
Banxico meets eight times a year, and its monetary policy is greatly influenced by decisions of the US Federal Reserve (Fed). Therefore, the central bank’s decision-making committee usually gathers a week after the Fed. In doing so, Banxico reacts and sometimes anticipates monetary policy measures set by the Federal Reserve. For example, after the Covid-19 pandemic, before the Fed raised rates, Banxico did it first in an attempt to diminish the chances of a substantial depreciation of the Mexican Peso (MXN) and to prevent capital outflows that could destabilize the country.
Author

Joaquin Monfort
FXStreet
Joaquin Monfort is a financial writer and analyst with over 10 years experience writing about financial markets and alt data. He holds a degree in Anthropology from London University and a Diploma in Technical analysis.

















