Gold price ease: Risk-off sentiment and declining US yields take toll
- Gold drops 0.90% as commodities face widespread pressure.
- US Treasury yields fall seven basis points, but the Greenback gains marginally, with the DXY up 0.04% to 104.08.
- US JOLTS data hit three-year low, showing economic slowdown alongside below-estimate Durable Goods Orders.

Gold prices retreat some 0.90% in the mid-North American session on Tuesday, amid a risk-off impulse and despite falling US Treasury bond yields. The latest tranche of US economic data shows the economy is slowing down, warranting lower interest rates. Despite that, the XAU/USD trades with losses and exchanges hands at $2,328.
The golden metal has fallen below $2,350 a troy ounce as commodities plunges across the board. Oil prices were under heavy pressure earlier amidst fears that the global economy might grow at a slower pace, which could dent demand for crude.
US Treasury yields, which usually correlate inversely to Gold prices, were also down seven basis points by the US 10-year Treasury yield.
In opposition, the Greenback is trading with marginal gains of 0.04% in the US Dollar Index (DXY). The DXY tracks the Greenback against a basket of six currencies and is up at 104.08.
Data-wise, the US economic docket featured the release of April’s JOLTS data and Durable Goods Orders. The reports showcased that the economy remains resilient yet weak amid higher borrowing costs set by the US Federal Reserve (Fed).
Following the data release, the December 2024 fed funds rate futures contract showed that most traders expect at least 36 basis points of rate cuts via the Chicago Board of Trade (CBOT).
Consequently, US Treasury bond yields dropped, and the Greenback extended its losses to three straight days.
Daily digest market movers: Gold price falls as US Treasury yields retreat
- Tuesday’s US economic docket featured the US JOLTs Job Openings report, which decreased from 8.355 million to 8.059 million in April, falling short of the estimated 8.34 million.
- US Durable Goods Orders rose by 0.6% MoM in April, which is below both the estimates and the previous reading of 0.7%.
- Last week, the US Core Personal Consumption Expenditure Price Index (PCE), the Fed’s preferred inflation gauge, stabilized, boosting hopes for potential rate cuts.
- Meanwhile, business activity showed mixed results, with the S&P Global Manufacturing PMI expanding, while the Institute for Supply Management (ISM) Manufacturing PMI contracted for the second consecutive month.
- Traders are currently pricing about a 54.9% chance of a rate cut, according to the CME FedWatch Tool.
- The US economic docket during the week will feature ADP Employment Change ahead of Friday’s Nonfarm Payrolls.
Technical analysis: Gold price slips below $2,350
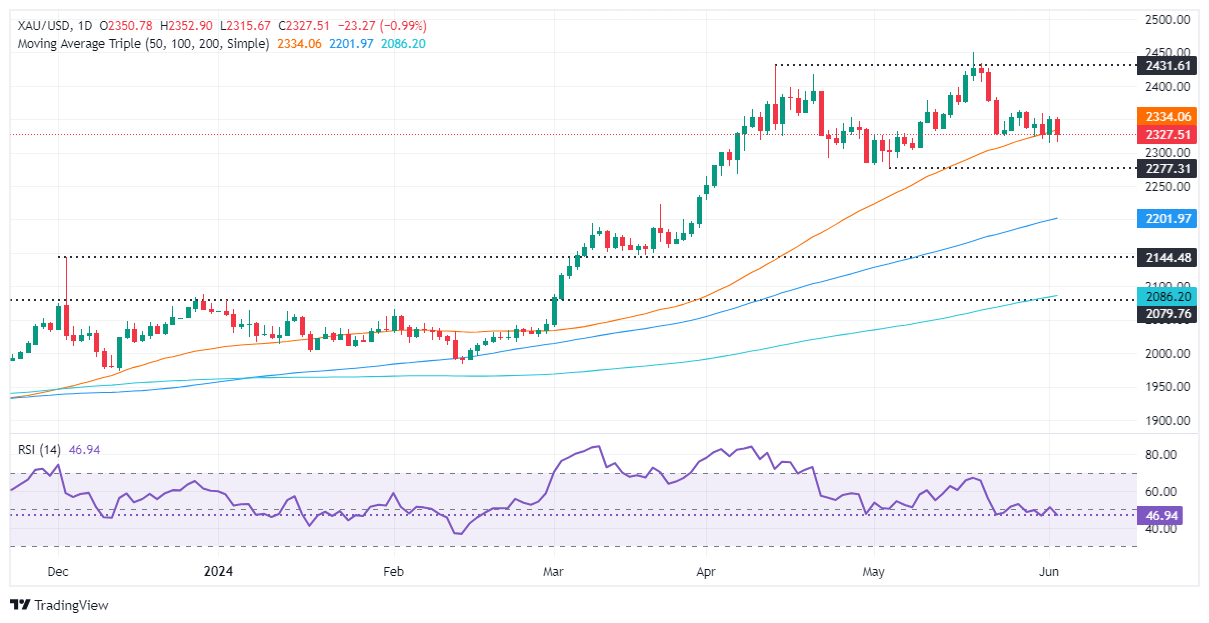
Gold’s rally remains in place, though the spot prices have fallen below the 50-day Simple Moving Average (SMA) of $2,334. Price action and the momentum shifting in favor of the sellers could pave the way for a pullback. The Relative Strength Index (RSI) turned bearish, below the 50 midline, opening the door for further Gold losses.
Once the XAU/USD fell below the 50-day Simple Moving Average (SMA) at $2,334, that could pave the way to challenge the May 8 low of $2,303, followed by the May 3 cycle low of $2,277.
Further gains lie ahead if XAU/USD buyers reclaim $2,350. Up next would be the $2,400 level, followed by the year-to-date high of $2,450 and, subsequently, the $2,500 mark.
Gold FAQs
Gold has played a key role in human’s history as it has been widely used as a store of value and medium of exchange. Currently, apart from its shine and usage for jewelry, the precious metal is widely seen as a safe-haven asset, meaning that it is considered a good investment during turbulent times. Gold is also widely seen as a hedge against inflation and against depreciating currencies as it doesn’t rely on any specific issuer or government.
Central banks are the biggest Gold holders. In their aim to support their currencies in turbulent times, central banks tend to diversify their reserves and buy Gold to improve the perceived strength of the economy and the currency. High Gold reserves can be a source of trust for a country’s solvency. Central banks added 1,136 tonnes of Gold worth around $70 billion to their reserves in 2022, according to data from the World Gold Council. This is the highest yearly purchase since records began. Central banks from emerging economies such as China, India and Turkey are quickly increasing their Gold reserves.
Gold has an inverse correlation with the US Dollar and US Treasuries, which are both major reserve and safe-haven assets. When the Dollar depreciates, Gold tends to rise, enabling investors and central banks to diversify their assets in turbulent times. Gold is also inversely correlated with risk assets. A rally in the stock market tends to weaken Gold price, while sell-offs in riskier markets tend to favor the precious metal.
The price can move due to a wide range of factors. Geopolitical instability or fears of a deep recession can quickly make Gold price escalate due to its safe-haven status. As a yield-less asset, Gold tends to rise with lower interest rates, while higher cost of money usually weighs down on the yellow metal. Still, most moves depend on how the US Dollar (USD) behaves as the asset is priced in dollars (XAU/USD). A strong Dollar tends to keep the price of Gold controlled, whereas a weaker Dollar is likely to push Gold prices up.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















