What gold is telling us

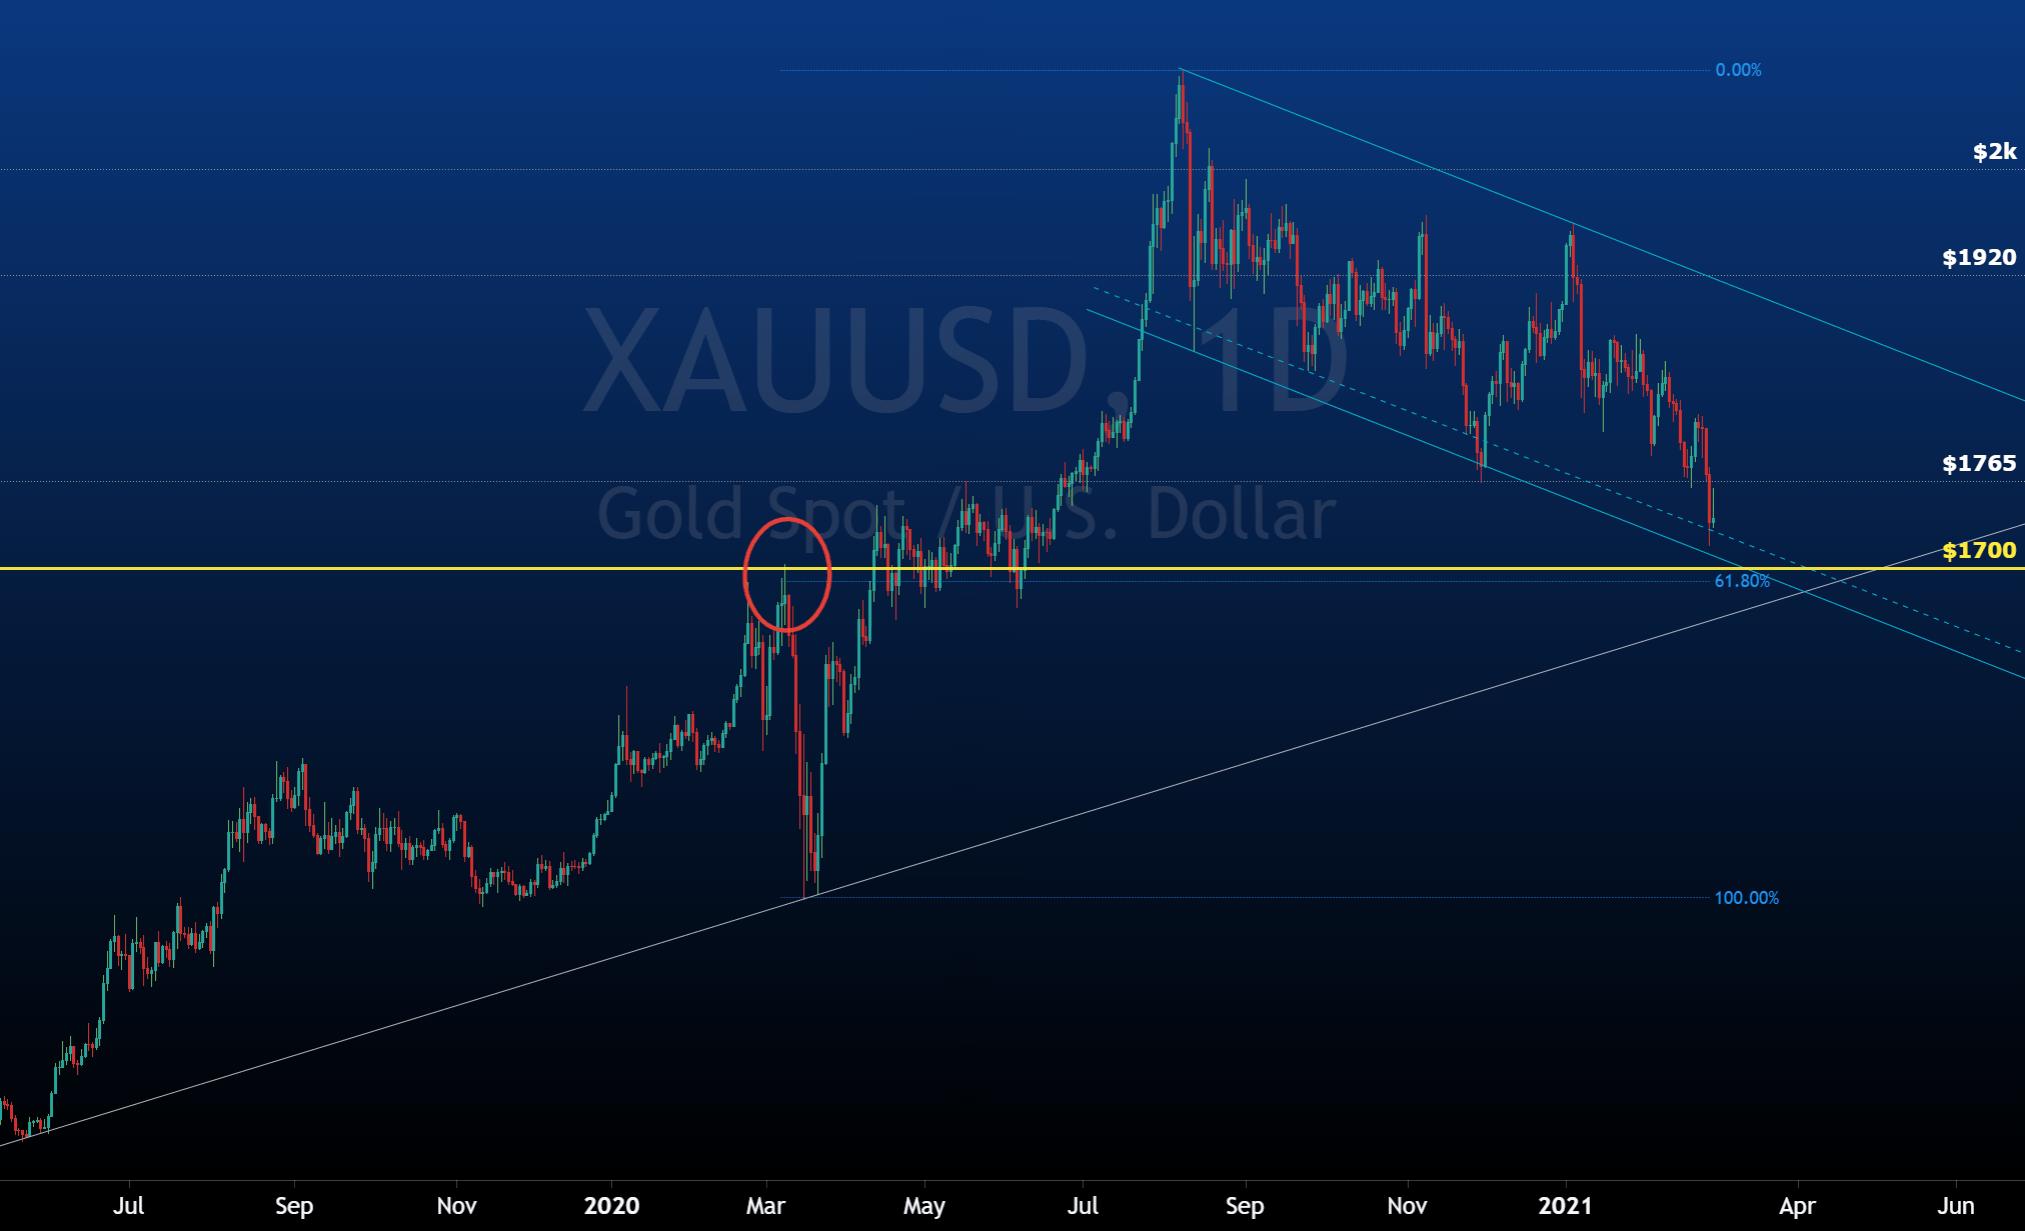
Recall the liquidity event observed in March of 2020. Although gold ended up dropping less than the broad markets, it was not immune under stressed liquidity conditions. Once market concerns subsided, gold rebounded sharply along with other hard assets like silver and most commodities.
This tells us that investors sold their gold because they had to, not because they wanted to.
Recently, gold has fallen below its key support level of $1765 (Q4 2020 lows). As seen below, gold is nearing pre-pandemic levels in the $1700 range (yellow).
More leverage, greater unwinding
This is exactly what liquidity issues are made of - forced selling of highly liquid assets to bolster cash buffers and even meet margin calls. Although markets are not in absolute turmoil as of now, gold is sending a message that liquidity concerns are back.
It’s important to remember the financial system is more leveraged today than ever before. Margin debt is at all-time highs, which amplifies liquidity concerns when they arise. Based on this backdrop of tremendous leverage in financial assets, we can expect an exaggeration of both market highs and lows.
Why liquidity concerns now?
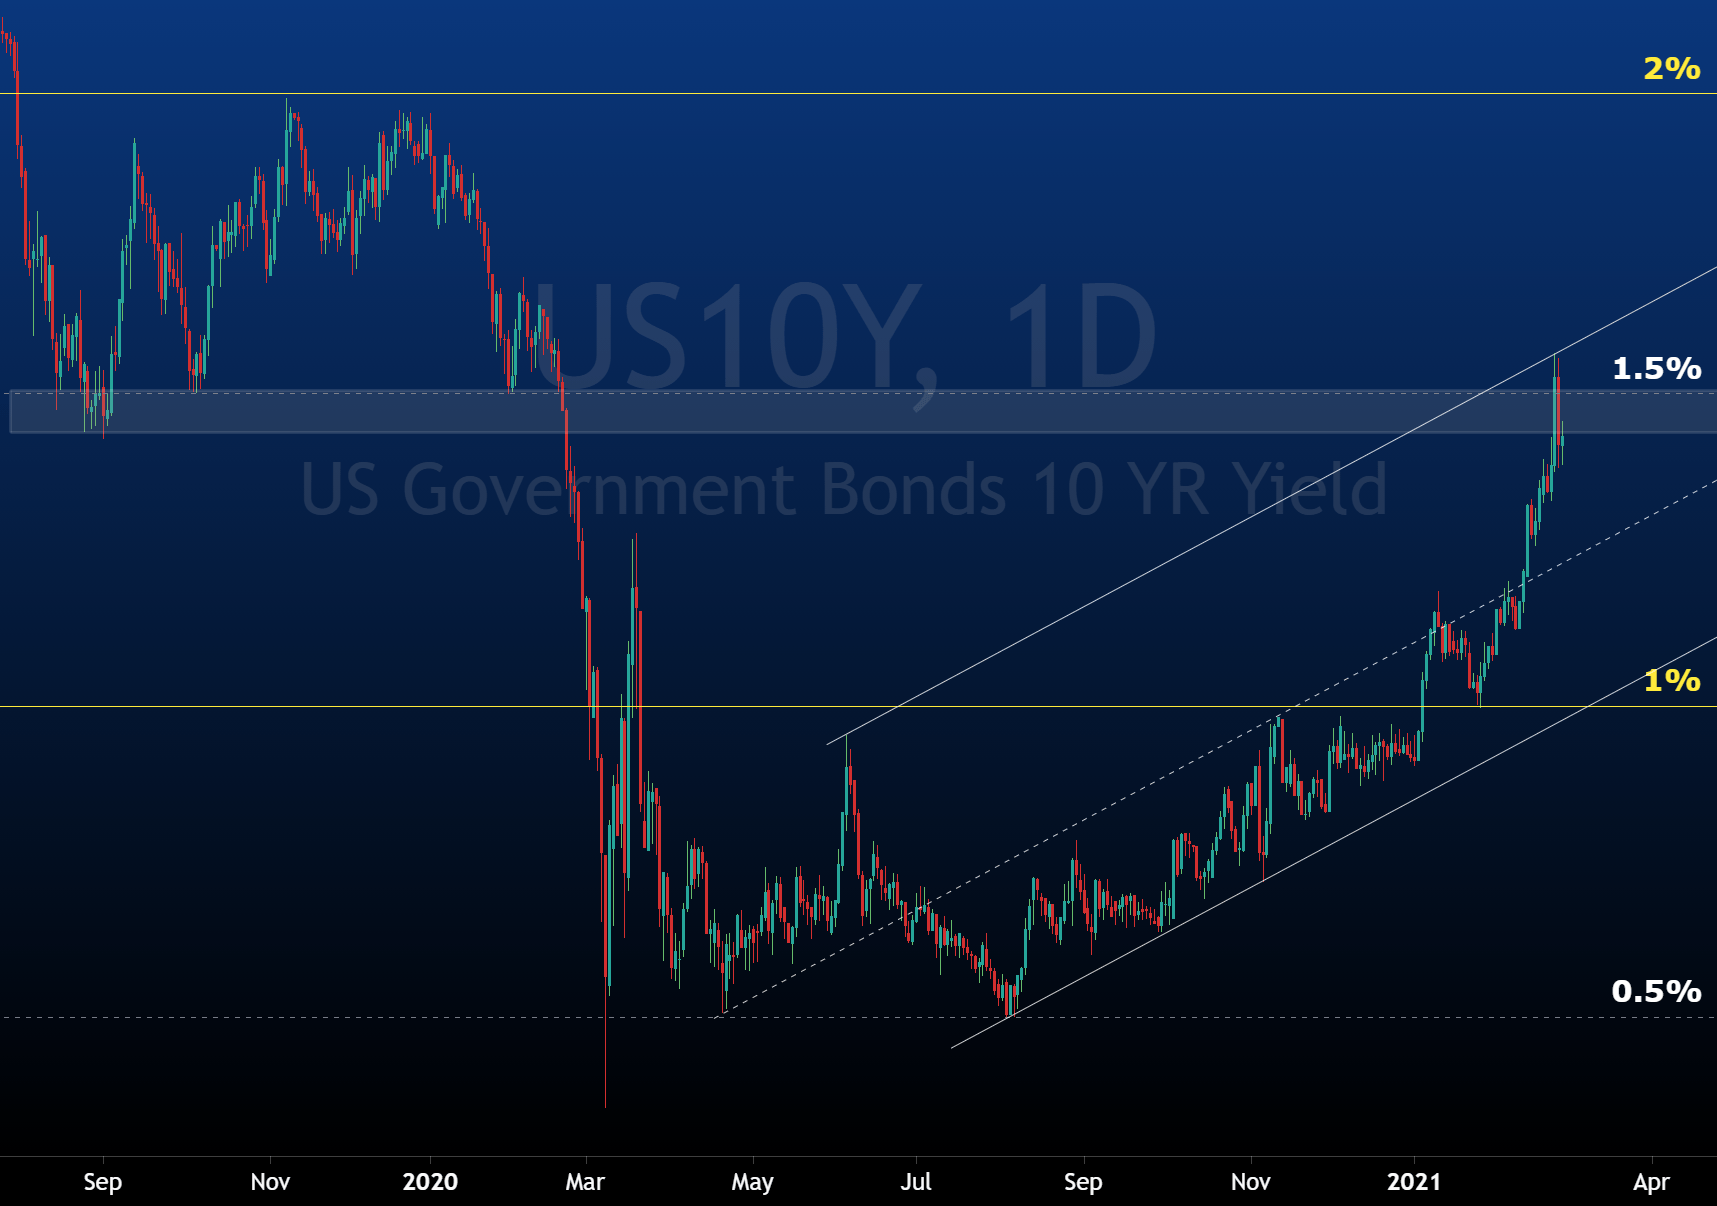
US Treasury yields have been rising sharply as of late, due to higher inflation expectations and the presumption that government spending will remain high. It was only a matter of time before sharply rising yields created liquidity concerns given today’s highly leveraged global economic system.
Therefore, it will be crucial for investors to keep a close eye on the 10-year yield and gold. A great buying opportunity is present in the precious metals space when we consider that central banks will not allow yields to rise indefinitely. Physical precious metals and mining shares remain at bargain prices, given the macroeconomic backdrop.
The 10-year yield is sitting around 1.5% in the midst of this ongoing bond market selloff. Note in the chart below, how the 1.5% range marks a test of key previous structure:
The Fed will be under pressure to act
It’s possible the 10-year yield has naturally peaked already, but we cannot be sure. If not, the Fed will be under pressure in its next meeting to intervene. Many economists, including Danielle Dimartino Booth of Quill Intelligence, are suggesting that the Fed may be forced to shift their QE purchases toward the long end of the yield curve to halt the rise in Treasury yields.
Remember, the Fed and other global central banks need to keep real interest rates negative or else the cost of refinancing government and private sector debts will be too great a burden. Their goal is to inflate away the government’s debt - requiring inflation levels to remain higher than long-term rates. Without negative real rates, it’s impossible to keep the financial economy in a constant expansion mode.
Currently, the Fed’s QE program is focused on buying the short-end of the yield curve. If indeed the FOMC decides to purchase longer duration securities, it will be de-facto implementing “yield curve controls.” This would bring the US financial system one step closer to a full “Japanification.”
Opportunity
Whether or not the top of the 10-year yield comes naturally or takes the FOMC action, the buying opportunity in precious metals is not one to be overlooked.
As central banks drive real rates into negative territory, gold’s case as an inflation hedge and safe-haven insurance asset is only strengthened in the long run.
Precious metals investors should be thankful for the opportunity to accumulate at prices equivalent to pre-pandemic levels - before the massive government interventions of 2020 had even taken place.
Warren Buffett has said this many times - be fearful when others are greedy, greedy when others are fearful. What better time could there be to accumulate precious metals assets than when others are under forced selling pressure!
Author

Miles Ruttan
Bytown Capital
Miles' focus at the firm is to oversee our macro analysis, with the emphasis being placed on global credit and liquidity flows.

















