|

GBP/USD Forecast: Pressuring weekly lows and at risk of falling

GBP/USD Current price: 1.3737

  • The UK Markit Construction PMI jumped to 61.7 in March.
  • Concerns related to the AstraZeneca covid vaccine weigh on the pound.
  • GBP/USD remains under selling pressure and is poised to extend its slump.
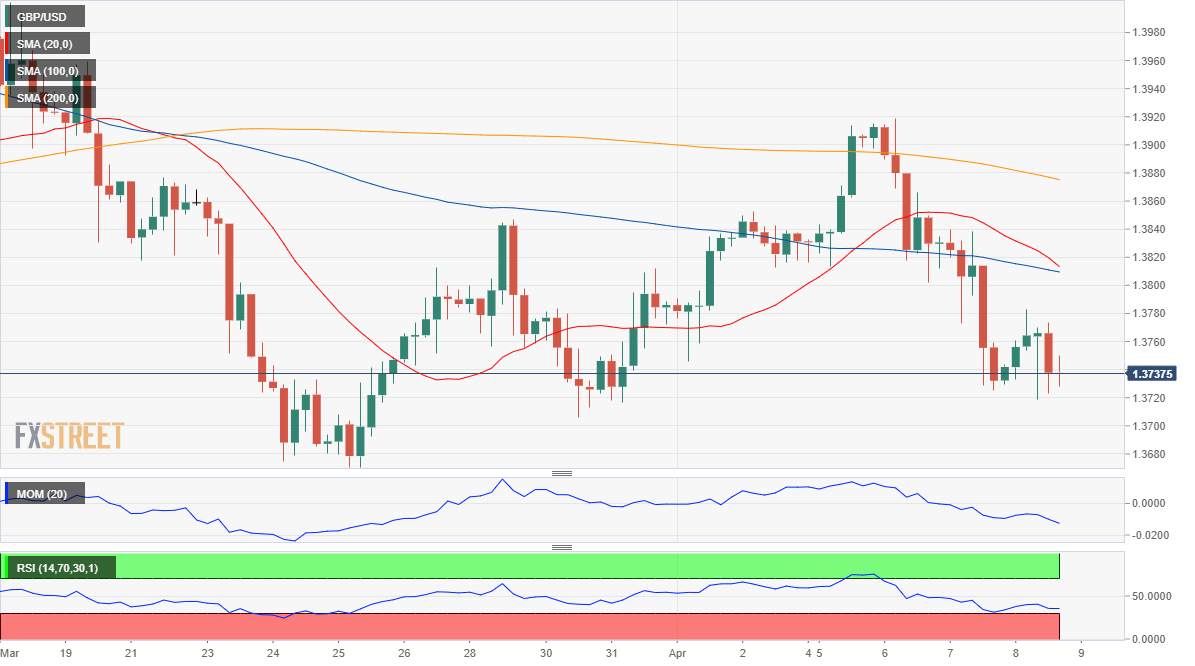
The British Pound remained among the worst performers against the greenback, as the GBP/USD pair extended its weekly decline to 1.3718, ending the day around 1.3740. UK macroeconomic data was quite encouraging, as the March Markit Construction PMI hit 61.7, improving from 53.3 and largely surpassing the expected 54.6. Concerns surrounding the AstraZeneca vaccine keep weighing on sterling, as the EMA found a “rare link” between the jab and blood clots. Nevertheless, the UK  has given at least one dose of a coronavirus vaccine to roughly 50% of the population, which brought sharply down the number of daily deaths and contagions.

The UK will publish on Friday Halifax House Prices for the three months to March, while the BOE will publish its Quarterly Bulletin for the first quarter of the year.

GBP/USD short-term technical outlook

The GBP/USD pair is still at risk of falling according to intraday technical readings. The 4-hour chart shows that it keeps developing below all of its moving averages, with the 20 SMA accelerating south and about to cross below the 100 SMA, both around the 1.3815 level. The Momentum indicator bounced from daily lows but lost strength upward within negative levels, while the RSI indicator is stable around 38, indicating a lack of buying interest. A steeper decline is on the table on a break below 1.3720, the immediate support level.

 Support levels: 1.3720 1.3680 1.3640

Resistance levels: 1.3770 1.3810 1.3865  

View Live Chart for the GBP/USD

Author

Valeria Bednarik

Valeria Bednarik was born and lives in Buenos Aires, Argentina. Her passion for math and numbers pushed her into studying economics in her younger years.


More from Valeria Bednarik
Share:

Editor's Picks

AUD/USD flirts with 0.7000, lowest since early August amid bullish USD

AUD/USD hits a fresh low since early August during the Asian session on Friday and looks vulnerable near 0.7000 after breaking below the 200-day SMA overnight. Against the backdrop of the hawkish Fed, a two-day rally in oil prices revives inflation fears and continues to push US bond yields to multi-year highs. Adding to this, geopolitical risks lift the US Dollar to a two-month high, overshadowing RBA rate hike bets and weighing on the pair.

USD/JPY pulls back from three-week high after failing near 159.00

USD/JPY edges lower during the Asian session on Friday, stalling its recent strong move to a three-week high of 159.00 as Japanese Yen bears turn cautious amid intervention fears. Meanwhile, the US Dollar retains a strong bullish undertone as the Fed's hawkish outlook and oil-driven inflation fears continue to push US bond yields to multi-year peaks. Furthermore, the BoJ's dovish rate hike last week might cap JPY and support spot prices.

Gold treads water below $4,300

Gold grabs some buying attention and advances marginally at the end of the week, partially retracing the weekly decline, although it is still navigating below the key $4,300 mark per troy ounce. The fresh selling bias on the Greenback and the modest decline in US Treasury yields appear to support the humble advance in the precious metal.

Crypto Today: Bitcoin and Ethereum edge lower, XRP extends recovery as macro headwinds weigh

The broader cryptocurrency market is consolidating on Friday, with Bitcoin paring losses slightly above $84,000. Ethereum declines in tandem with BTC. Ripple (XRP), meanwhile, paints a different picture.


Fed vs BoJ: Both hiked. The market only believes one of them – and the chart shows which
The Federal Reserve (Fed) and the Bank of Japan (BoJ) have just done something remarkably similar. Both central banks raised interest rates by 25 basis points (bps) last week, both are confronting inflation risks, and both signal that future decisions will depend on incoming economic data.
Fed vs BoJ: Both hiked. The market only believes one of them – and the chart shows which

The Fed and the BoJ have just done something remarkably similar. Both central banks raised interest rates by 25 bps last week, both are confronting inflation risks, and both signal that future decisions will depend on incoming economic data.













