GBP/USD Forecast: Pound Sterling looks to push higher after UK inflation data
- GBP/USD trades slightly above 1.2700 in the European morning on Wednesday.
- October inflation figures from the UK came in above market expectations.
- The technical outlook points to a bullish tilt in the near term.

GBP/USD trades in positive territory slightly above 1.2700 early Wednesday as markets assess latest inflation readings from the UK. The pair's near-term technical picture highlights a buildup of recovery momentum.
British Pound PRICE Today
The table below shows the percentage change of British Pound (GBP) against listed major currencies today. British Pound was the strongest against the Japanese Yen.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 0.12% | -0.20% | 0.59% | 0.00% | 0.16% | 0.26% | 0.24% | |
| EUR | -0.12% | -0.32% | 0.48% | -0.12% | 0.03% | 0.13% | 0.11% | |
| GBP | 0.20% | 0.32% | 0.77% | 0.20% | 0.35% | 0.45% | 0.44% | |
| JPY | -0.59% | -0.48% | -0.77% | -0.60% | -0.45% | -0.36% | -0.37% | |
| CAD | -0.00% | 0.12% | -0.20% | 0.60% | 0.16% | 0.26% | 0.24% | |
| AUD | -0.16% | -0.03% | -0.35% | 0.45% | -0.16% | 0.10% | 0.08% | |
| NZD | -0.26% | -0.13% | -0.45% | 0.36% | -0.26% | -0.10% | -0.02% | |
| CHF | -0.24% | -0.11% | -0.44% | 0.37% | -0.24% | -0.08% | 0.02% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the British Pound from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent GBP (base)/USD (quote).
The UK's Office for National Statistics reported that annual inflation in the UK, as measured by the change in the Consumer Price Index (CPI), climbed to 2.3% in October from 1.7% in September, surpassing the market expectation of 2.2%. Additionally, the Core CPI, which excludes volatile food and energy prices, rose 3.3% in the same period, up from 3.2% in September. On a monthly basis, the CPI increased 0.6% after staying unchanged in September.
According to Reuters, UK rate futures point to 59 basis points (bps) of Bank of England (BoE) rate cuts by the end of 2025, vs 64 bps before stronger-than-forecast UK inflation data.
In the second half of the day, BoE Deputy Governor Sarah Breeden and Deputy Governor Dave Ramsden will be delivering speeches. While testifying before the UK Treasury Select Committee on Tuesday, BoE Governor Andrew Bailey noted that a gradual approach to removing monetary policy restraint will help them observe risks to the inflation outlook. In case BoE officials adopt a cautious tone regarding further policy easing, citing latest inflation readings, GBP/USD could continue to stretch higher.
The US economic calendar will not offer any high-impact macroeconomic data releases on Wednesday. Meanwhile, investors will keep a close eye on headlines surrounding the Russia-Ukraine conflict. A further escalation of geopolitical tensions could help the US Dollar (USD) stay resilient against its rivals and limit GBP/USD's upside.
GBP/USD Technical Analysis
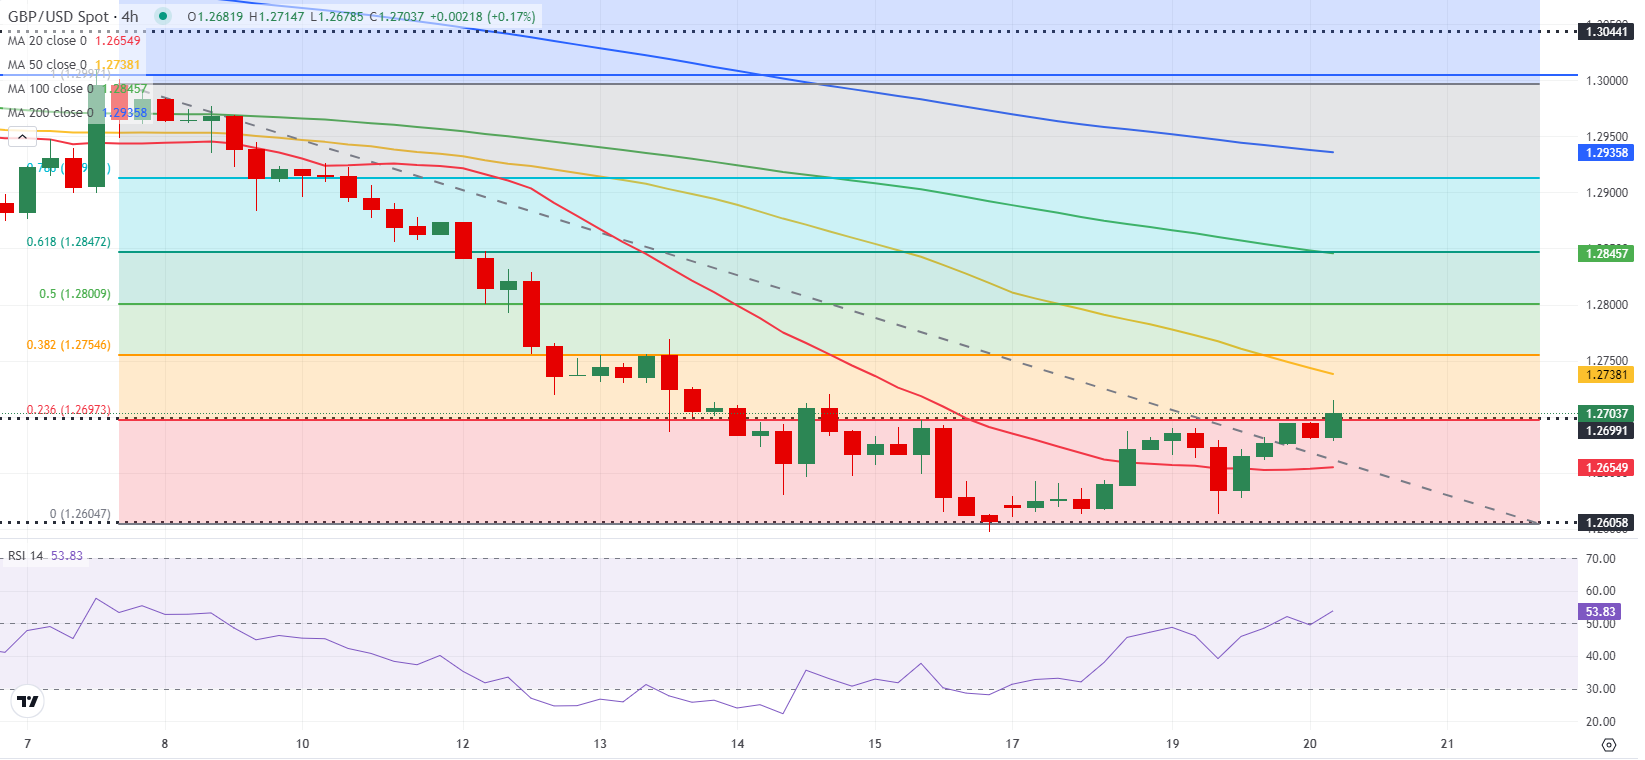
The Relative Strength Index (RSI) indicator on the 4-hour chart climbed above 50 early Wednesday, highlighting an increasing buyer interest. GBP/USD was last seen trading slightly above 1.2700, where the Fibonacci 23.6% retracement level of the latest downtrend is located. In case the pair confirms this level as support, it could face next resistance at 1.2740-1.2750 (50-period Simple Moving Average (SMA), Fibonacci 38.2% retracement) before 1.2800 (Fibonacci 50% retracement).
If GBP/USD fails to stabilize above 1.2700 and retreats below this level, the 20-period SMA at 1.2650 could be seen as next support ahead of 1.2600 (static level).
Inflation FAQs
Inflation measures the rise in the price of a representative basket of goods and services. Headline inflation is usually expressed as a percentage change on a month-on-month (MoM) and year-on-year (YoY) basis. Core inflation excludes more volatile elements such as food and fuel which can fluctuate because of geopolitical and seasonal factors. Core inflation is the figure economists focus on and is the level targeted by central banks, which are mandated to keep inflation at a manageable level, usually around 2%.
The Consumer Price Index (CPI) measures the change in prices of a basket of goods and services over a period of time. It is usually expressed as a percentage change on a month-on-month (MoM) and year-on-year (YoY) basis. Core CPI is the figure targeted by central banks as it excludes volatile food and fuel inputs. When Core CPI rises above 2% it usually results in higher interest rates and vice versa when it falls below 2%. Since higher interest rates are positive for a currency, higher inflation usually results in a stronger currency. The opposite is true when inflation falls.
Although it may seem counter-intuitive, high inflation in a country pushes up the value of its currency and vice versa for lower inflation. This is because the central bank will normally raise interest rates to combat the higher inflation, which attract more global capital inflows from investors looking for a lucrative place to park their money.
Formerly, Gold was the asset investors turned to in times of high inflation because it preserved its value, and whilst investors will often still buy Gold for its safe-haven properties in times of extreme market turmoil, this is not the case most of the time. This is because when inflation is high, central banks will put up interest rates to combat it. Higher interest rates are negative for Gold because they increase the opportunity-cost of holding Gold vis-a-vis an interest-bearing asset or placing the money in a cash deposit account. On the flipside, lower inflation tends to be positive for Gold as it brings interest rates down, making the bright metal a more viable investment alternative.
Author

Eren Sengezer
FXStreet
As an economist at heart, Eren Sengezer specializes in the assessment of the short-term and long-term impacts of macroeconomic data, central bank policies and political developments on financial assets.

















