GBP/USD Forecast: Pound Sterling could stretch lower in case 1.3250 support fails
- GBP/USD recovers toward 1.3300 following Tuesday's sharp drop.
- The technical outlook remains bearish in the near term.
- ADP Employment Change in the US is forecast to arrive at 120,000 in September.

GBP/USD turned south on Tuesday and lost nearly 0.7% on a daily basis. The pair edges higher toward 1.3300 in the European session on Wednesday but the technical outlook is yet to highlight a buildup of recovery momentum.
British Pound PRICE This week
The table below shows the percentage change of British Pound (GBP) against listed major currencies this week. British Pound was the weakest against the Canadian Dollar.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 0.76% | 0.54% | 1.37% | -0.22% | 0.00% | 0.68% | 0.48% | |
| EUR | -0.76% | -0.20% | 0.61% | -0.94% | -0.69% | -0.04% | -0.18% | |
| GBP | -0.54% | 0.20% | 0.94% | -0.74% | -0.49% | 0.16% | 0.02% | |
| JPY | -1.37% | -0.61% | -0.94% | -1.51% | -1.40% | -0.64% | -0.80% | |
| CAD | 0.22% | 0.94% | 0.74% | 1.51% | 0.27% | 0.91% | 0.77% | |
| AUD | -0.00% | 0.69% | 0.49% | 1.40% | -0.27% | 0.65% | 0.51% | |
| NZD | -0.68% | 0.04% | -0.16% | 0.64% | -0.91% | -0.65% | -0.16% | |
| CHF | -0.48% | 0.18% | -0.02% | 0.80% | -0.77% | -0.51% | 0.16% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the British Pound from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent GBP (base)/USD (quote).
Following a bullish start to the week, the US Dollar (USD) continued to gather strength on Tuesday, forcing GBP/USD to push lower. The risk-averse market atmosphere amid escalating geopolitical tensions helped the USD outperform its rivals. Meanwhile, the US Bureau of Labor Statistics reported that the number of job openings on the last business day of August stood at 8.04, up from 7.71 million in July and above the market expectation of 7.65 million, further supporting the USD.
The Automatic Data Processing (ADP) will publish the private sector employment report later in the day. Investors expect the private sector payrolls to rise by 120,000 following August's 99,000 increase. A disappointing print below 100,000 could cause investors to price in a negative surprise in Friday's Nonfarm Payrolls data and cause the USD to come under selling pressure. On the other hand, a reading above the market forecast could help the USD hold its ground.
Investors will also pay close attention to headlines surrounding the crisis in the Middle East. Israel has vowed to retaliate after Iran has fired about 200 ballistic missiles. In the meantime, the Israeli Defense Forces has reportedly deployed additional troops to Lebanon, prompting the evacuation of 24 villages in Southern Lebanon. A further escalation of geopolitical tensions could allow the USD to benefit from safe-haven flows.
GBP/USD Technical Analysis
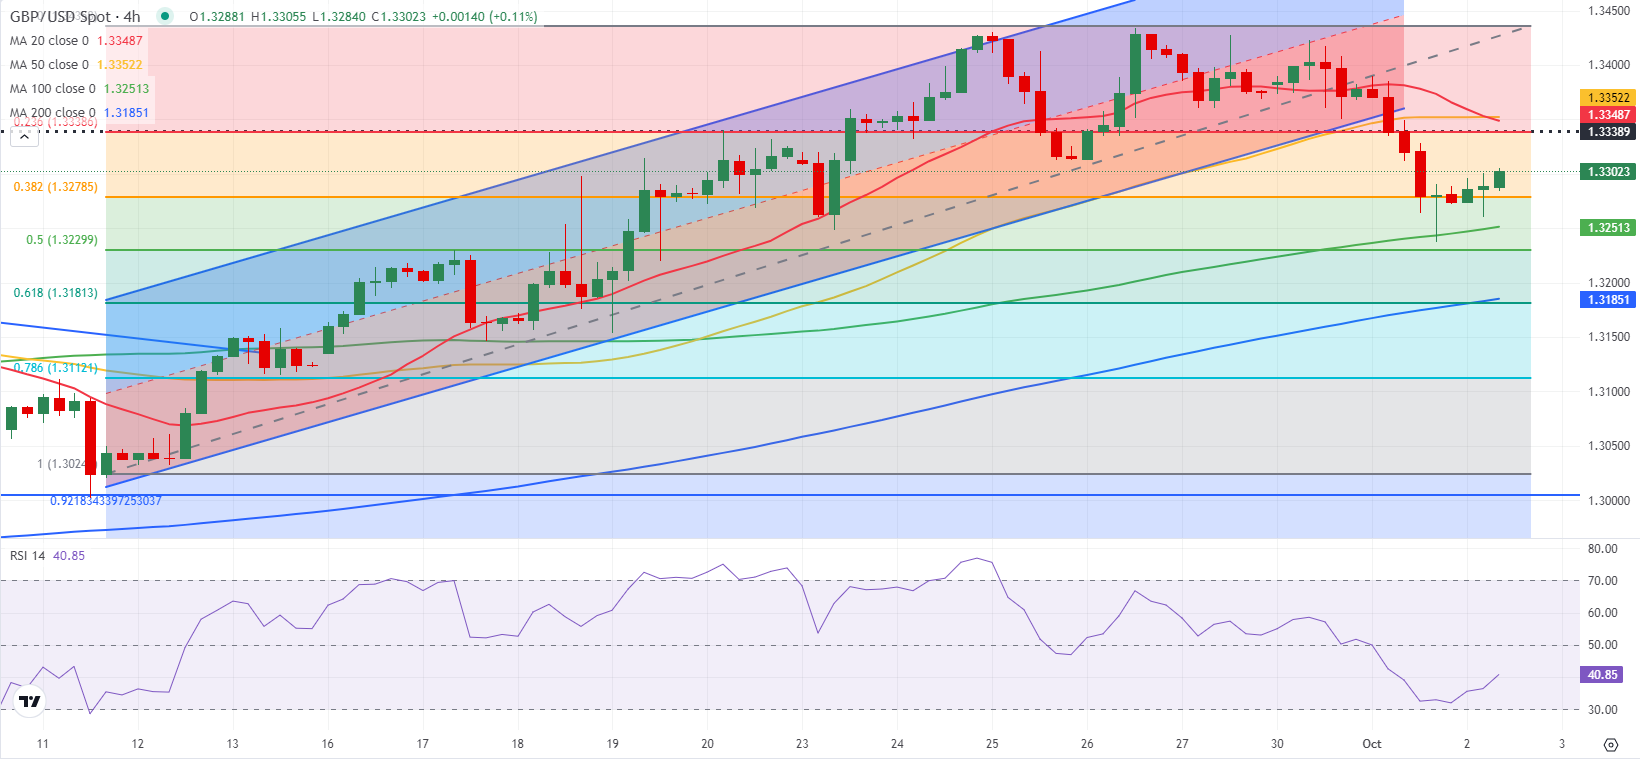
The Relative Strength Index (RSI) indicator on the 4-hour chart stays well below 50, suggesting that the recent recovery attempt could be a technical correction rather than the beginning of a reversal.
On the downside, interim support is located at 1.3275 (Fibonacci 38.2% retracement of the latest uptrend) before 1.3250, where the 100-period Simple Moving Average (SMA) is located. A daily close below the latter could attract technical sellers and open the door for another leg lower toward 1.3180 (200-period SMA).
In case GBP/USD stabilizes above 1.3300 (static level), it could face next resistance at 1.3340-1.3350 (Fibonacci 23.6% retracement, 50-period SMA, 20-period SMA) before 1.3400 (round level).
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, also known as ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Eren Sengezer
FXStreet
As an economist at heart, Eren Sengezer specializes in the assessment of the short-term and long-term impacts of macroeconomic data, central bank policies and political developments on financial assets.
















