|

S&P 500 reclaims the 4000 mark, as US equities record its best month since 2020

  • The three major US equity indices advanced between 0.97% and 1.88%.
  • A risk-on impulse since last Wednesday underpinned US equities, lifted by US corporate earnings of Amazon and Apple.
  • The US Dollar Index fell below 106.000, while the US 10-year T-note yield finished around 2.654%.
S&P 500 reclaims the 4000 mark, as US equities record its best month since 2020

US equities finished the week on a higher note, as Amazon and Apple soared as earnings from both companies exceeded analysts’ estimates after the US Federal Reserve hiked rates 75 bps in the week, spurring a rally that carried on until the end of the week/month.

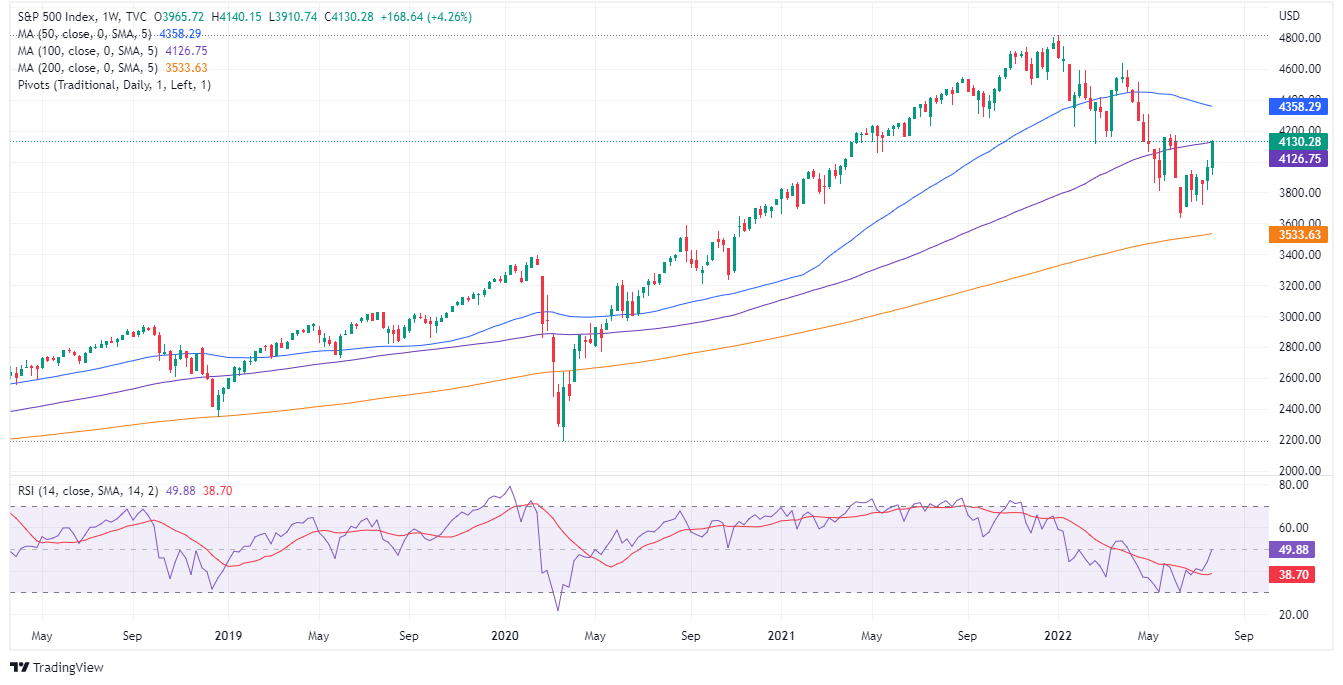
The S&P 500 closed the week gaining 1.42%, at 4,130.28, while the tech-heavy Nasdaq rose 1.88%, up to 12,390.69. Additionally, the Dow Jones Industrial followed suit and climbed 0.97%, finishing at 32,845.13.

Sector-wise,  the leading sectors are Energy, up by 4.51 %, followed by Consumer Discretionary and Industrials, each recording gains of 4.27% and 2%, respectively. The biggest losers were Consumer Staples and Health, diving 0.72% and 0.35% each.

Shares fell due to Walmart cutting its earnings forecast, complaining about double-digit food prices and elevated energy prices. Additionally, the US Federal Reserve monetary policy decision is looming, and Europe’s escalating energy crisis re-ignited recession fears amongst traders, which turned to safe-haven assets, namely the greenback.

Global equities remain to trade positively, reflecting an upbeat sentiment. Data-wise, the US Department of Commerce revealed that June’s Personal Consumption Expenditure rose 1% MoM, higher than 0.9% estimations. Annually based, edged higher by 6.8%, vs. 6.7% foreseen by analysts.

Late, the University of Michigan reported that Consumer Sentiment on its final reading for July beat expectations and rose 51.5. In the same survey, inflation expectations for a 5-year horizon, from 2.8% (preliminary) to 2.9%, though less than June’s readings.

In the meantime, Fed speakers began to cross wires. The first one was Atlanta’s Fed President Raphael Bostic, who said that the Fed is “going to have to do more in terms of interest-rate moves” and added that he does not think the country is in a recession. In the meantime, Christopher Waller said that “a soft landing is a plausible outcome for the labor market going forward.”

Elsewhere, the US Dollar Index (DXY), a measurement of the greenback’s value against some currencies, fell 0.67% to 105.828, while the 10-year US Treasury yield dropped two bps, yielding 2.654%.

In the commodities complex, WTI gained 1.95%, exchanging hands at $98.30 BPD. Meanwhile, precious metals like gold (XAU/USD) increased by 0.78%, trading at $1764.00 a troy ounce.

SP 500 Chart
Key Technical Levels

SP 500

Overview
Today last price4130.28
Today Daily Change60.48
Today Daily Change %1.49
Today daily open4069.43
 
Trends
Daily SMA203893.98
Daily SMA503915.32
Daily SMA1004113.38
Daily SMA2004339.59
 
Levels
Previous Daily High4077.73
Previous Daily Low3991.58
Previous Weekly High4011.65
Previous Weekly Low3817.67
Previous Monthly High4181.86
Previous Monthly Low3636.65
Daily Fibonacci 38.2%4044.82
Daily Fibonacci 61.8%4024.49
Daily Pivot Point S14014.76
Daily Pivot Point S23960.1
Daily Pivot Point S33928.61
Daily Pivot Point R14100.91
Daily Pivot Point R24132.4
Daily Pivot Point R34187.06

Author

Christian Borjon Valencia

Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.


More from Christian Borjon Valencia
Share:

Editor's Picks

AUD/USD bears retain control near YTD low, 0.6650 tested

AUD/USD sits at fresh YTD lows near 0.6550 in Friday's Asian session and looks vulnerable to further downside. The US Dollar holds near April 2025 highs amid renewed US-Iran tensions and aggressive Fed rate-hike bets. Moreover, Thursday’s dismal Aussie jobs data, the RBA’s dovish tilt and PBOC's status-quo continue to weigh on the Aussie, validating the negative outlook for the currency pair.

USD/JPY drops below 159.50 after Japan’s National CPI

USD/JPY has turned south below mid-159.00s in the Asian session on Friday, as the Japanese Yen gains ground following the country's National CPI, which reaffirmed the December BoJ rate hike. Further, a broader risk-off market environment lifts the Yen's safe-haven appeal. However, hawkish Fed outlook and renewed US-Iran tensions keep the US Dollar supported, which could limit the pair's downside.


Gold: The $3,500 zone holds the downside… for now

Gold further extends its deep pullback, coming close to the key $3,500 mark per troy ounce as Friday’s European session draws to a close. Furthermore, the yellow metal has traded with losses since Monday, always tracking rising bets for extra tightening by the Fed and the lack of any progress from the Middle East conflict.

Bitcoin slips below $60,000 as selling pressure accelerates

Bitcoin price slips below $60,000 on Friday, reaching a level not seen since early July. Momentum indicators suggest firm selling pressure despite reaching oversold levels.

Week ahead – Flash PMIs and PCE inflation in focus ahead of Thanksgiving

US flash PMIs and PCE inflation data could shape Fed rate expectations. Eurozone and UK PMIs will offer an early look at business activity. Australia’s CPI data could influence expectations for the RBA’s next move.

Gold's 14-month low looks mild next to Silver's fall from $121 to $44
Gold has lost a third of its value since January as traders bet on more Federal Reserve rate increases. Silver has lost nearly two-thirds, because the buyers still holding Gold up have no equivalent in the Silver market. Gold is trading below $3,700 for the first time since September 2025, a little more than a third under the record near $5,600 it set in late January.















