Pound Sterling weakens as stubborn US inflation improves safe-haven demand
- The Pound Sterling tumbles as hot US inflation data dampens market sentiment.
- UK Employment data for the three months ending January indicates weak labor demand and slower wage growth.
- Cooling UK labor market conditions lift up BoE rate cut hopes.

The Pound Sterling (GBP) witnesses an intense sell-off in Tuesday’s early American session as the United States Bureau of Labor Statistics (BLS) has reported a hot Consumer Price Index (CPI) report for February, and the United Kingdom Office for National Statistics (ONS) has reported soft Employment data.
US monthly headline inflation grew by 0.4%, as expected, against a 0.3% increase in January. In the same period, core inflation, which strips off volatile food and energy prices, rose steadily by 0.4%. Investors anticipated the core CPI to grow at a slower pace of 0.3%. As for annual figures, the headline CPI accelerated to 3.2% from expectations and the former release of 3.1% and the core inflation decelerated slightly to 3.8% from 3.9% in January. Investors forecasted that the underlying inflation data will soften sharply to 3.7%.
Figures from the UK ONS show that higher interest rates from the Bank of England (BoE) and the deepening cost-of-living crisis are starting to dampen labor market conditions. The UK’s Unemployment Rate increased to 3.9%, employers fired 21K workers, and Average Earnings grew slower in the three months ending January. The labor market data clearly demonstrates uncertainty over the economic outlook, which could force BoE policymakers to start reducing interest rates earlier than previously expected.
Daily digest market movers: Pound Sterling drops sharply while US Dollar soars
- The Pound Sterling falls sharply as the United Kingdom ONS reported softer-than-expected Employment data for the three months ending in January.
- The Unemployment Rate climbed to 3.9%, higher than expectations and the prior reading of 3.8%. UK employers laid off 21K workers against hiring of 72K job-seekers in three months ending in December. In February, the Claimant Count Change grew moderately by 16.8K from expectations of 20.3K. In January, individuals claiming jobless benefits were 3.1K, downwardly revised from 14.1K.
- Average Earnings Excluding Bonuses grew by 6.1%, against expectations and the previous reading of 6.2%. Earnings including bonuses rose at a slower pace of 5.6%, against the consensus of 5.7% and the prior reading of 5.8%.
- The pace at which Average Earnings (both with and without bonuses) for three months ending January declines is higher than expected by market participants. Slower wage growth is expected to allow Bank of England policymakers to consider rate cuts earlier than anticipated.
- Conversely, on Monday, BoE policymaker Catherine Mann warned that there is a long way to go to bring down inflation sustainably to the desired target of 2%. Mann was one of the two policymakers who voted for a rate hike in the February monetary policy meeting.
- This week, the Pound Sterling will remain in action as investors will shift focus to the UK monthly Gross Domestic Product (GDP) and the factory data for January, which will be published on Wednesday.
Technical Analysis: Pound Sterling drops to 1.2760
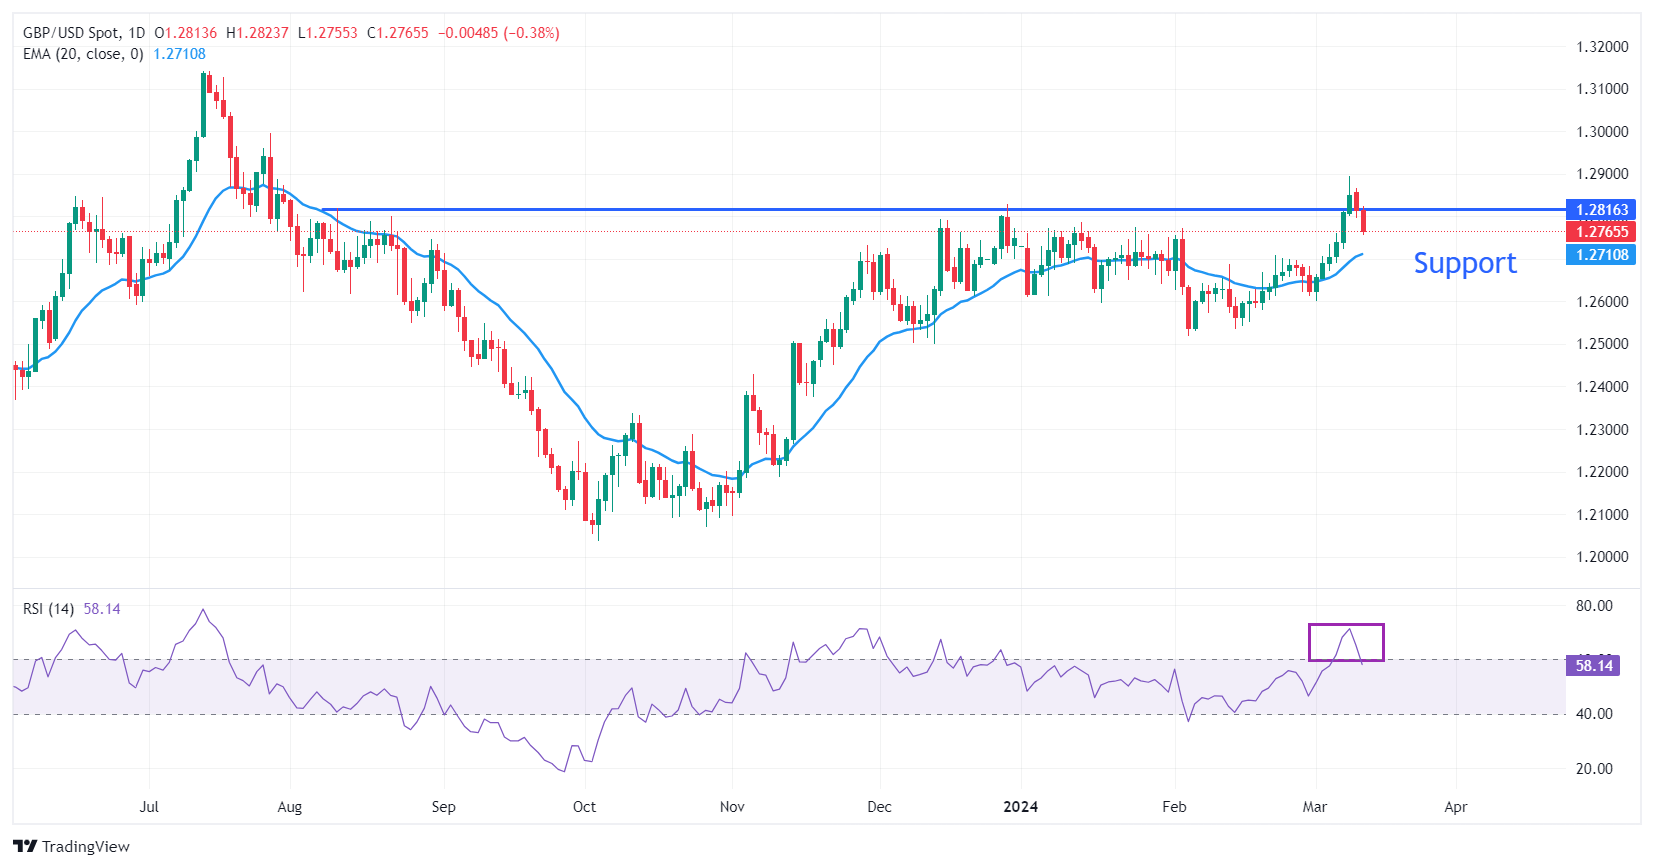
The Pound Sterling edges down below the round-level support of 1.2800 against the US Dollar after downbeat UK labor market data. The near-term appeal of the GBP/USD is still upbeat as the 20-day Exponential Moving Average (EMA) at 1.2720 is sloping towards the north. The pair has corrected from a seven-month high of 1.2894 to near the horizontal support plotted from the August 10 high at 1.2819.
The 14-period Relative Strength Index (RSI) is inches lower from its recent peak of 71.33, but the broader momentum remains bullish.
Risk sentiment FAQs
In the world of financial jargon the two widely used terms “risk-on” and “risk off'' refer to the level of risk that investors are willing to stomach during the period referenced. In a “risk-on” market, investors are optimistic about the future and more willing to buy risky assets. In a “risk-off” market investors start to ‘play it safe’ because they are worried about the future, and therefore buy less risky assets that are more certain of bringing a return, even if it is relatively modest.
Typically, during periods of “risk-on”, stock markets will rise, most commodities – except Gold – will also gain in value, since they benefit from a positive growth outlook. The currencies of nations that are heavy commodity exporters strengthen because of increased demand, and Cryptocurrencies rise. In a “risk-off” market, Bonds go up – especially major government Bonds – Gold shines, and safe-haven currencies such as the Japanese Yen, Swiss Franc and US Dollar all benefit.
The Australian Dollar (AUD), the Canadian Dollar (CAD), the New Zealand Dollar (NZD) and minor FX like the Ruble (RUB) and the South African Rand (ZAR), all tend to rise in markets that are “risk-on”. This is because the economies of these currencies are heavily reliant on commodity exports for growth, and commodities tend to rise in price during risk-on periods. This is because investors foresee greater demand for raw materials in the future due to heightened economic activity.
The major currencies that tend to rise during periods of “risk-off” are the US Dollar (USD), the Japanese Yen (JPY) and the Swiss Franc (CHF). The US Dollar, because it is the world’s reserve currency, and because in times of crisis investors buy US government debt, which is seen as safe because the largest economy in the world is unlikely to default. The Yen, from increased demand for Japanese government bonds, because a high proportion are held by domestic investors who are unlikely to dump them – even in a crisis. The Swiss Franc, because strict Swiss banking laws offer investors enhanced capital protection.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.

















