Gold surge stalls after JOLTs data, FOMC minutes awaited
- Gold climbs to $2,664 but faces pressure from a strong US labor market and Trump's assertive tariff plans.
- Trump’s unexpected remarks on reclaiming the Panama Canal and imposing tariffs on neighbors bolster the US Dollar.
- People's Bank of China boosts gold reserves, signaling increased demand as global economic uncertainties persist.
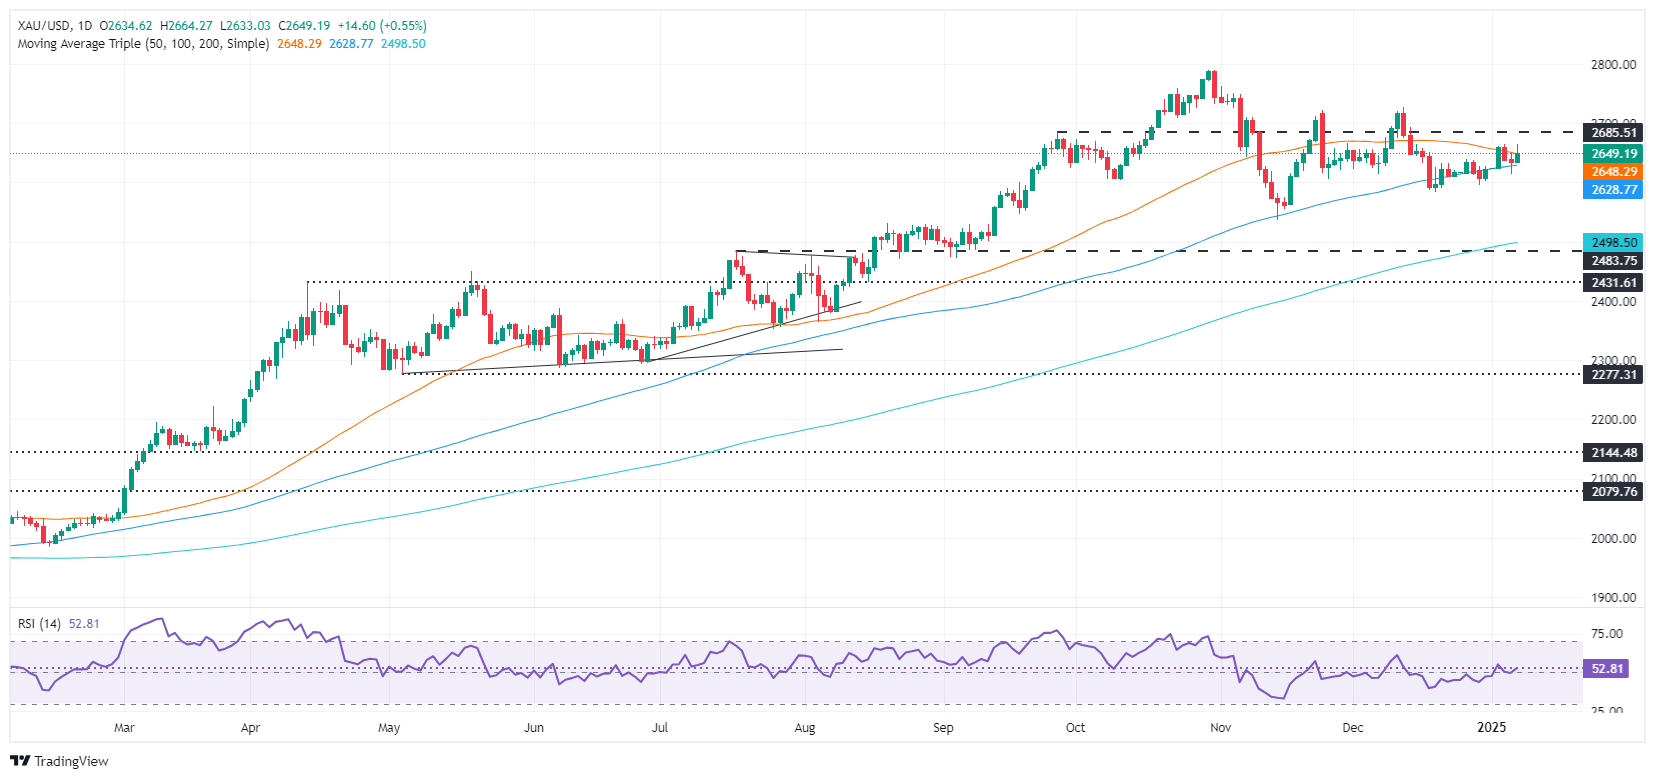
Gold price advanced late in the North American session on Tuesday yet retreated from daily highs on solid United States (US) economic data and US President-elect Donald Trump’s press conference remarks. The XAU/USD trades at $2,648, gains 0.50%.
In the United States, the schedule revealed a strong jobs report amid an increase in job openings, reassuring investors that the labor market is solid. Furthermore, business activity in the services sector improved sharply, weighing on expectations for further easing by the Federal Reserve (Fed).
In the meantime, US President-elect Donald Trump crossed the wires, said he would like to take back control of the Panama Canal and reiterated that he would impose tariffs on Canada and Mexico. This boosted the US Dollar (USD) and capped Gold’s advance.
Earlier, Bullion rose to a two-day peak of $2,664 after China’s central bank increased its Gold reserves for the second straight month by 300K ounces to 73.3 million, an indication that the People’s Bank of China (PBoC) resumed its purchases after a six-month pause.
US Treasury bond yields remained high, bolstering the Greenback. According to the Fed funds futures interest rate contract at the Chicago Board of Trade (CBOT), investors estimate 51 basis points (bps) of easing or two 25 bps interest rate cuts by the Fed toward the end of the year.
Ahead this week, the US economic docket will feature the ADP Employment Change, Initial Jobless Claims figures, the Fed’s last meeting minutes and December’s US Nonfarm Payrolls report.
Daily digest market movers: Gold price climbs amid high US yields, underpinned by PBoC purchases
- Gold remains pressured as US real yields rise two bps up to 2.28%.
- The US 10-year T-note yield soars six and a half bps to 4.691%.
- The US Dollar Index (DXY), which tracks the buck’s performance against a basket of six currencies, edges up by 0.26% at 108.55 after bouncing from a weekly low of 107.75.
- The ISM Services PMI in December increased by 54.1, exceeding forecasts of 53.3 and November’s 52.1 reading.
- The Job Labor and Turnover Survey (JOLTS) revealed that work openings increased from 7.839 million to 8.098 million in November.
- The US trade deficit widened in November, according to the US BEA, reaching $78.2 billion compared to $73.6 billion in October.
- Imports climbed by 3.4% MoM to $351.6 billion from $339.9 billion, while exports increased by 2.7%MoM to $273.4 billion from $266.3 billion.
XAU/USD technical outlook: Gold price advances but remains below $2,650
Gold prices have advanced above $2,640, opening the door to exchange hands at around the $2,640 - $2,650 range. Nonetheless, the yellow metal cannot decisively clear the 50-day Simple Moving Average (SMA) at around $2,651, which could pave the way for further upside.
In that outcome, the next ceiling level would be $2,700 ahead of challenging the December 12 peak at $2,726. If surpassed, the next stop would be the record high at $2,790.
Conversely, if sellers drag the XAU/USD below the 100-day SMA of $2,627, look for a test of $2,500 before Gold extends its losses to the 200-day SMA at $2,494.
Gold FAQs
Gold has played a key role in human’s history as it has been widely used as a store of value and medium of exchange. Currently, apart from its shine and usage for jewelry, the precious metal is widely seen as a safe-haven asset, meaning that it is considered a good investment during turbulent times. Gold is also widely seen as a hedge against inflation and against depreciating currencies as it doesn’t rely on any specific issuer or government.
Central banks are the biggest Gold holders. In their aim to support their currencies in turbulent times, central banks tend to diversify their reserves and buy Gold to improve the perceived strength of the economy and the currency. High Gold reserves can be a source of trust for a country’s solvency. Central banks added 1,136 tonnes of Gold worth around $70 billion to their reserves in 2022, according to data from the World Gold Council. This is the highest yearly purchase since records began. Central banks from emerging economies such as China, India and Turkey are quickly increasing their Gold reserves.
Gold has an inverse correlation with the US Dollar and US Treasuries, which are both major reserve and safe-haven assets. When the Dollar depreciates, Gold tends to rise, enabling investors and central banks to diversify their assets in turbulent times. Gold is also inversely correlated with risk assets. A rally in the stock market tends to weaken Gold price, while sell-offs in riskier markets tend to favor the precious metal.
The price can move due to a wide range of factors. Geopolitical instability or fears of a deep recession can quickly make Gold price escalate due to its safe-haven status. As a yield-less asset, Gold tends to rise with lower interest rates, while higher cost of money usually weighs down on the yellow metal. Still, most moves depend on how the US Dollar (USD) behaves as the asset is priced in dollars (XAU/USD). A strong Dollar tends to keep the price of Gold controlled, whereas a weaker Dollar is likely to push Gold prices up.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















