GBP/USD cracks through 1.30 as bears regain control
- GBP/USD backslid another two-thirds of one percent on Wednesday.
- Cable shed more weight after UK CPI inflation figures missed the mark.
- US & UK Retail Sales figures go head-to-head with releases on Thursday and Friday, respectively.

Tension snapped in GBP/UISD chart action on Wednesday, with Cable losing the tug of war and backsliding out of recent congestion. Cable tumbled two-thirds of one percent and slipped below the 1.3000 handle during the midweek market session. GBP markets withered after UK Consumer Price Index (CPI) inflation figures missed the mark, sending the Pound Sterling to a fresh eight-week low.
UK CPI inflation number widely missed median market forecasts as inflation drops faster and further than investors initially anticipated in September. Headline CPI inflation for the year ended in September eased to 1.7% from 2.2%, with markets expecting a print of 1.9%. Core CPI inflation remains stubbornly higher than headline inflation measures, but still eased faster than expected, dipping to 3.2% YoY from the previous 3.6% and wringing extra out of the forecast 3.4%.
The UK is witnessing its slowest pace of annual inflation growth since May of 2021, and rising concerns of a deepening economic slowdown are dragging Cable lower. UK Producer Price Index (PPI) figures also contracted more than expected in September, with headline PPI Output prices swooning -0.7% YoY, below the forecast -0.6% and eating away the previous 0.2%. The UK Retail Price Index also hit its lowest measure since April of 2021, falling to 2.7% YoY compared to the previous period’s 3.5% and the median market forecast of 3.1%.
Up next on the data docket will be Thursday’s US Retail Sales. Markets are expecting an improvement in US retailer volumes, forecasting a MoM uptick of 0.3% in September Retail Sales compared to August’s 0.1% print.
The UK’s last chance to impress traders will come on Friday, when UK Retail Sales figures get released. Unfortunately, investors aren’t expecting much; September’s UK Retail Sales are forecast to slump to -0.3% MoM from the previous 0.1%.
GBP/USD price forecast
GBP/USD is set to close for a third straight week in the red as long as Greenback bulls can keep their hands on the wheel for the back half of the trading week. The pair has declined nearly 3.5% after hitting multi-month highs near 1.3450 in September, and the loss of the 1.3000 handle serves as a last-chance wakeup call for Pound Sterling bidders.
GBP/USD daily chart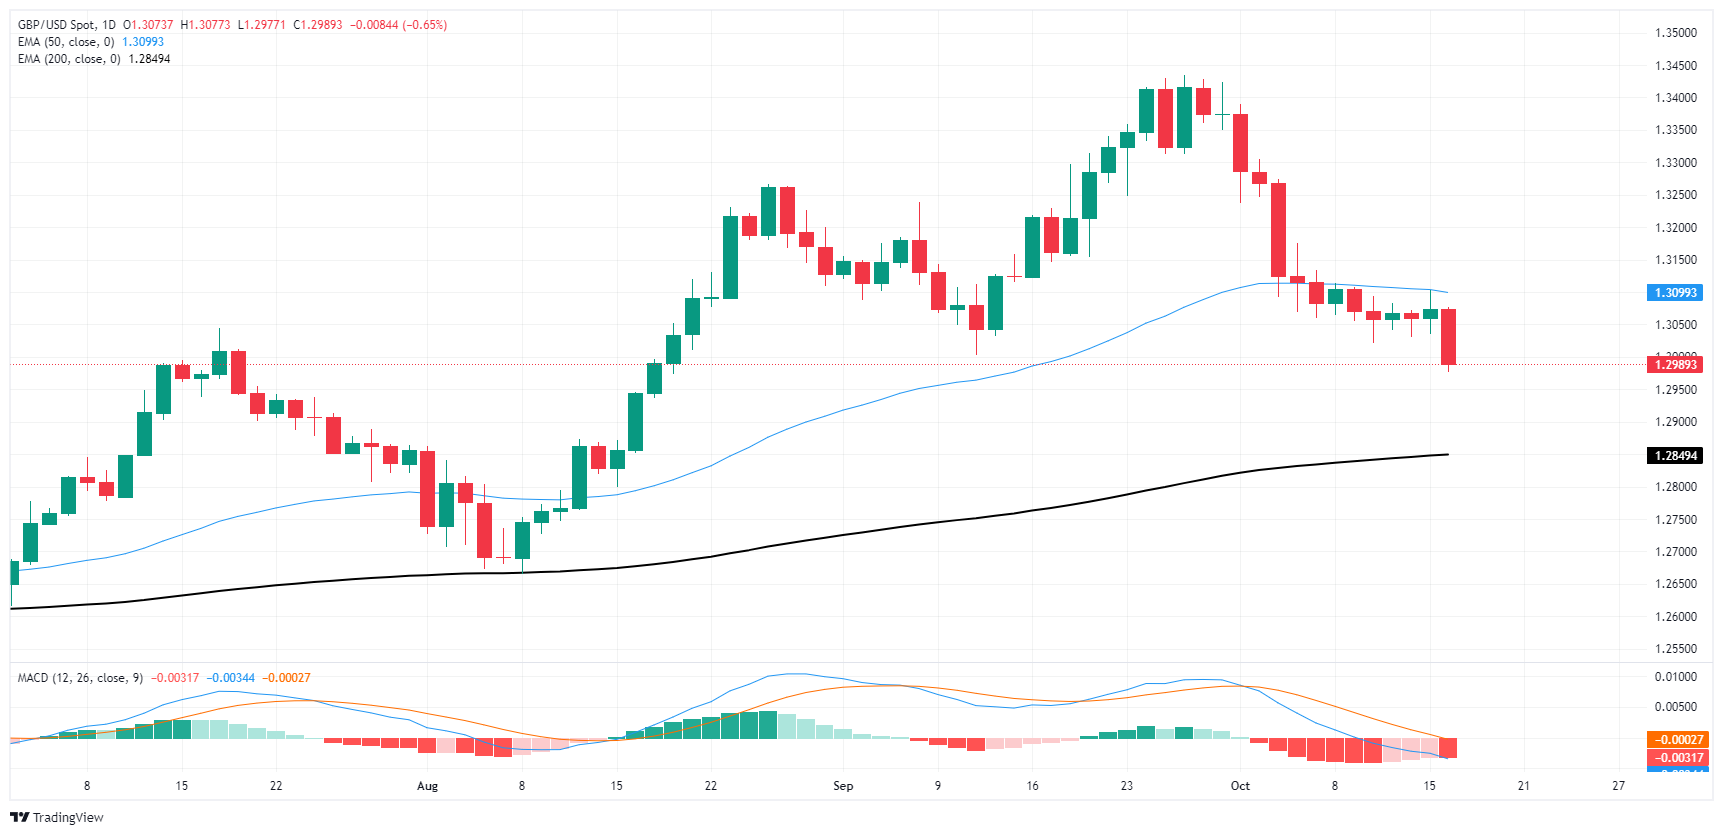
Euro FAQs
The Euro is the currency for the 19 European Union countries that belong to the Eurozone. It is the second most heavily traded currency in the world behind the US Dollar. In 2022, it accounted for 31% of all foreign exchange transactions, with an average daily turnover of over $2.2 trillion a day. EUR/USD is the most heavily traded currency pair in the world, accounting for an estimated 30% off all transactions, followed by EUR/JPY (4%), EUR/GBP (3%) and EUR/AUD (2%).
The European Central Bank (ECB) in Frankfurt, Germany, is the reserve bank for the Eurozone. The ECB sets interest rates and manages monetary policy. The ECB’s primary mandate is to maintain price stability, which means either controlling inflation or stimulating growth. Its primary tool is the raising or lowering of interest rates. Relatively high interest rates – or the expectation of higher rates – will usually benefit the Euro and vice versa. The ECB Governing Council makes monetary policy decisions at meetings held eight times a year. Decisions are made by heads of the Eurozone national banks and six permanent members, including the President of the ECB, Christine Lagarde.
Eurozone inflation data, measured by the Harmonized Index of Consumer Prices (HICP), is an important econometric for the Euro. If inflation rises more than expected, especially if above the ECB’s 2% target, it obliges the ECB to raise interest rates to bring it back under control. Relatively high interest rates compared to its counterparts will usually benefit the Euro, as it makes the region more attractive as a place for global investors to park their money.
Data releases gauge the health of the economy and can impact on the Euro. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the single currency. A strong economy is good for the Euro. Not only does it attract more foreign investment but it may encourage the ECB to put up interest rates, which will directly strengthen the Euro. Otherwise, if economic data is weak, the Euro is likely to fall. Economic data for the four largest economies in the euro area (Germany, France, Italy and Spain) are especially significant, as they account for 75% of the Eurozone’s economy.
Another significant data release for the Euro is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought after exports then its currency will gain in value purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















