Australian Dollar keeps recovery mode intact ahead of US Retail Sales
- The Australian Dollar stages a comeback as US Dollar Index pulls back from yearly highs.
- The Aussie Dollar may face challenges due to recent weak domestic and Chinese economic data.
- RBA Governor Bullock stated that current interest rates will remain unchanged until the bank gains confidence in the inflation outlook.

The Australian Dollar (AUD) sustains the rebound from three-month lows against the US Dollar (USD) on Friday. The recent downward trend in the AUD/USD pair is largely due to key economic data from Australia released on Thursday. Additionally, the AUD remained uninfluenced by mixed economic data from its close trading partner China.
China’s Retail Sales rose 4.8% year-over-year in October, surpassing the expected 3.8% and the 3.2% increase seen in September. Meanwhile, the country’s Industrial Production grew by 5.3% YoY, slightly below the forecasted 5.6% but higher than the 5.4% growth recorded in the previous period.
China's National Bureau of Statistics (NBS) shared its economic outlook during its press conference, noting an improvement in China's consumer expectations in October. The bureau plans to intensify policy adjustments and boost domestic demand, highlighting that recent policies have had a positive impact on the economy.
However, the decline of the Aussie Dollar may be limited due to less dovish remarks from Reserve Bank of Australia (RBA) Governor Michele Bullock on Thursday. Bullock stated that current interest rates are sufficiently restrictive and will stay at this level until the central bank gains confidence in the inflation outlook.
The US Dollar Index (DXY), which tracks the US Dollar's performance against six major currencies, has pulled back from its yearly high of 107.06 recorded on Thursday. This decline is attributed to a slowdown in "Trump trades." At the time of writing, the DXY trades near 106.50.
Markets are now focused on US October Retail Sales data, set to be released on Friday, along with comments from Federal Reserve officials. On Thursday, Fed Chair Jerome Powell noted that the recent performance of the US economy has been "remarkably good," allowing the Fed room to gradually lower interest rates.
Australian Dollar PRICE This week
The table below shows the percentage change of Australian Dollar (AUD) against listed major currencies this week. Australian Dollar was the weakest against the US Dollar.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 1.45% | 2.10% | 1.71% | 1.05% | 1.78% | 1.54% | 1.36% | |
| EUR | -1.45% | 0.61% | 0.33% | -0.27% | 0.42% | 0.19% | -0.01% | |
| GBP | -2.10% | -0.61% | -0.37% | -0.88% | -0.19% | -0.43% | -0.62% | |
| JPY | -1.71% | -0.33% | 0.37% | -0.62% | 0.00% | -0.05% | -0.32% | |
| CAD | -1.05% | 0.27% | 0.88% | 0.62% | 0.77% | 0.47% | 0.27% | |
| AUD | -1.78% | -0.42% | 0.19% | -0.01% | -0.77% | -0.26% | -0.44% | |
| NZD | -1.54% | -0.19% | 0.43% | 0.05% | -0.47% | 0.26% | -0.20% | |
| CHF | -1.36% | 0.00% | 0.62% | 0.32% | -0.27% | 0.44% | 0.20% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the Australian Dollar from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent AUD (base)/USD (quote).
Australian Dollar recovers further as US Dollar corrects downwards
- The US Producer Price Index (PPI) rose by 2.4% year-over-year in October, up from a revised 1.9% increase in September (previously 1.8%) and surpassing market expectations of 2.3%. Meanwhile, the Core PPI, which excludes food and energy, climbed 3.1% YoY, slightly above the anticipated 3.0%.
- Australia’s seasonally adjusted unemployment rate held steady at 4.1% in October for the third month in a row, matching market expectations. However, employment change data revealed only 15.9K new jobs added in October, which fell short of the anticipated 25.0K.
- Australia's Consumer Inflation Expectations dropped to 3.8% in November, down from 4.0% in the previous month, reaching the lowest level since October 2021.
- Federal Reserve (Fed) Bank of St. Louis President Alberto Musalem commented on Wednesday that persistent inflation challenges make it difficult for the Fed to continue easing rates. Musalem redirected attention to the overall strength of the US labor market, seeking to alleviate concerns about inflation's resistance to the Fed's downward pressure efforts.
- Federal Reserve Bank of Kansas City President Jeffrey Schmid highlighted potential challenges in lowering interest rates. Schmid also criticized market participants who continue to hold out hope for a return to near-zero rates, calling their expectations unrealistic.
- US Consumer Price Index (CPI) increased by 2.6% year-over-year in October, in line with market forecasts. Meanwhile, the core CPI, which excludes the more volatile food and energy components, rose by 3.3% as expected.
- Australia's Prime Minister Anthony Albanese shared in a radio interview on Wednesday that he discussed trade with US President-elect Donald Trump during a phone call last week. Albanese informed Trump that the United States holds a trade surplus with Australia and emphasized that it is in Washington's best interest to "trade fairly" with its ally. Meanwhile, the defense minister underscored Australia's significant investment in security.
- Last week, China's latest stimulus measures fell short of investor expectations, further dampening demand prospects for Australia’s largest trading partner and weighing on the Australian Dollar. China announced a 10 trillion Yuan debt package to alleviate local government financing pressures and support struggling economic growth. However, the package stopped short of implementing direct economic stimulus measures.
Technical Analysis: Australian Dollar bounces as RSI prods oversold zone
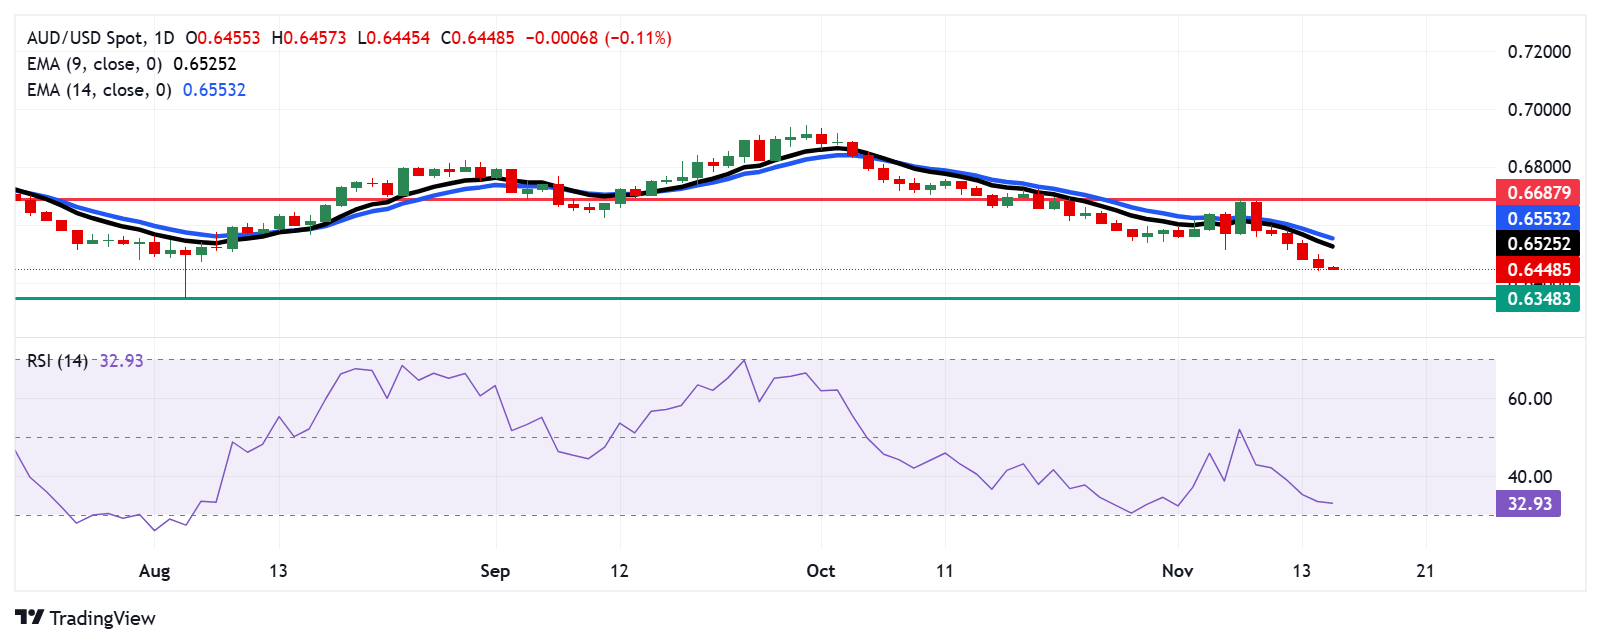
AUD/USD trades near 0.6470 on Friday. An analysis of the daily chart shows short-term downward pressure, as the pair remains below the nine-day Exponential Moving Average (EMA). Additionally, the 14-day Relative Strength Index (RSI) is slightly above 30, indicating potential oversold conditions. If the RSI dips below 30, it could signal an oversold situation, suggesting a possible upward correction.
The AUD/USD pair may find a key level near 0.6400 for support. A break below this psychological threshold could amplify downward pressure, potentially driving the pair toward the yearly low of 0.6348, last touched on August 5.
The immediate resistance lies at the psychological level of 0.6500. A break above this could lift the pair toward the nine-day EMA at 0.6525, followed by the 14-day EMA at 0.6553. Surpassing these EMAs may pave the way for a move toward the three-week high of 0.6687.
AUD/USD: Daily Chart
Australian Dollar FAQs
One of the most significant factors for the Australian Dollar (AUD) is the level of interest rates set by the Reserve Bank of Australia (RBA). Because Australia is a resource-rich country another key driver is the price of its biggest export, Iron Ore. The health of the Chinese economy, its largest trading partner, is a factor, as well as inflation in Australia, its growth rate and Trade Balance. Market sentiment – whether investors are taking on more risky assets (risk-on) or seeking safe-havens (risk-off) – is also a factor, with risk-on positive for AUD.
The Reserve Bank of Australia (RBA) influences the Australian Dollar (AUD) by setting the level of interest rates that Australian banks can lend to each other. This influences the level of interest rates in the economy as a whole. The main goal of the RBA is to maintain a stable inflation rate of 2-3% by adjusting interest rates up or down. Relatively high interest rates compared to other major central banks support the AUD, and the opposite for relatively low. The RBA can also use quantitative easing and tightening to influence credit conditions, with the former AUD-negative and the latter AUD-positive.
China is Australia’s largest trading partner so the health of the Chinese economy is a major influence on the value of the Australian Dollar (AUD). When the Chinese economy is doing well it purchases more raw materials, goods and services from Australia, lifting demand for the AUD, and pushing up its value. The opposite is the case when the Chinese economy is not growing as fast as expected. Positive or negative surprises in Chinese growth data, therefore, often have a direct impact on the Australian Dollar and its pairs.
Iron Ore is Australia’s largest export, accounting for $118 billion a year according to data from 2021, with China as its primary destination. The price of Iron Ore, therefore, can be a driver of the Australian Dollar. Generally, if the price of Iron Ore rises, AUD also goes up, as aggregate demand for the currency increases. The opposite is the case if the price of Iron Ore falls. Higher Iron Ore prices also tend to result in a greater likelihood of a positive Trade Balance for Australia, which is also positive of the AUD.
The Trade Balance, which is the difference between what a country earns from its exports versus what it pays for its imports, is another factor that can influence the value of the Australian Dollar. If Australia produces highly sought after exports, then its currency will gain in value purely from the surplus demand created from foreign buyers seeking to purchase its exports versus what it spends to purchase imports. Therefore, a positive net Trade Balance strengthens the AUD, with the opposite effect if the Trade Balance is negative.
Author

Akhtar Faruqui
FXStreet
Akhtar Faruqui is a Forex Analyst based in New Delhi, India. With a keen eye for market trends and a passion for dissecting complex financial dynamics, he is dedicated to delivering accurate and insightful Forex news and analysis.

















