EUR/USD Forecast: Euro bulls could remain interested while 1.1000 holds as support
- EUR/USD holds above 1.1000 after touching a fresh 2024-high on Wednesday.
- The US economic calendar will feature several key data releases on Thursday.
- The pair's technical outlook suggests that the bullish bias remains intact.

EUR/USD gathered bullish momentum and reached its highest level of 2024 near 1.1050 on Wednesday. The pair stays in a consolidation phase and trades slightly above 1.1000 in the European session on Thursday.
US Dollar PRICE This week
The table below shows the percentage change of US Dollar (USD) against listed major currencies this week. US Dollar was the strongest against the Japanese Yen.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | -0.80% | -0.64% | 0.49% | -0.20% | -0.63% | 0.06% | 0.14% | |
| EUR | 0.80% | 0.18% | 1.28% | 0.60% | 0.06% | 0.85% | 0.96% | |
| GBP | 0.64% | -0.18% | 1.34% | 0.42% | -0.13% | 0.67% | 0.78% | |
| JPY | -0.49% | -1.28% | -1.34% | -0.67% | -1.17% | -0.43% | -0.36% | |
| CAD | 0.20% | -0.60% | -0.42% | 0.67% | -0.47% | 0.26% | 0.37% | |
| AUD | 0.63% | -0.06% | 0.13% | 1.17% | 0.47% | 0.80% | 0.92% | |
| NZD | -0.06% | -0.85% | -0.67% | 0.43% | -0.26% | -0.80% | 0.10% | |
| CHF | -0.14% | -0.96% | -0.78% | 0.36% | -0.37% | -0.92% | -0.10% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the US Dollar from the left column and move along the horizontal line to the Japanese Yen, the percentage change displayed in the box will represent USD (base)/JPY (quote).
The data from the US showed on Wednesday that the Consumer Price Index (CPI) and the core CPI both rose 0.2% on a monthly basis in July, as forecast. The risk mood improved following the US inflation figures, making it difficult for the US Dollar (USD) to find demand.
In the European morning, US stock index futures trade modestly higher on the day. The US economic calendar will feature weekly Initial Jobless Claims and July Retail Sales data on Thursday.
A significant decline in the number of first-time application for unemployment benefits, with a reading below 220,000, could help the US Dollar (USD) gather strength with the immediate reaction. Meanwhile, Retail Sales are forecast to rise 0.3% after staying unchanged in June. A negative print could revive fears over an economic downturn in the US and hurt the USD, even if the Jobless Claims data comes in better than forecast.
Investors will also pay close attention to comments from Federal Reserve (Fed) officials. In case policymakers note that a 50 basis points (bps) rate cut is unlikely in September following the July inflation readings, the USD is likely to stay resilient against its rivals.
EUR/USD Technical Analysis
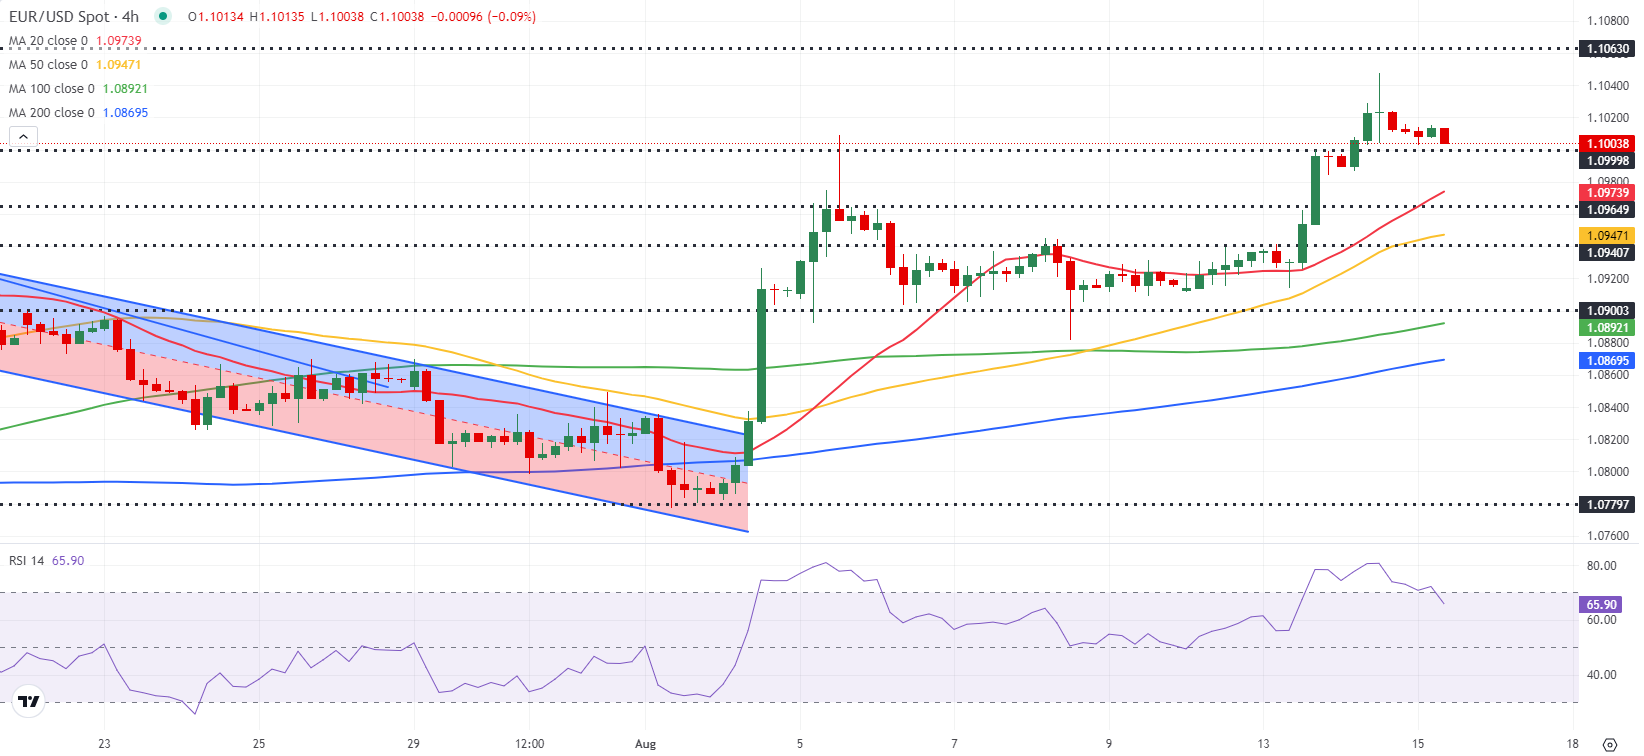
The Relative Strength Index (RSI) indicator on the 4-hour chart retreated below 70 after touching 80 on Wednesday, suggesting that the pair's bullish bias remains intact following a technical correction.
On the downside, 1.1000 (psychological level, static level) aligns as immediate support before 1.0960 (static level), 1.0940 (static level) and 1.0900 (psychological level, static level). In case the pair manages to hold above 1.1000, buyers could look to retain control. In this scenario, 1.1050-1.1060 (static level) could be seen as next resistance before 1.1100 (psychological level, static level).
Euro FAQs
The Euro is the currency for the 20 European Union countries that belong to the Eurozone. It is the second most heavily traded currency in the world behind the US Dollar. In 2022, it accounted for 31% of all foreign exchange transactions, with an average daily turnover of over $2.2 trillion a day. EUR/USD is the most heavily traded currency pair in the world, accounting for an estimated 30% off all transactions, followed by EUR/JPY (4%), EUR/GBP (3%) and EUR/AUD (2%).
The European Central Bank (ECB) in Frankfurt, Germany, is the reserve bank for the Eurozone. The ECB sets interest rates and manages monetary policy. The ECB’s primary mandate is to maintain price stability, which means either controlling inflation or stimulating growth. Its primary tool is the raising or lowering of interest rates. Relatively high interest rates – or the expectation of higher rates – will usually benefit the Euro and vice versa. The ECB Governing Council makes monetary policy decisions at meetings held eight times a year. Decisions are made by heads of the Eurozone national banks and six permanent members, including the President of the ECB, Christine Lagarde.
Eurozone inflation data, measured by the Harmonized Index of Consumer Prices (HICP), is an important econometric for the Euro. If inflation rises more than expected, especially if above the ECB’s 2% target, it obliges the ECB to raise interest rates to bring it back under control. Relatively high interest rates compared to its counterparts will usually benefit the Euro, as it makes the region more attractive as a place for global investors to park their money.
Data releases gauge the health of the economy and can impact on the Euro. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the single currency. A strong economy is good for the Euro. Not only does it attract more foreign investment but it may encourage the ECB to put up interest rates, which will directly strengthen the Euro. Otherwise, if economic data is weak, the Euro is likely to fall. Economic data for the four largest economies in the euro area (Germany, France, Italy and Spain) are especially significant, as they account for 75% of the Eurozone’s economy.
Another significant data release for the Euro is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought after exports then its currency will gain in value purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Eren Sengezer
FXStreet
As an economist at heart, Eren Sengezer specializes in the assessment of the short-term and long-term impacts of macroeconomic data, central bank policies and political developments on financial assets.















