US Dollar Index extends the advance to the 95.50 area
- The index pushes further north of the 95.00 yardstick on Tuesday.
- US markets return to normality following the MLK Jr. holiday.
- NY Empire State Index, NAHB Index, TIC Flows next on tap.

The greenback, when tracked by the US Dollar Index (DXY), keeps the buying bias unchanged and approaches the 95.50 region on turnaround Tuesday.
US Dollar Index up on yields, looks to data
The index advances for the third consecutive session on Tuesday amidst the renewed sentiment towards the buck and the relentless move higher in US yields across the curve.
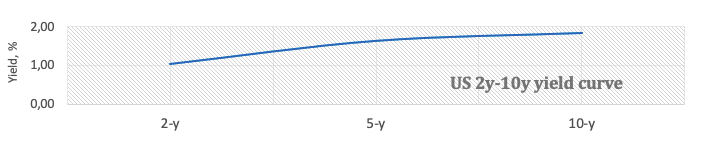
Indeed, yields of the 2y note trade well past the 1.0% yardstick for the first time in nearly two years, while the 10y reference approaches 1.85% and the long end trade in multi-month peaks above 2.16%. The closely watched 2y-10y yield spread now hovers around the 80 pts.
Meanwhile, investors continue to adjust to the increasing prospects of a Fed’s lift-off sooner than expected, with the March meeting a likely candidate to start the tightening cycle. Recent Fedspeak, Powell’s testimony last week and persistent elevated inflation underpins this potential scenario.
In the US data space, the NY Empire State Index is due in the first turn seconded by the NAHB Index, while November TIC Flows will close the calendar.
What to look for around USD
The index regained composure and reclaimed the 95.00 mark and above in past sessions, partially reversing the intense selloff witnessed during most of last week. Higher US yields propped up by firmer speculation of a sooner Fed’s lift-off and supportive Fedspeak helped the buck to regain part of the shine lost in past sessions, all against the backdrop of persistent elevated inflation and the solid performance of the US economy.
Key events in the US this week: NAHB Index, TIC Flows (Tuesday) – Building Permits, Housing Starts (Wednesday) – Initial Claims, Philly Fed Index, Existing Home Sales (Thursday).
Eminent issues on the back boiler: Start of the Fed’s tightening cycle. US-China trade conflict under the Biden’s administration. Debt ceiling issue. Potential geopolitical effervescence vs. Russia and China.
US Dollar Index relevant levels
Now, the index is gaining 0.07% at 95.31 and a break above 95.76 (55-day SMA) would open the door to 96.46 (2022 high Jan.4) and finally 96.93 (2021 high Nov.24). On the flip side, the next down barrier emerges at 94.62 (2022 low Jan.14) seconded by 93.27 (monthly low Oct.28 2021) and then 93.15 (200-day SMA).
Author

Pablo Piovano
FXStreet
Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.