|

US Dollar Index challenges daily highs near 96.30

  • DXY gathers steam following November’s Payrolls.
  • The US economy added fewer jobs than expected last month.
  • The ISM Non-Manufacturing, Factory Orders come next in the docket.

The greenback, in terms of the US Dollar Index (DXY), gathers some pace and retests the daily highs around 96.30 at the end of the week.

US Dollar Index bid post-NFP

The index now advances for the third session in a row on Friday and looks to consolidate the rebound above the 96.00 barrier following the release of November’s US labour market report.

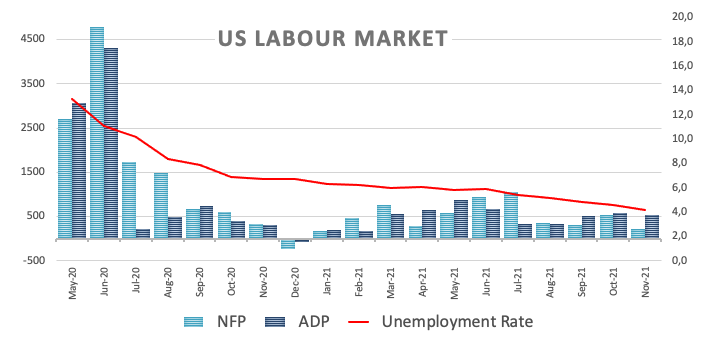
In fact, US yields and the dollar edge higher despite the US economy added “just” 210K jobs in November (vs. 550K estimated), although the jobless rate ticked lower and Average Hourly Earnings surprised to the downside at 0.3% MoM and 4.8% YoY.
In the meantime, yields across the curve add to gains seen in the second half of the week, with the 2y note flirting with tops around 0.65%, the belly advances past 1.45% and the long end approaches 1.80%.

The dollar remains on track to close the sixth consecutive week with gains, always underpinned by the uptrend in US yields, auspicious results from US fundamentals – which in turn support the idea of a strong recovery – a pick-up of risk aversion on omicron fears and lately by the hawkish twist in Powell’s testimony after he suggested the Fed will discuss adopting a quicker tapering pace at the December meeting, all pointing to a rates lift-off at some point in mid-2022.

Closing the weekly calendar, Markit will publish the final Services PMI seconded by the ISM Non-Manufacturing.

US Dollar Index relevant levels

Now, the index is gaining 0.10% at 96.22 and a break above 96.93 (2021 high Nov.24) would open the door to 97.00 (round level) and then 97.80 (high Jun.30 2020). On the flip side, the next down barrier emerges at 95.51 (weekly low Nov.30) followed by 94.96 (weekly low Nov.15) and finally 94.44 (low Nov.18).

Author

Pablo Piovano

Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.


More from Pablo Piovano
Share:

Editor's Picks

AUD/USD flirts with 0.7000, lowest since early August amid bullish USD

AUD/USD hits a fresh low since early August during the Asian session on Friday and looks vulnerable near 0.7000 after breaking below the 200-day SMA overnight. Against the backdrop of the hawkish Fed, a two-day rally in oil prices revives inflation fears and continues to push US bond yields to multi-year highs. Adding to this, geopolitical risks lift the US Dollar to a two-month high, overshadowing RBA rate hike bets and weighing on the pair.

USD/JPY pulls back from three-week high after failing near 159.00

USD/JPY edges lower during the Asian session on Friday, stalling its recent strong move to a three-week high of 159.00 as Japanese Yen bears turn cautious amid intervention fears. Meanwhile, the US Dollar retains a strong bullish undertone as the Fed's hawkish outlook and oil-driven inflation fears continue to push US bond yields to multi-year peaks. Furthermore, the BoJ's dovish rate hike last week might cap JPY and support spot prices.

Gold treads water below $4,300

Gold grabs some buying attention and advances marginally at the end of the week, partially retracing the weekly decline, although it is still navigating below the key $4,300 mark per troy ounce. The fresh selling bias on the Greenback and the modest decline in US Treasury yields appear to support the humble advance in the precious metal.

Crypto Today: Bitcoin and Ethereum edge lower, XRP extends recovery as macro headwinds weigh

The broader cryptocurrency market is consolidating on Friday, with Bitcoin paring losses slightly above $84,000. Ethereum declines in tandem with BTC. Ripple (XRP), meanwhile, paints a different picture.


Fed vs BoJ: Both hiked. The market only believes one of them – and the chart shows which
The Federal Reserve (Fed) and the Bank of Japan (BoJ) have just done something remarkably similar. Both central banks raised interest rates by 25 basis points (bps) last week, both are confronting inflation risks, and both signal that future decisions will depend on incoming economic data.
Fed vs BoJ: Both hiked. The market only believes one of them – and the chart shows which

The Fed and the BoJ have just done something remarkably similar. Both central banks raised interest rates by 25 bps last week, both are confronting inflation risks, and both signal that future decisions will depend on incoming economic data.

US Dollar Index challenges daily highs near 96.30













