US Dollar Index bounces off lows, approaches 96.00
- DXY regains some composure and trades closer to 96.00.
- Higher US yields sustain the recovery in the dollar so far.
- November’s Wholesale Inventories only due in the US docket.

The greenback, in terms of the US Dollar Index (DXY), returns to the positive territory and looks to reclaim the 96.00 neighbourhood at the beginning of the week.
US Dollar Index looks to data, yields, Powell
The index partially reverses Friday’s moderate pullback and trades on an upbeat note near the 96.00 mark amidst the continuation of the upside momentum in US yields across the curve, while market participants seem to have already digested the disheartening Payrolls results published on Friday (+199K).
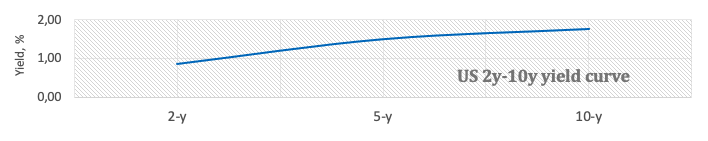
Still on the US cash markets, the short end of curve extends the upside and already flirts with the 0.90% mark, while yields of the key 10y benchmark note remain firm and at shouting distance from the 1.80% level. Furthermore, the closely watched 2y-10y yield spread approaches once again the 90 pts yardstick.
Monday’s US docket will only show the November Wholesale Inventories, although investors’ attention will largely be on the release of the inflation figures tracked by the CPI as well as December’s Retail Sales, both of them due later in the week.
What to look for around USD
The index ended last week on the defensive and in multi-day lows in the sub-96.00 area. The recent steady/bearish price action in the dollar came in contrast with the sharp advance in US yields across the curve and alternating risk appetite trends throughout the week. In the meantime, the dollar’s constructive outlook is seen underpinned by the Fed’s intentions to start the hiking cycle earlier than anticipated amidst persevering elevated inflation, supportive Fedspeak, higher yields and the solid performance of the US economy.
Key events in the US this week: Wholesale Inventories (Monday) - Fed J.Powell Testimony (Tuesday) - December CPI (Wednesday) - Initial Claims, FOMC L.Brainard Testimony, Producer Prices (Thursday) - Retail Sales, Industrial Production, Flash Consumer Sentiment, Business Inventories (Friday).
Eminent issues on the back boiler: Start of the Fed’s tightening cycle. US-China trade conflict under the Biden’s administration. Debt ceiling issue. Potential geopolitical effervescence vs. Russia and China.
US Dollar Index relevant levels
Now, the index is advancing 0.14% at 95.87 and a break above 96.46 (weekly top Jan.4) would open the door to 96.90 (weekly high Dec.15) and finally 96.93 (2021 high Nov.24). On the flip side, the next down barrier emerges at 96.61 (55-day SMA) seconded by 95.57 (monthly low Dec.31) and then 95.51 (weekly low Nov.30).
Author

Pablo Piovano
FXStreet
Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.
















