Swiss Franc: risks lie to the downside as inflation diverges from SNB forecasts
- Swiss Franc is vulnerable as inflation data continues to undershoot official forecasts.
- The SNB expected inflation to average 1.9% in 2024 in its December forecast, but it currently sits at 1.2%.
- The latest Producer and Import Prices showed the tenth month of deflation in a row.

The Swiss Franc (CHF) trades flat at the end of the trading week – off by barely a few hundredths of a percent in its most traded pairs. The overal fundamental outlook is not particulay favourable for CHF given Swiss inflation continues to decline and diverge from official estimates. This suggests the Swiss National Bank may feel the pressure to ease policy, a generally negative factor for the currency as it attracts lower inflows of foreign capital.
In its latest macroeconomic data release, Swiss Producer and Import Prices continued their deflationary trend in February, registering deflation for the tenth consecutive month at minus 2.0% (from negative 2.3% in January), according to data from the Federal Statistical Office.
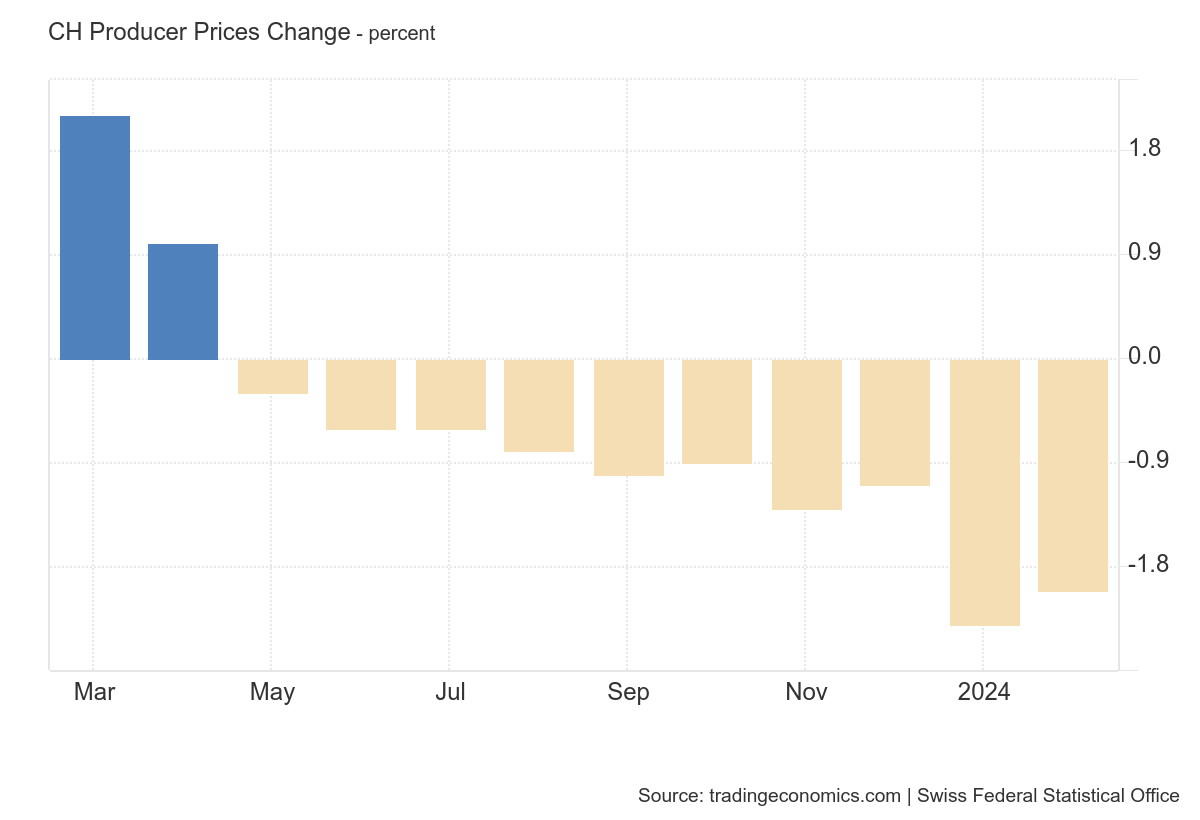
Swiss Franc at risk as inflation remains below SNB forecast
The Swiss Franc could be vulnerable to weakening further as inflation in Switzerland looks increasingly likely to undercut official forecasts.
In its latest batch of data, Swiss headline inflation rose 1.2% YoY in February, down from 1.3% in January, and increased 0.6%, up from 0.2% in January, on a month-on-month basis.
The data shows that inflation is undercutting the Swiss National Bank’s (SNB) own forecasts, which at its December policy meeting expressed the view that inflation would start rising from the 1.4% registered in November.
“However, inflation is likely to increase again somewhat in the coming months due to higher electricity prices and rents, as well as the rise in VAT.” The SNB said in its December policy statement.
The SNB implemented a rate hike of 0.25% in June 2023, raising rates from 1.50% to 1.75% to combat the threat of higher inflation. However, given the opposite has happened and inflation has actually come down quicker than expected, there is now a risk it could cut interest rates, which would be negative for the Swiss Franc, since lower rates attract less inflows of foreign capital.
The possibility of a change in policy is increased by the fact that inflation is running well below the SNB’s 1.9% forecast for 2024. Although there is only two months of data so far, it will have to rise substantially to meet the bank’s forecast before the end of the year. The SNB’s next policy meeting is on March 21.
SNB’s Jordan thinks Swiss Franc is too expensive
The Chairman of the SNB Thomas Jordan has expressed concerns about the Swiss Franc's excessive strength, particularly its impact on Swiss businesses, especially exporters. These concerns are reflected in data from Switzerland's Foreign Exchange Reserves (CHFER), which show a recovery in Forex reserves in 2024, indicating that the SNB may be selling Swiss Francs to bring the exchange rate down.
Technical Analysis: Swiss Franc oscillates in short-term range versus USD
The USD/CHF, which measures the number of Swiss Francs that one US Dollar can buy, has been oscillating within a relatively tight range between roughly 0.8900 and 0.8740 since the middle of February.
The pair is overall in short-term uptrend with the expectation that it will eventually breakout from the current range and start moving higher. However, resistance from a long-term trendline and the 50-week Simple Moving Average (SMA) present considerable obstacles to a prolongation of the trend.
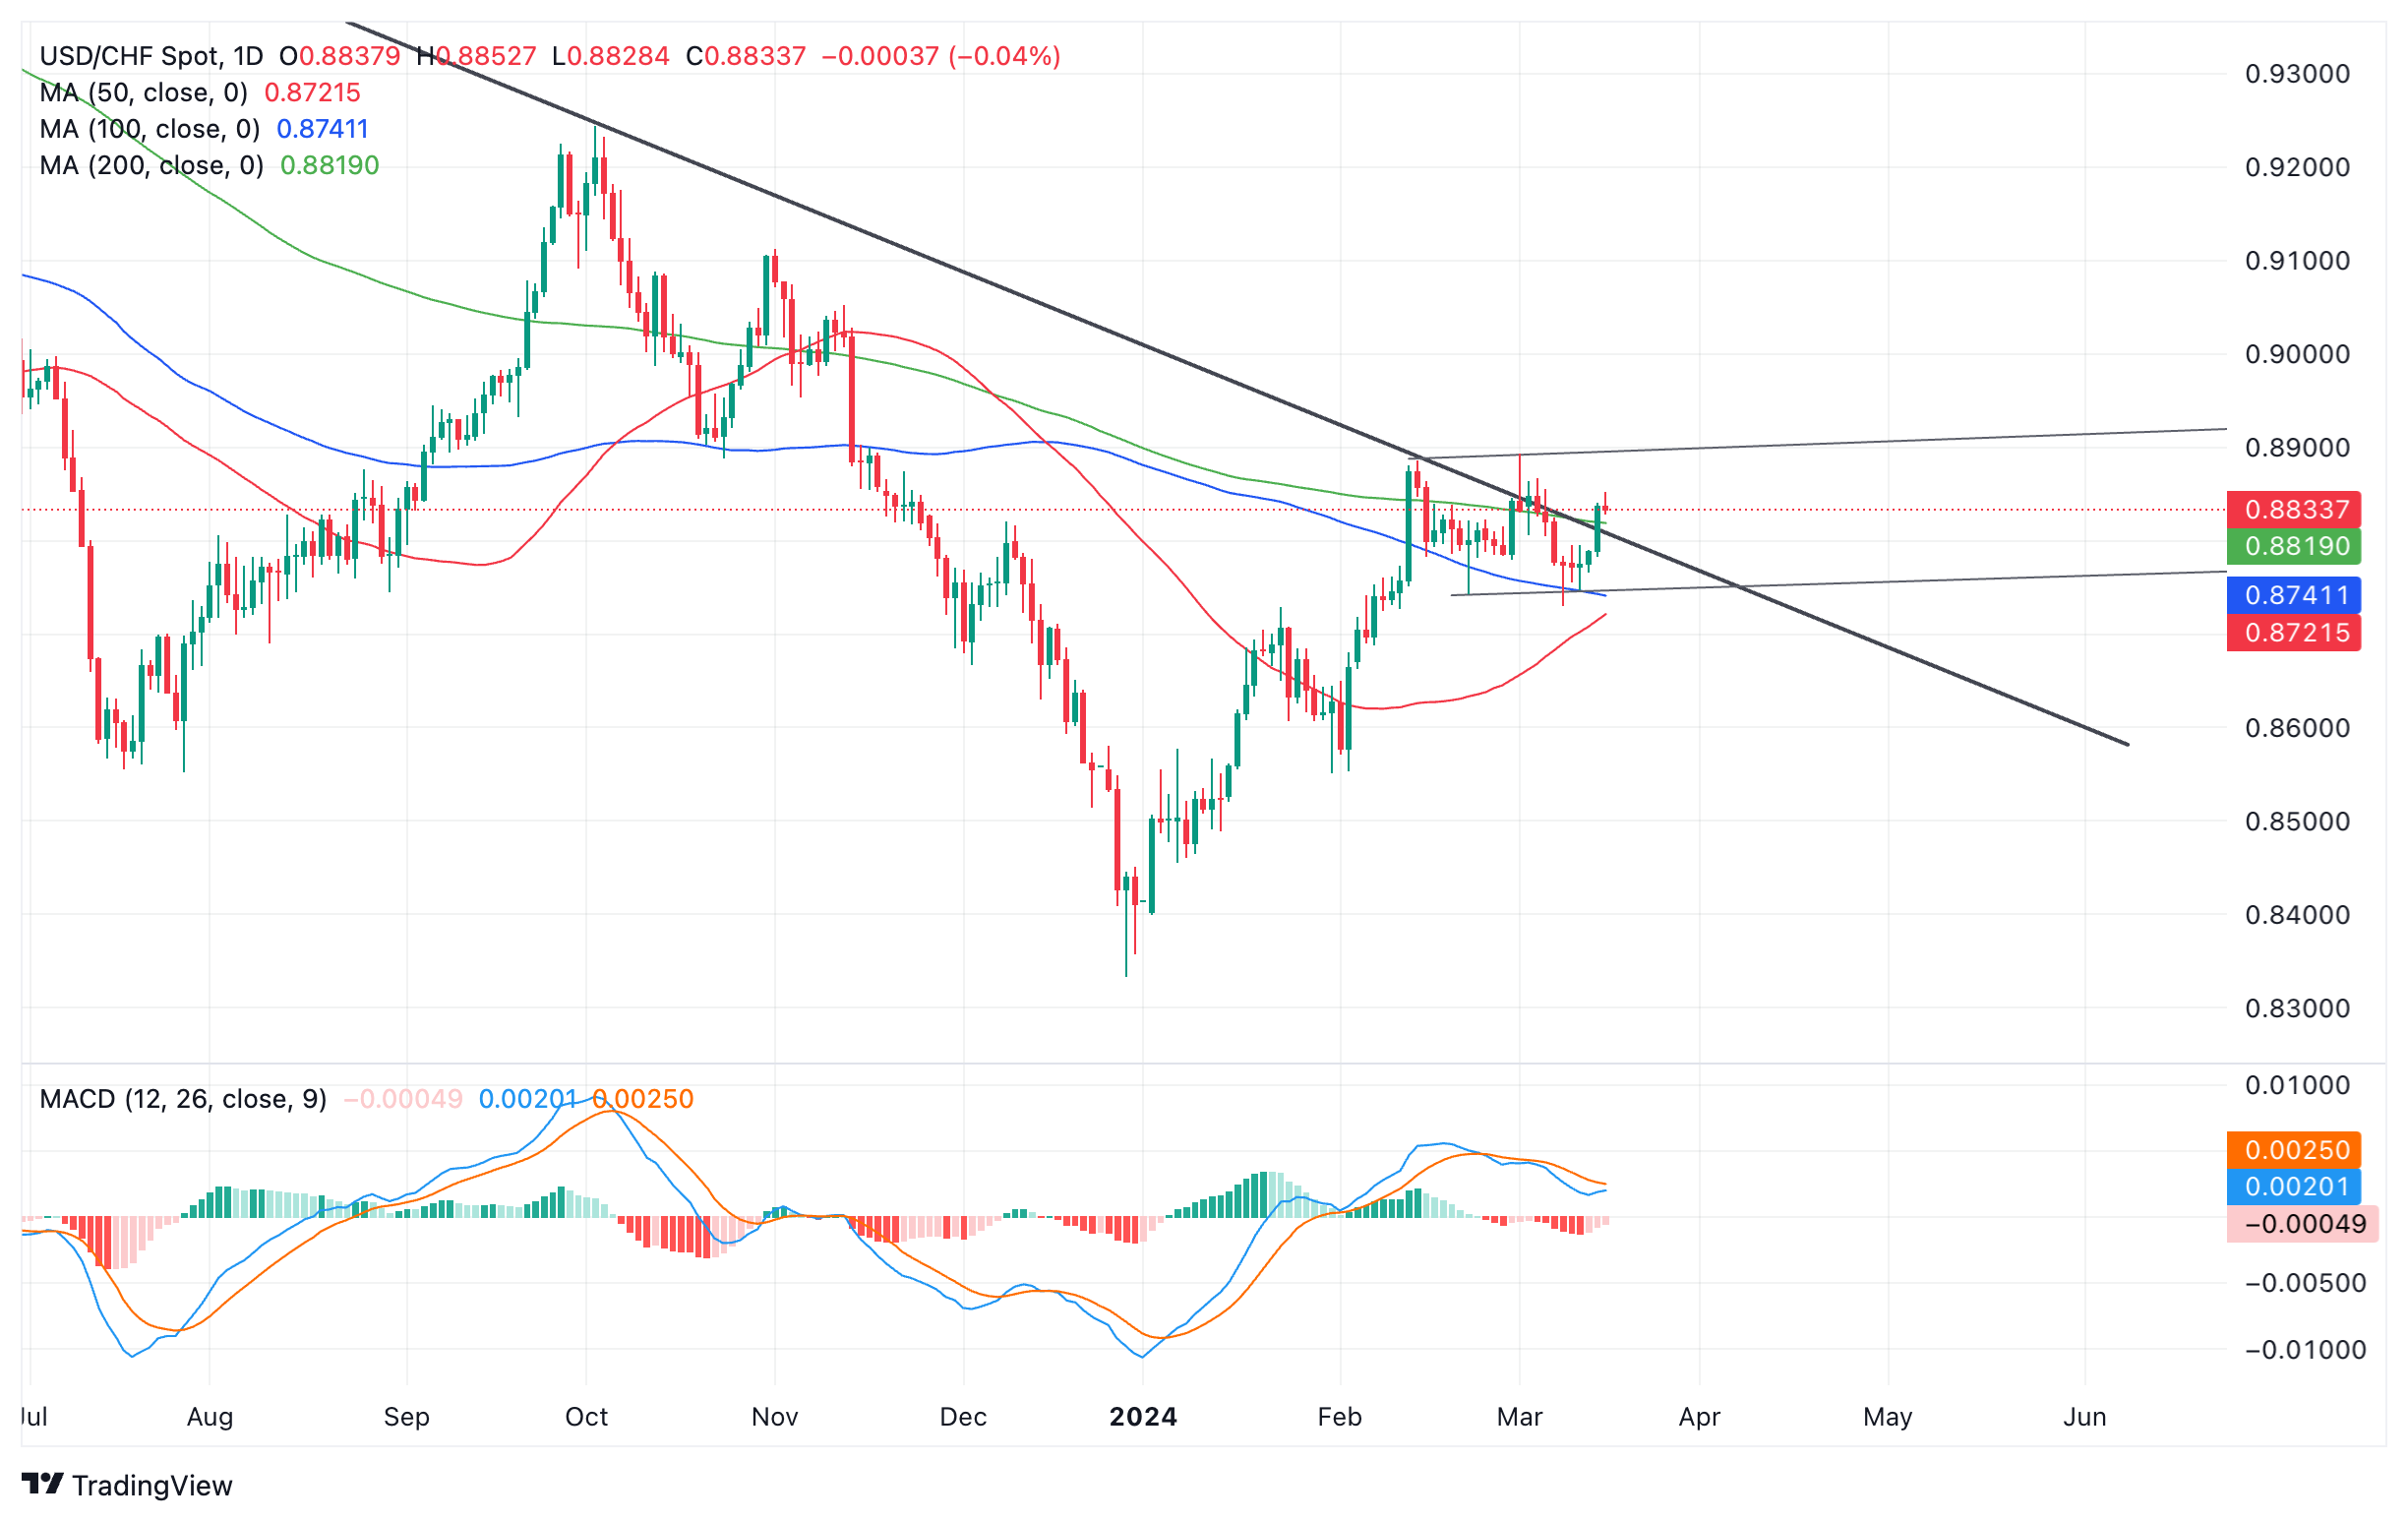
US Dollar versus Swiss Franc: 4-hour chart
For more upside to be confirmed, a decisive break above the range highs at 0.8900 would be required. Such a move would probably then extend to an initial target at 0.8992, the 0.618 Fibonacci ratio of the height of the range extrapolated higher, followed by 0.9052, the full height extrapolated higher.
A decisive break below the range low at 0.8729, however, could indicate a short-term trend reversal and the start of a deeper slide lower. The first target for the move lower would be the 0.618 extrapolation of the height of the range at 0.8632, followed by the full extrapolation at 0.8577, which is also close to the 0.8551 January 31 lows, another key support level to the downside.
SNB FAQs
The Swiss National Bank (SNB) is the country’s central bank. As an independent central bank, its mandate is to ensure price stability in the medium and long term. To ensure price stability, the SNB aims to maintain appropriate monetary conditions, which are determined by the interest rate level and exchange rates. For the SNB, price stability means a rise in the Swiss Consumer Price Index (CPI) of less than 2% per year.
The Swiss National Bank (SNB) Governing Board decides the appropriate level of its policy rate according to its price stability objective. When inflation is above target or forecasted to be above target in the foreseeable future, the bank will attempt to tame excessive price growth by raising its policy rate. Higher interest rates are generally positive for the Swiss Franc (CHF) as they lead to higher yields, making the country a more attractive place for investors. On the contrary, lower interest rates tend to weaken CHF.
Yes. The Swiss National Bank (SNB) has regularly intervened in the foreign exchange market in order to avoid the Swiss Franc (CHF) appreciating too much against other currencies. A strong CHF hurts the competitiveness of the country’s powerful export sector. Between 2011 and 2015, the SNB implemented a peg to the Euro to limit the CHF advance against it. The bank intervenes in the market using its hefty foreign exchange reserves, usually by buying foreign currencies such as the US Dollar or the Euro. During episodes of high inflation, particularly due to energy, the SNB refrains from intervening markets as a strong CHF makes energy imports cheaper, cushioning the price shock for Swiss households and businesses.
The SNB meets once a quarter – in March, June, September and December – to conduct its monetary policy assessment. Each of these assessments results in a monetary policy decision and the publication of a medium-term inflation forecast.
Author

Joaquin Monfort
FXStreet
Joaquin Monfort is a financial writer and analyst with over 10 years experience writing about financial markets and alt data. He holds a degree in Anthropology from London University and a Diploma in Technical analysis.

















