Mexican Peso posts solid session, capitalize on soft US PMIs ahead of inflation data

Most recent article: Mexican Peso declines amid mixed inflation data, strong US economic report
- Mexican Peso capitalized on weaker-than-expected US economic output, uptick in risk appetite.
- Upcoming mid-month inflation data in Mexico could impact Banxico's rate decisions, with expectations leaning toward easing policy.
- The Citibanamex poll shows analysts expect Banxico to hold rates unchanged in May but could resume its easing cycle in June.
The Mexican Peso stages a comeback and rallies against the US Dollar in early trading during Tuesday’s North American session. Weaker-than-expected economic data from the United States (US) and an improvement in risk appetite kept the Greenback pressured as geopolitical woes temper. The USD/MXN trades at 16.99, clocks losses of 0.81%.
Mexico’s economic docket revealed on Monday that economic activity in February 2024 improved, though it failed to boost the Peso. Traders are expecting the release of mid-month inflation figures for April, with core inflation expected to dip further, while the headline Consumer Price Index (CPI) is foreseen remaining unchanged. If the disinflation process shows signs of evolving, that could influence the Bank of Mexico (Banxico) to continue to cut rates, which remain elevated at 11.00%.
The Citibanamex Poll released on Monday suggests that most analysts expect Banxico to keep rates unchanged at the May monetary policy meeting. The consensus expects a rate cut for the June meeting, while the median estimate calls for the main reference rate to end at 10.00%, up from 9.63% previously.
Across the border, S&P Global revealed that business activity in the US edged lower, an indication that the economy is slowing down amid higher interest rates set by the Federal Reserve.
Daily digest market movers: Mexican Peso rescued by softer US S&P PMIs
- Banxico’s Governor Victoria Rodriguez Ceja said that service inflation is not slowing as expected. She added that the Peso‘s strength has helped to temper inflationary pressures and lower imported goods. She emphasized that Banxico would remain data-dependent.
- Mexico’s March inflation figures showed that the CPI was 4.48% and 4.69% for core YoY. On a monthly basis, the CPI was 0.27% and 0.33%, respectively.
- On Monday, the National Statistics Agency (INEGI) revealed that Economic Activity rose 1.4% MoM and 4.4% YoY in the second month of the year compared to January’s 0.9% and 1.9% increases, respectively.
- Last week, the International Monetary Fund (IMF) updated its economic growth projections for Mexico, reducing the 2024 growth forecast from 2.7% to 2.4% and the 2025 forecast from 1.5% to 1.4%.
- S&P Global revealed that the US Manufacturing PMI was 49.9, below the estimates of 52, while the Services index stood at 50.9, down from the 52 expected. Therefore, the Composite PMI was down from 52.1 to 50.9.
- Market participants had priced out an interest rate cut by the Fed in June and July, sparked by hawkish comments expressed by Fed officials last week.
- Data from the Chicago Board of Trade (CBOT) suggests that traders expect fed funds rate to finish 2024 at 4.965%, down from 4.985% on Monday.
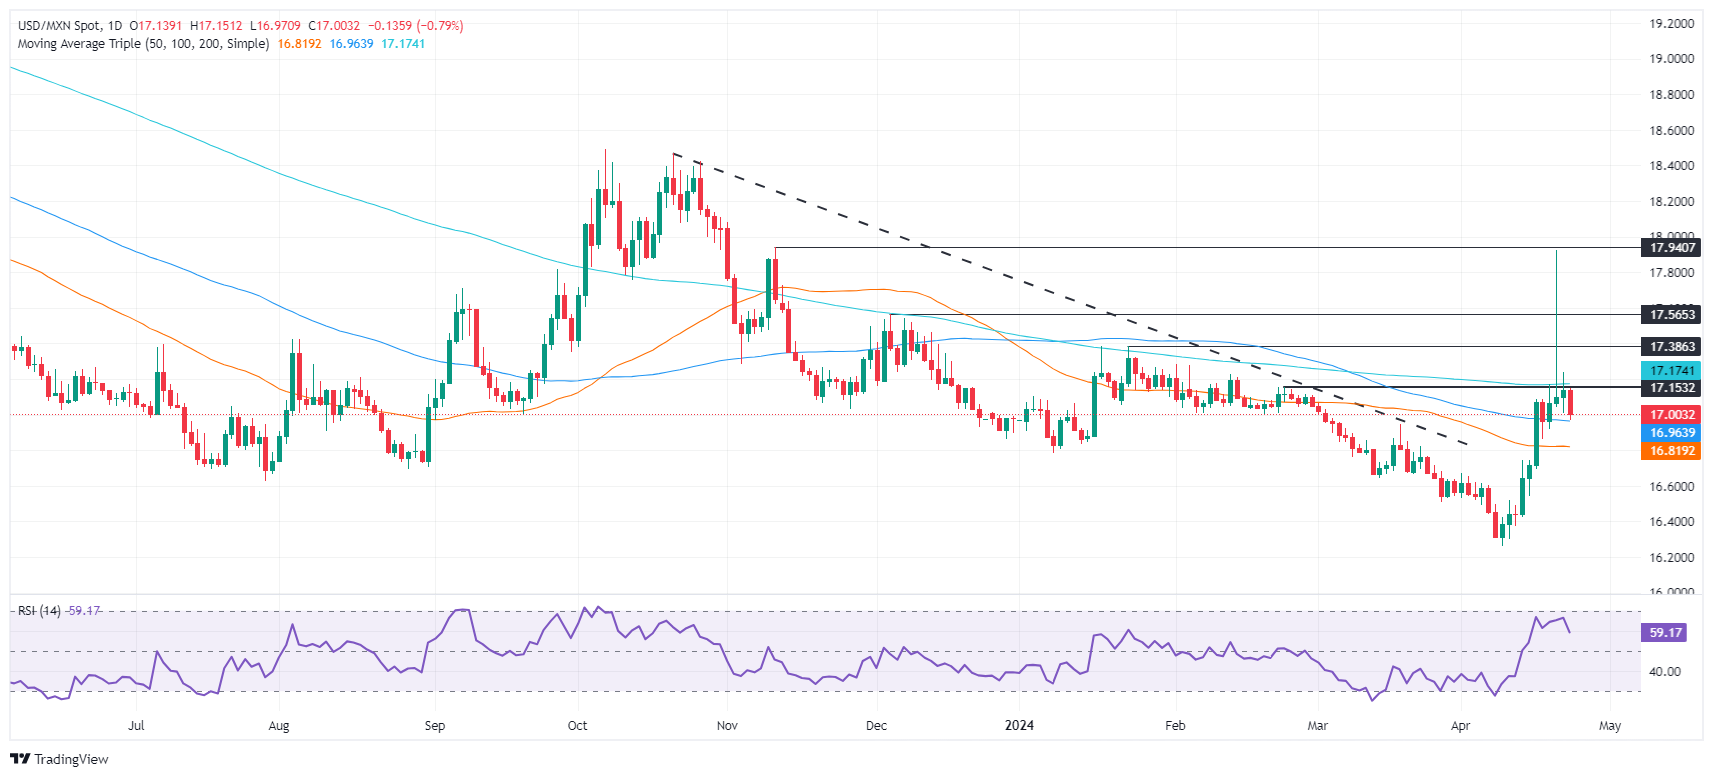
Technical analysis: Mexican Peso counterattacks as USD/MXN tumbles below 200-day SMA
The Mexican Peso regained its previous strength as shown by the USD/MXN edging below the 200-day Simple Moving Average (SMA) at 17.16, opening the door to challenge the 17.00 figure. If sellers push the exchange rate below the latter, they could test the 100-day SMA at 16.96. A breach of the latter will expose the 50-day SMA at 16.81.
On the other hand, buyers need to conquer the 200-day SMA at 17.16. Once surpassed, the next resistance level would be the January 23 high at 17.38, followed by December 5’s 17.56 and the 18.00 figure.
USD/MXN Price Action – Daily Chart
Mexican Peso FAQs
The Mexican Peso (MXN) is the most traded currency among its Latin American peers. Its value is broadly determined by the performance of the Mexican economy, the country’s central bank’s policy, the amount of foreign investment in the country and even the levels of remittances sent by Mexicans who live abroad, particularly in the United States. Geopolitical trends can also move MXN: for example, the process of nearshoring – or the decision by some firms to relocate manufacturing capacity and supply chains closer to their home countries – is also seen as a catalyst for the Mexican currency as the country is considered a key manufacturing hub in the American continent. Another catalyst for MXN is Oil prices as Mexico is a key exporter of the commodity.
The main objective of Mexico’s central bank, also known as Banxico, is to maintain inflation at low and stable levels (at or close to its target of 3%, the midpoint in a tolerance band of between 2% and 4%). To this end, the bank sets an appropriate level of interest rates. When inflation is too high, Banxico will attempt to tame it by raising interest rates, making it more expensive for households and businesses to borrow money, thus cooling demand and the overall economy. Higher interest rates are generally positive for the Mexican Peso (MXN) as they lead to higher yields, making the country a more attractive place for investors. On the contrary, lower interest rates tend to weaken MXN.
Macroeconomic data releases are key to assess the state of the economy and can have an impact on the Mexican Peso (MXN) valuation. A strong Mexican economy, based on high economic growth, low unemployment and high confidence is good for MXN. Not only does it attract more foreign investment but it may encourage the Bank of Mexico (Banxico) to increase interest rates, particularly if this strength comes together with elevated inflation. However, if economic data is weak, MXN is likely to depreciate.
As an emerging-market currency, the Mexican Peso (MXN) tends to strive during risk-on periods, or when investors perceive that broader market risks are low and thus are eager to engage with investments that carry a higher risk. Conversely, MXN tends to weaken at times of market turbulence or economic uncertainty as investors tend to sell higher-risk assets and flee to the more-stable safe havens.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















