|

EUR/USD bulls come up for their last breath?

  • EUR/USD holds within familiar ranges following the Fed taper announcement. 
  • Fed statement inline with expectations, yet transitory language a touch more hawkish.
  • All eyes on Powell's presser, the Fed Dec meeting, US data and how hawkish the ECB will be.  

EUR/USD was trading around 1.1600 throughout the Federal Reserve event on Wednesday. The outcome was more or less in line with the market's expectations but the Fed has acknowledged in a tweak in its statement that inflation might not be as transitory as expected. 

 Nevertheless, the price made a fresh high during the chairman's presser, touching 1.1616 at the time of writing as Powell attempts to dial down inflation risks. The range, so far today, has been between 1.1562 and 1.1616. 

Fed statement takeaways

A taper announcement was made, something that was well telegraphed in prior Fed communications. In the statement, it maintained the transitory language but changed the wording, from ''reflecting transitory factors'' to, ''factors that are expected to be transitory'':
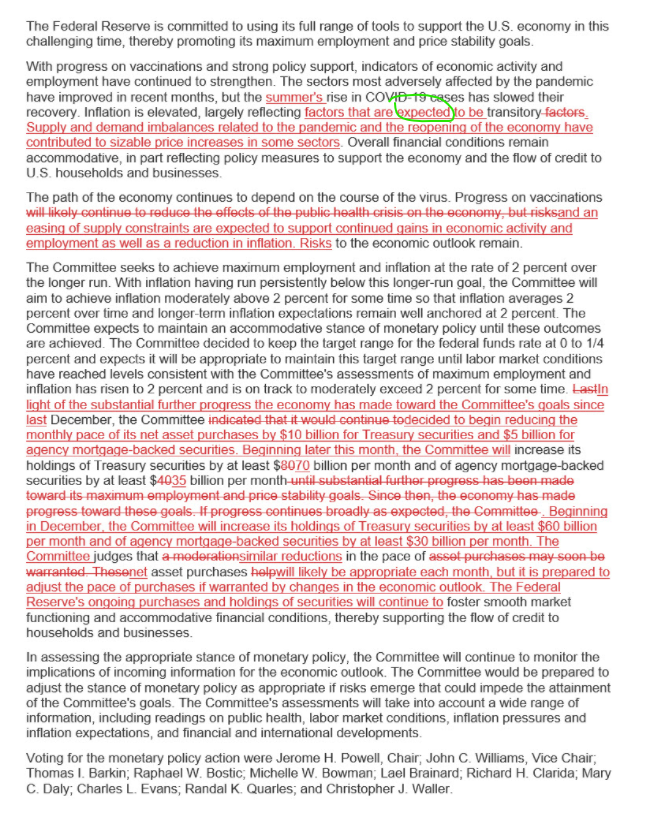
  • Tapering starting November, with monthly reductions of $15 bln.
  • Prepared to adjust taper pace ‘as warranted’.
  • Interest rate decision actual: 0.25% vs 0.25% previous; est 0.25%.

Fed's chair, Powell's presser

Powell is emphasising that the US is not at maximum employment and he has tried to water down the market's take on the tweak to the 'transitory' verbiage in the statement. The US dollar was sent on the backfoot following his reasoning but overall, the markets are steady and will very quickly move to a focus on US data with the Nonfarm Payrolls just around the corner. 

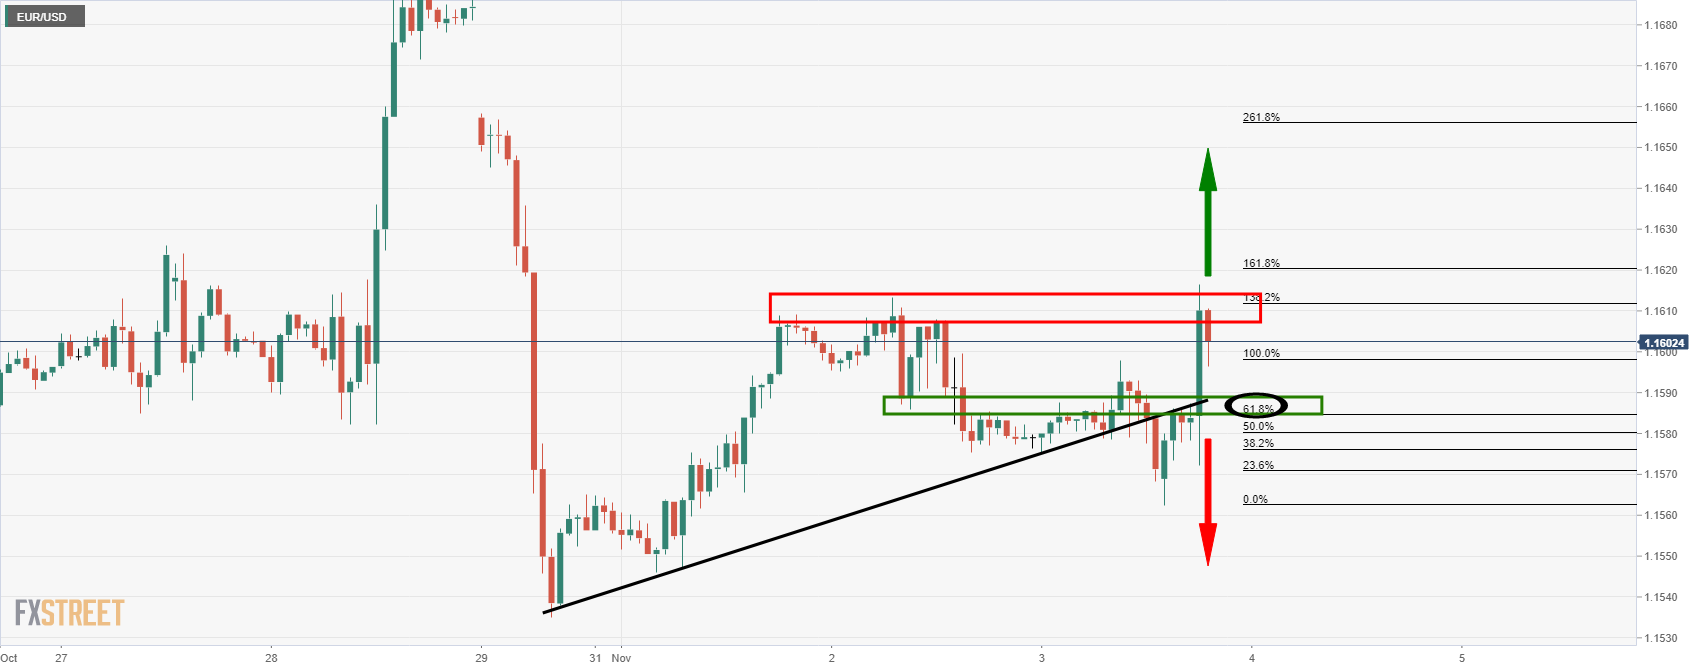
EUR/USD H1 chart

From a technical standpoint, the downside is still vulnerable so long as the price stays within the confines of recent ranges as follows:
Author

Ross J Burland

Ross J Burland, born in England, UK, is a sportsman at heart. He played Rugby and Judo for his county, Kent and the South East of England Rugby team.


More from Ross J Burland
Share:

Editor's Picks

AUD/USD sits near a one-month top, above 0.7000 amid fresh USD selling

AUD/USD holds above 0.7000 through the Asian session, trading near a one-month high touched earlier this Monday amid renewed US Dollar selling. US bond yields decline further amid a modest pullback in crude oil prices, capping the USD recovery from a three-week low. Moreover, bets for a November RBA rate hike support the Aussie, though upside seems capped ahead of the crucial two-day FOMC meeting, starting Tuesday.

USD/JPY struggles below 157.00 on weak USD; holds above one-month low ahead of Fed, BoJ meetings

USD/JPY attracts fresh sellers during the Asian session on Monday, stalling its recovery from the lowest level since September 18, touched Friday as a further decline in US bond yields weighs on the US Dollar. Meanwhile, the Japanese Yen benefits from a more hawkish BoJ, further weighing on the currency pair. The downside, however, seems limited as traders keenly await Fed and BoJ policy meetings later this week.

Gold rebounds from three-month low and retakes $4,000 on weak USD; focus remains on FOMC

Gold attracts some buyers, moving back above the $4,000 psychological mark during the Asian session amid a broadly weaker US Dollar. US President Donald Trump has ruled out immediate military action against Iran, triggering a modest pullback in crude oil prices. Furthermore, Federal Reserve officials have signaled no urgency to raise interest rates immediately.

Cardano's derivatives and on-chain data confirm bears in control

Cardano extends losses, trading below $0.202 after three consecutive weeks of more than 20% declines since early October. Selling pressure continues to build as weakening derivatives metrics, bearish on-chain signals and a deteriorating technical outlook point to further downside risks. Derivatives data shows a bearish bias for Cardano.

CFTC Report: WTI rally runs ahead of positioning
The week in one sentence: WTI prices surged while speculative longs were cut in the week to October 20, creating the clearest price/positioning divergence. Sterling and the Canadian Dollar led the constructive currency shift, while Yen longs also rebuilt. Speculators turned less constructive on the WTI, reducing their net exposure to around 89.3K contracts.
What November 3 means for the Fed's rate path and the US Dollar

The USD faces a decisive period ahead of the November 3 midterm elections. While markets anticipate another interest rate increase from the Fed in December, the battle for control of Congress could reshape fiscal policy expectations and, indirectly, the path of US monetary policy in 2027.















