BoJ’s Ueda: Accommodative financial conditions will be maintained for time being
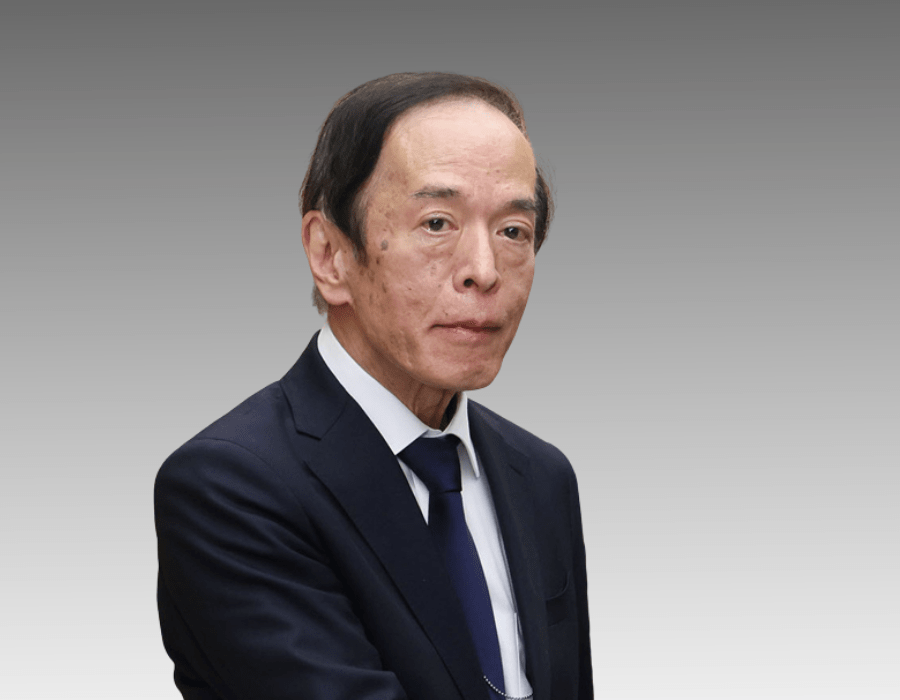
The Bank of Japan (BoJ) Governor Kazuo Ueda stated in his Semiannual Report on Currency and Monetary Control on Wednesday that, given the current perspective for economic activity and prices, it expects accommodative financial conditions to be maintained for the time being.
Key quotes
“Now within sight that the price stability target of 2 percent would be achieved in a sustainable and stable manner toward the end of the projection period of the January 2024 Outlook Report, as various data and anecdotal information from firms had gradually shown that the virtuous cycle between wages and prices had become more solid.”
“On this basis, the Bank considered that the policy framework of Quantitative and Qualitative Monetary Easing (QQE) with Yield Curve Control and the negative interest rate policy to date had fulfilled their roles, and it therefore changed the monetary policy framework.”
“Specifically, the Bank decided, among other measures, to set the uncollateralized overnight call rate as the policy interest rate and encourage that rate to remain at around 0 to 0.1 percent.”
“Given the current outlook for economic activity and prices, it anticipates that accommodative financial conditions will be maintained for the time being.”"Trend inflation yet to reach 2%, so need to support economy's momentum toward hitting 2% by maintaining accommodative monetary conditions."
"Want to scrutinise whether trend inflation will indeed head toward 2% in judging appropriate degree of monetary support."
"Waiting to exit until trend inflation hits 2% would have heightened risk of inflation overshoot, force us to hike rates aggressively."
"We won't change monetary policy just to deal directly with FX moves."
"We might need to change monetary policy if fx moves lead not just to rising import prices, but risk pushing up trend inflation more than expected."
"We want the Japanese Government Bond (JGB) market to eventually return to a state where yields are set by market prices."
"We are now observing how the markets absorb the March policy shift, after which we hope to begin reducing the size of our JGB buying."
"Japan's prolonged deflation, low inflation made it difficult to affect public's inflation expectations via expansion of monetary base."
Market reaction
The USD/JPY pair is trading at 151.70, losing 0.04% on the day at the time of writing.
Bank of Japan FAQs
The Bank of Japan (BoJ) is the Japanese central bank, which sets monetary policy in the country. Its mandate is to issue banknotes and carry out currency and monetary control to ensure price stability, which means an inflation target of around 2%.
The Bank of Japan has embarked in an ultra-loose monetary policy since 2013 in order to stimulate the economy and fuel inflation amid a low-inflationary environment. The bank’s policy is based on Quantitative and Qualitative Easing (QQE), or printing notes to buy assets such as government or corporate bonds to provide liquidity. In 2016, the bank doubled down on its strategy and further loosened policy by first introducing negative interest rates and then directly controlling the yield of its 10-year government bonds.
The Bank’s massive stimulus has caused the Yen to depreciate against its main currency peers. This process has exacerbated more recently due to an increasing policy divergence between the Bank of Japan and other main central banks, which have opted to increase interest rates sharply to fight decades-high levels of inflation. The BoJ’s policy of holding down rates has led to a widening differential with other currencies, dragging down the value of the Yen.
A weaker Yen and the spike in global energy prices have led to an increase in Japanese inflation, which has exceeded the BoJ’s 2% target. Still, the Bank judges that the sustainable and stable achievement of the 2% target has not yet come in sight, so any sudden change in the current policy looks unlikely.
Author

Lallalit Srijandorn
FXStreet
Lallalit Srijandorn is a Parisian at heart. She has lived in France since 2019 and now becomes a digital entrepreneur based in Paris and Bangkok.