AUD/USD: Why has the Australian Dollar weakened so much despite amazing jobs data?
- AUD/USD pitches back down to the base of its range after US data eclipses Aussie employment figures.
- The rapid reversal is surprising since the Australian data was stellar whilst the US data was unremarkable.
- A deeper analysis of the Australian jobs data might reveal why its upside influence was so ephemeral.

AUD/USD is trading back down at the bottom or its multi-week range in the lower 0.6500s on Friday, after positive US data led to a reversal in the pair from its 0.6634 Thursday highs.
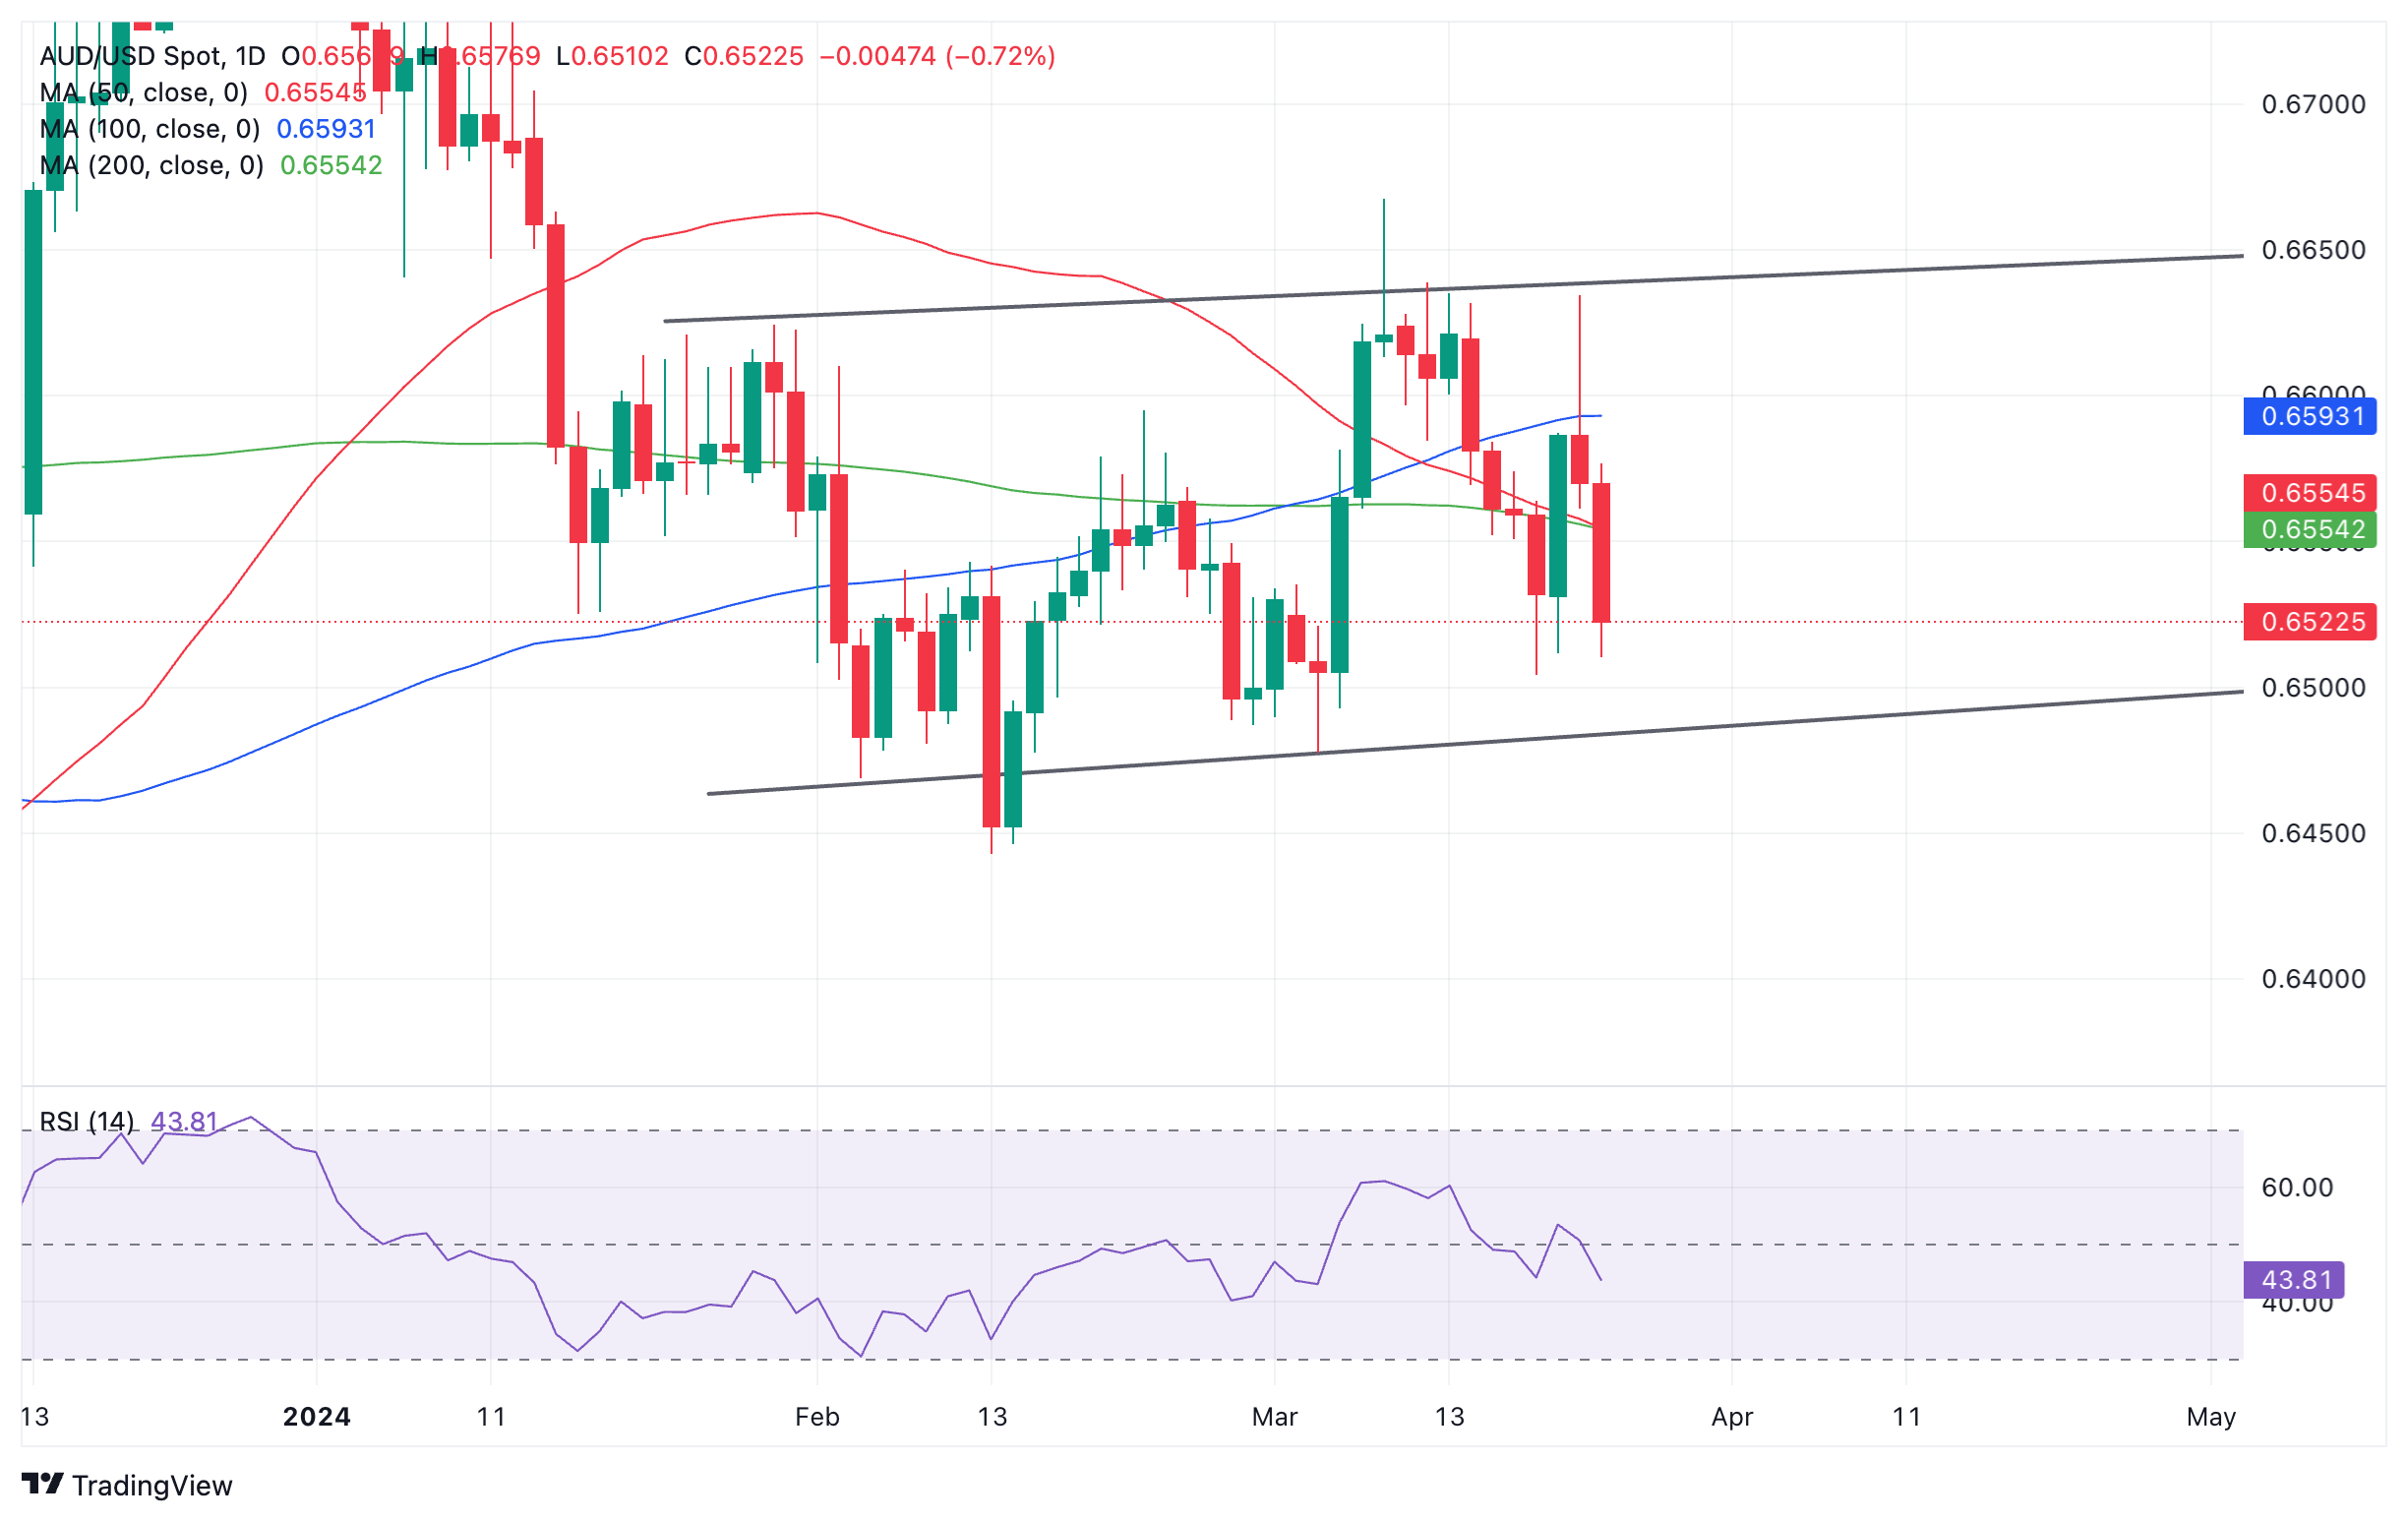
Australian Dollar versus US Dollar: Daily chart
Although the US data was positive it was not remarkable. When compared to the Australian employment data that preceded it and led to such a strong surge higher in the AUD/USD on Thursday morning, it could be said to be at best mediocre.
How is it, then, that in the case of the AUD/USD pair, the US data led to such a sharp reversal lower?
US data downs the Aussie
A look at the US data in detail only intensifies the mystery further. The S&P Global US Composite PMI actually came out lower in March than the previous month, and Services PMI undershot expectations.
Whilst Manufacturing PMI beat expectations at 52.7 – making the US one of the few developed countries with an expansionary Manufacturing sector – the data hardly warranted the strong move up in the US Dollar (USD).
Granted, the other releases at the time – Initial Jobless Claims and the Philadelphia Fed Manufacturing Index – also painted a positive picture of the state of the US economy, these are still considered only at best rather minor data points.
Australian employment – a true renaissance?
Australian employment data, on the other hand, released a few hours before the US data came out, appeared at least on the surface stellar by comparison.
The Unemployment Rate fell to 3.7% from 4.1% in February, and the number of new employees hit 116,500, a number well above the average. Both data points beat expectations of 4.0% and 40,000 respectively.
A deeper dig into Australia’s labor market statistics and seasonal effects, however, suggests the incredible data in February obscured a much more modest underlying trend.
The Unemployment Rate, for example, may have fallen sharply in february but it was “around where it had been six months earlier,” according to Bjorn Davis, head of Statistics at ABS.
In terms of the unusually high Employment Change figure of 116.5K, Davis says this smooths out to a much more modest level when taken alongside the 62,000 fall in employed people in December and weaker-than-usual 15,000 rise in January. Taking the three months losses and gains together smooths the overall three-month change to a more modest 70,000 more people employed overall in February, compared to November 2023.
The data shows a lag effect because a larger-than-average number of people were waiting to start a job in December and January, that they subsequently went on to begin in February, boosting that month’s statistics.
That said, that data was still better than usual. The increase in people working from January to February was still above average, according to Davis.
“In 2022 and 2023, around 4.3 percent of employed people in February had not been employed in January. In 2024, this was higher, at 4.7 percent, and well above the pre-pandemic average for 2015 to 2020 of around 3.9 percent."
Nevertheless, a deeper understanding of the underlying statistics of February’s Australian employment release goes some way to explaining why the reaction in the Australian Dollar was a) not stronger, and b) so easily toppled by subsequent mediocre US data.
Author

Joaquin Monfort
FXStreet
Joaquin Monfort is a financial writer and analyst with over 10 years experience writing about financial markets and alt data. He holds a degree in Anthropology from London University and a Diploma in Technical analysis.

















