Gold price consolidates and prints weekly losses after US inflation data
- Gold sees partial retreat reacting to unexpectedly high US producer inflation and strengthening US Dollar.
- US Treasury yields and Dollar Index rise, reflecting a market reassessment of Federal Reserve's monetary policy.
- Retail Sales and Initial Jobless Claims data underscore US economic resilience, weighing on Gold's intraday prices.

Gold prices trimmed some of their Wednesday gains on Thursday after traders began to price in a less “dovish” Federal Reserve following a hotter-than-expected Producer Price Index (PPI) report. Consequently, US Treasury bond yields rose, underpinning the US Dollar. At the time of writing, XAU/USD exchanges hands at around $2,160.00 and gains 0.50%.
US equities finished the session with losses. Earlier, the US Department of Labor announced that a measure of inflation on the producer side jumped. At the same time, US Retail Sales showed that consumers remained resilient, while people filing for unemployment insurance decreased below the previous reading and estimates.
Uncertainty about the US central bank policy prospects prompted investors to trim their bets that the Fed would cut rates at the June meeting. In the meantime, the yellow metal treads water as the US 10-year Treasury bond yield surges ten basis points from 4.19% to 4.29%, while The US Dollar Index (DXY), a gauge of the buck’s performance versus other currencies, climbs 0.54% to 103.33.
Daily digest market movers: Gold traders on the defensive amid strong USD
- The PPI was strong, at 1.6% YoY, up from 0.9%, while the core PPI stood at 2%, unchanged, with both figures exceeding the consensus.
- The US Department of Commerce revealed that Retail Sales missed estimates of 0.8% MoM and rose 0.6%, still an improvement compared to the prior month’s reading of -1.1%.
- The labor market remained tight as Initial Jobless Claims for the week ending March 9 dipped from 210K to 209K, below estimates of 218K.
- Given the backdrop of consumer and producer price indices in the US showcasing reaccelerating inflation, Fed officials should refrain from easing monetary policy.
- During last week's testimony at the US Congress, Fed Chairman Jerome Powell said that inflation is cooling while acknowledging that they could ease policy late in the year. However, he emphasized that it would depend on incoming data reassuring policymakers that inflation is sustainably moving toward the Fed’s 2% goal. The Fed’s next meeting is scheduled for March 19-20 next week.
- According to the CME FedWatch Tool, expectations for a May rate cut remain low, having dropped to 11% from 22%. However, the odds for June stand at 64%, down from 72%.
Technical analysis: Gold buyers take a breather below $2,170.00
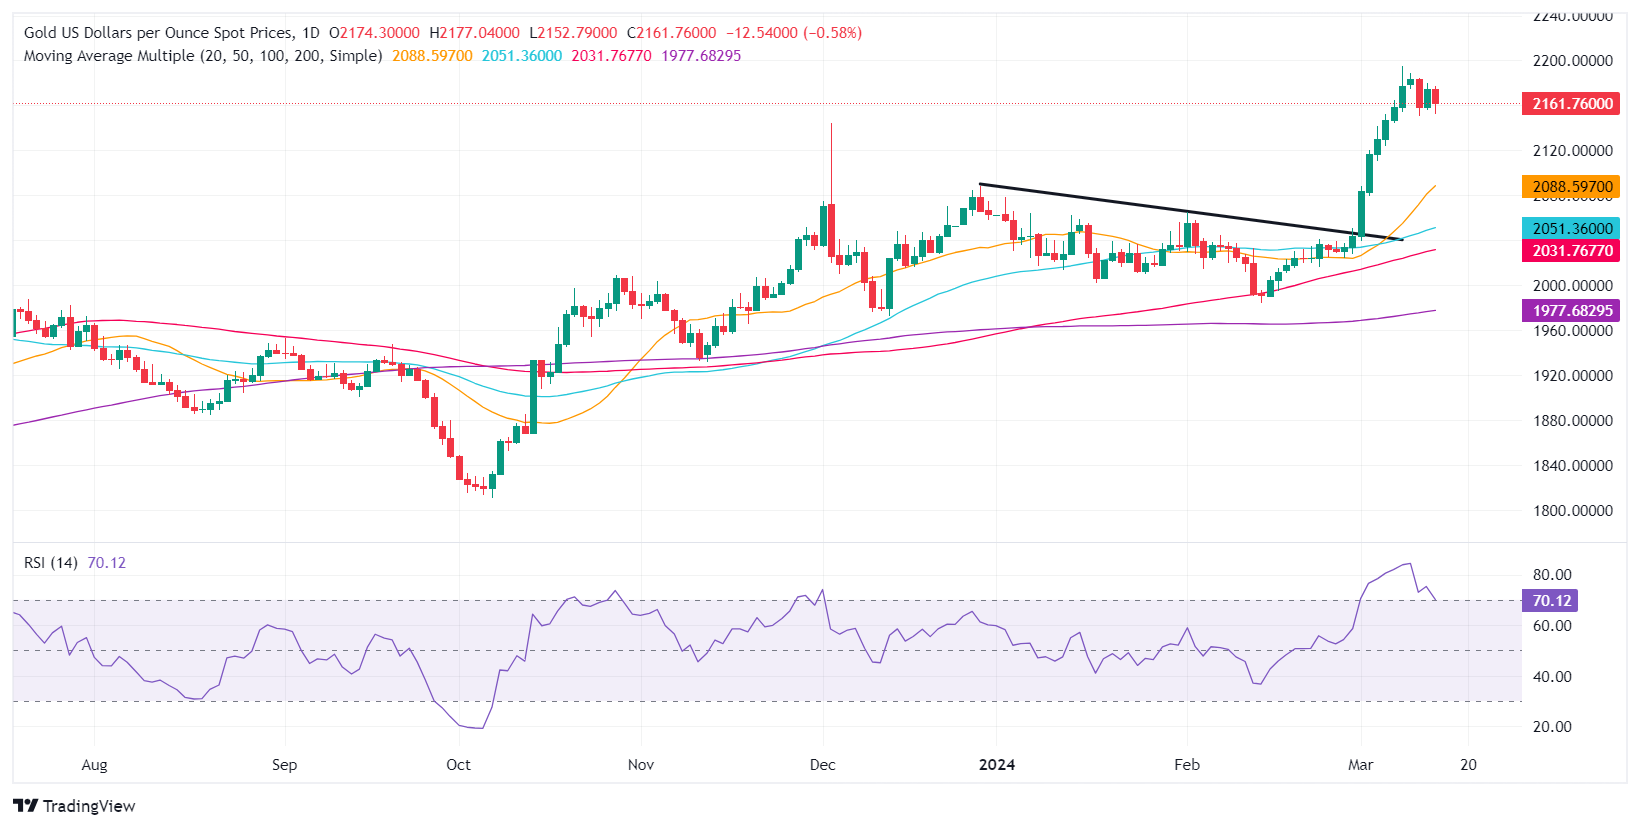
Gold price remains upwardly biased on Thursday, but it has consolidated near the $2,160-$2,180 area during the last three days, unable to break the top of the range and aim toward $2,200.00. It should be said that the Relative Strength Index (RSI) indicator is about to pierce below the 70 mark, an indication that buyers are losing momentum. In that event, XAU/US could dive toward $2,150.00.
Further downside is seen at the March 6 low of $2,123.80, followed by $2,100.00. A breach of the latter will expose the December 28 high at $2,088.48 and the February 1 high at $2,065.60.
On the other hand, a bullish continuation would happen once buyers reclaim the March 12 high of $2,184.76. The next stop would be the year-to-date high of $2,195.15, followed by $2,200.00.
Gold FAQs
Gold has played a key role in human’s history as it has been widely used as a store of value and medium of exchange. Currently, apart from its shine and usage for jewelry, the precious metal is widely seen as a safe-haven asset, meaning that it is considered a good investment during turbulent times. Gold is also widely seen as a hedge against inflation and against depreciating currencies as it doesn’t rely on any specific issuer or government.
Central banks are the biggest Gold holders. In their aim to support their currencies in turbulent times, central banks tend to diversify their reserves and buy Gold to improve the perceived strength of the economy and the currency. High Gold reserves can be a source of trust for a country’s solvency. Central banks added 1,136 tonnes of Gold worth around $70 billion to their reserves in 2022, according to data from the World Gold Council. This is the highest yearly purchase since records began. Central banks from emerging economies such as China, India and Turkey are quickly increasing their Gold reserves.
Gold has an inverse correlation with the US Dollar and US Treasuries, which are both major reserve and safe-haven assets. When the Dollar depreciates, Gold tends to rise, enabling investors and central banks to diversify their assets in turbulent times. Gold is also inversely correlated with risk assets. A rally in the stock market tends to weaken Gold price, while sell-offs in riskier markets tend to favor the precious metal.
The price can move due to a wide range of factors. Geopolitical instability or fears of a deep recession can quickly make Gold price escalate due to its safe-haven status. As a yield-less asset, Gold tends to rise with lower interest rates, while higher cost of money usually weighs down on the yellow metal. Still, most moves depend on how the US Dollar (USD) behaves as the asset is priced in dollars (XAU/USD). A strong Dollar tends to keep the price of Gold controlled, whereas a weaker Dollar is likely to push Gold prices up.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















