Gold price soars to unseen highs amid high US yields, unfazed by US jobs data
- Gold hits record highs, defying US Nonfarm Payrolls spike and US Dollar gains, highlighting safe-haven status.
- Fed rate cut outlook adjusted after employment data, central bank remarks.
- Geopolitical tensions and strong demand from China bolster Gold's market strength.
Gold rallied to a new all-time high, ignoring a strong March Nonfarm Payrolls report in the United States (US), which could prevent the Federal Reserve (Fed) from slashing rates sooner than the market expects. In achieving its milestone, the yellow metal ignored the rise in US Treasury yields and the Greenback, which clings to modest gains of 0.09%.
XAU/USD trades at $2,324 after reaching $2,330 earlier in Friday’s North American session. Gold’s price continued to be driven by fundamentals linked to the US Dollar, geopolitical risks and physical demand.
Focusing on data, US Nonfarm Payrolls figures for March crushed estimates and February’s numbers as new hirings rose to 303,000. Consequently, the Unemployment Rate fell, while Average Hourly Earnings were mixed, rising on monthly figures but diving on an annual basis.
Following the data, bets that the Fed would cut rates in June fell further, from around 70% a week ago to 53.4%, according to the CME FedWatch Tool.
The employment report reinforced Fed Chair Jerome Powell’s words on Wednesday. He said they’re in no rush to cut rates, and his words echoed throughout the week. On Friday, officials crossed the wires led by Richmond’s Fed Barkin, Dallas Fed Logan and Governor Bowman.
Daily digest market movers: Gold underpinned by strong physical demand, ignores US data
- US Department of Labor announces that Nonfarm Payrolls increased by 303,000 in March, higher than the anticipated 200,000 and the previous 270,000.
- Further details revealed that the Unemployment Rate decreased modestly to 3.8% from 3.9%, with Average Hourly Earnings meeting consensus predictions. Average Hourly Earnings rose by 0.3% MoM, up from 0.2%. In the twelve months to March, earnings rose by 4.1% as expected, down from 4.3%.
- Following these figures, the US Dollar strengthened, evidenced by a 0.15% rise in the US Dollar Index (DXY) to 104.36. US Treasury bond yields increased by about 5 basis points, with the 10-year rate reaching 4.365%.
- Recently, Fed Governor Michelle Bowman stated that cutting rates too soon risks a rebound in inflation. She said that eventually, the bank would cut rates, yet inflationary risks are tilted to the upside. Earlier, Richmond Fed President Thomas Barkin described the NFP report as robust but noted that inflation reduction has been inconsistent.
- Dallas Fed President Lorie Logan said there’s “no urgency” to cut borrowing costs, adding the risk of cutting too soon is higher than being late.
- Geopolitical risks loom following Israel’s attack on Iran’s embassy in Syria. Iran pledged to retaliate against Israel after seven officers were killed. A further escalation could pressure Gold prices upward, with traders looking at the $2,350 figure.
- World Gold Consortium reveals that the People’s Bank of China was the largest buyer of the yellow metal, increasing its reserves by 12 tonnes to 2,257 tonnes.
Technical analysis: Gold’s upside set to continue despite RSI’s overbought condition
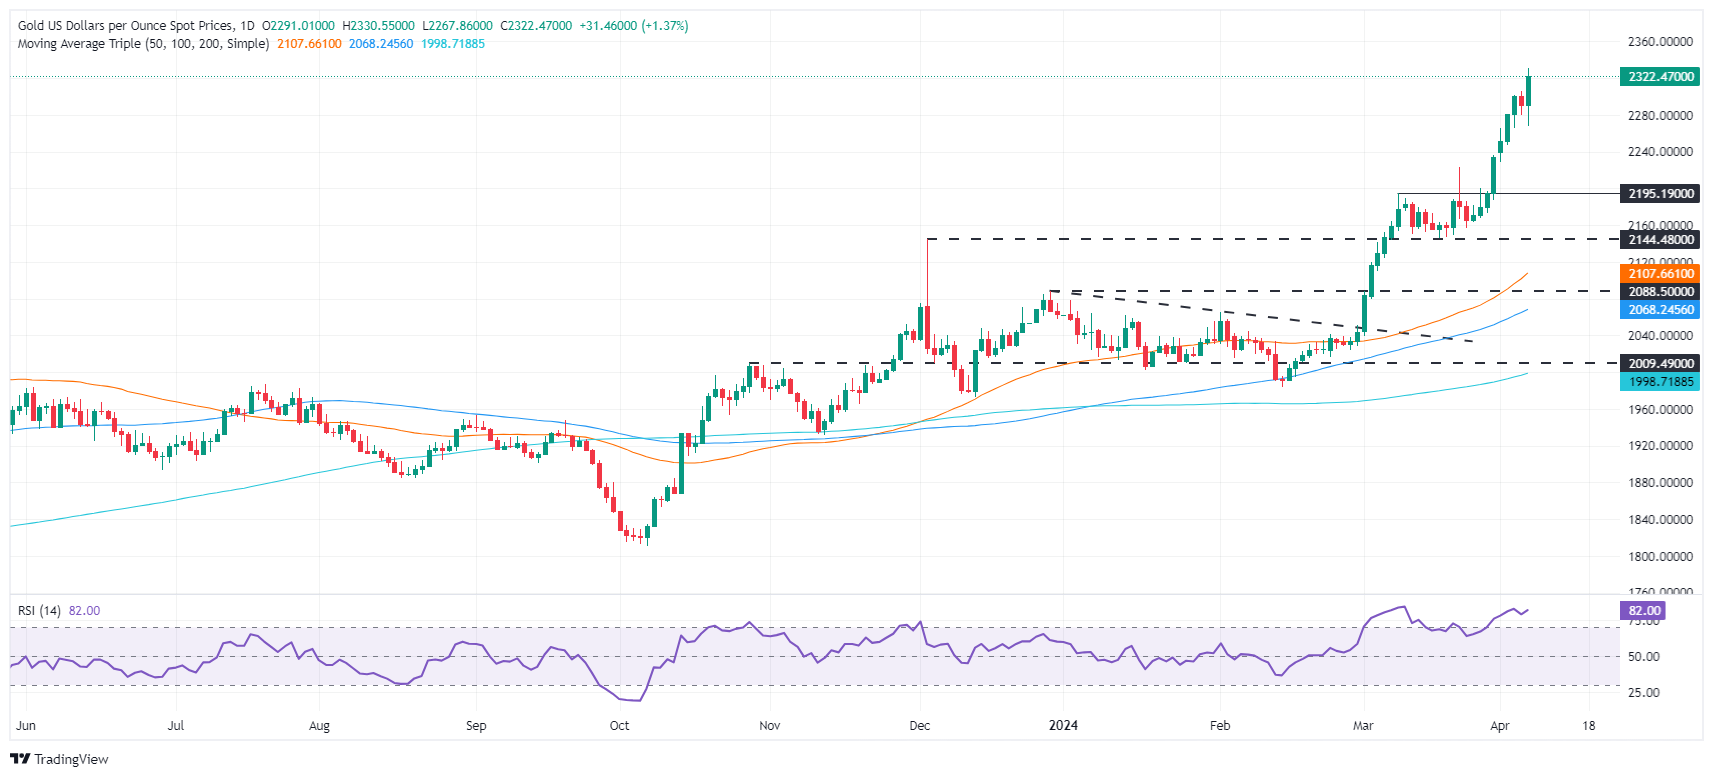
Gold’s rally is set to continue, with buyers gathering momentum. The Relative Strength Index (RSI), although at overbought conditions past the 70.00 level, aims north. Usually when an asset has a strong uptrend, the 80 reading is seen as the overbought extreme. However, as price action doesn’t show signs of exhaustion, the $2,350 mark is up for grabs.
On the flip side, the first support level would be $2,300. A breach of the latter will expose $2,250, followed by the $2,200 mark.
Gold FAQs
Gold has played a key role in human’s history as it has been widely used as a store of value and medium of exchange. Currently, apart from its shine and usage for jewelry, the precious metal is widely seen as a safe-haven asset, meaning that it is considered a good investment during turbulent times. Gold is also widely seen as a hedge against inflation and against depreciating currencies as it doesn’t rely on any specific issuer or government.
Central banks are the biggest Gold holders. In their aim to support their currencies in turbulent times, central banks tend to diversify their reserves and buy Gold to improve the perceived strength of the economy and the currency. High Gold reserves can be a source of trust for a country’s solvency. Central banks added 1,136 tonnes of Gold worth around $70 billion to their reserves in 2022, according to data from the World Gold Council. This is the highest yearly purchase since records began. Central banks from emerging economies such as China, India and Turkey are quickly increasing their Gold reserves.
Gold has an inverse correlation with the US Dollar and US Treasuries, which are both major reserve and safe-haven assets. When the Dollar depreciates, Gold tends to rise, enabling investors and central banks to diversify their assets in turbulent times. Gold is also inversely correlated with risk assets. A rally in the stock market tends to weaken Gold price, while sell-offs in riskier markets tend to favor the precious metal.
The price can move due to a wide range of factors. Geopolitical instability or fears of a deep recession can quickly make Gold price escalate due to its safe-haven status. As a yield-less asset, Gold tends to rise with lower interest rates, while higher cost of money usually weighs down on the yellow metal. Still, most moves depend on how the US Dollar (USD) behaves as the asset is priced in dollars (XAU/USD). A strong Dollar tends to keep the price of Gold controlled, whereas a weaker Dollar is likely to push Gold prices up.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.
















