US Non-farm Payrolls September Report: The two-tier economy
- Payrolls add 661,000 million jobs, missing the 850,000 forecast.
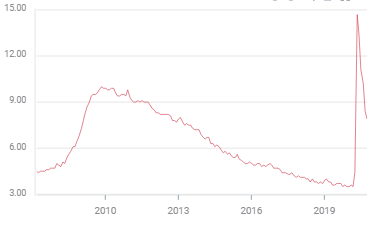
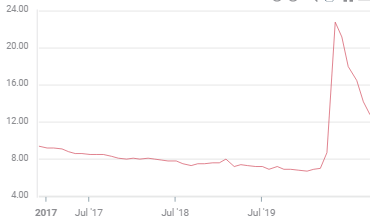
- Unemployment rate improves to 7.9% from 8.4%, underemployment to 12.8% from 14.2%.
- Equities slammed by White House COVID-19 diagnosis, dollar, Treasuries stable.
- Final jobs report before the November 3 election.

American firms stayed in hiring mode in September but the declining pace of restoration is evidence and a warning that that all is not well with the recovery.
Non-farm Payrolls added 661,000 jobs in September and the unemployment rate dropped to 7.9%, reported the Labor Department in the final report before the November 3 election. The August result was revised to 1.489 million from 1.371million.
Non-farm Payrolls
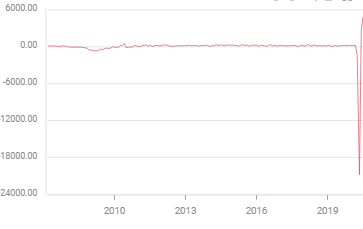
Expectations in the Reuters survey of economists had been for an increase of 850,000 in payrolls and an unemployment rate of 8.2%.
Unemployment Rate, U-3
FXStreet
In the five months since the lockdowns of March and April the US labor market has rehired 11.374 million people, 51.3% of the 22.16 million workers laid-off during the pandemic.
Unemployment has declined even faster in a second more inclusive measure, the so-called underemployment rate which includes discouraged workers and those working part-time because they cannot find full-time employment. This rate dropped to 12.8% from 14.2% in August. It had been predicted to rise to 15.4%. September is the third month in a row that economists have predicted an increase when the rate actually declined.
Underemployment Rate, U-6
The jobless rate for Blacks fell almost twice as fast as the overall percentage, dropping to 12.1% from 13.0%.
Leisure and hospitality, two sectors hard hit by the continuing business restrictions in some places and public reluctance to travel, led jobs gains with 318,000 while retail stores hired 142,000.
Losses were the greatest in government, 216,000, as many localities kept schools closed and 34,000 Census workers were laid-off as the annual population count came to a close.
Markets
Reaction to the payroll report was muted with currencies and Treasury rates barely stirring.
The NFP release was overshadowed by the COVID-19 diagnosis of President Trump and First Lady Melania.
Normally the minor disappointment of an 189,000 miss on payrolls might have been mildly negative for equities, but the more than 400 point decline in Dow Futures before the open and the 170 point drop after 90 minutes of trading was all Trump.
Market interest is now focused on the second stimulus package being negotiated in Congress. Passage is possible but unsure. A new spending deal would aid equities, support the dollar and boost the economy.
It might also affect the election, hence the uncertainty.
Initial Jobless Claims
While payrolls have maintained a steady if diminishing return of workers since the recovery began in May, initial jobless claims have remained stubbornly high. Seven months after the labor market collapsed in March the economy is still firing almost one million workers a week. The four-week moving average for initial claims was 867,250 in the September 25 week.
Unemployment insurance and other federal and local programs have helped maintain consumption but it seems inevitable that the employment situation will begin to affect consumer spending. With 70% of US GDP tied to the consumer the potential damage from the continuing layoffs is high.
Retail Sales
Retail sales have more than recovered from the March and April shutdowns, though purchases slowed in August, adding 0.6 following July’s 0.9% gain.
Including the closures, sales have increased an average of 0.87% per month through August, 5.2% for the period. In a normal economy those numbers would be proof of a healthy consumer backed by a strong job market.
Retail Sales

The expansion of the GDP retail sales component control group is even more impressive. The six-month average is 1.28% and the total is 7.7%.
The May and June rebound in sales was not exceptional, large sections of the US economy were closed in March and April and deferred purchases made up the bulk of those gains.
More telling will be the September and fourth quarter retail figures. If the reductions of July and August are not a return to normal levels of consumption but a trend that continues into the Christmas season the prognosis for the US economy will drop accordingly.
The September Retail Sales numbers will be issued by the Commerce Department on Friday October 16.
Manufacturing PMI
The outlook in the manufacturing sector is positive. The September purchasing managers’ index edged lower to 55.4 from 56 but the outlook is expansionary and back to the range at the beginning of 2019.
New orders beat expectations for the fourth month in a row. The September index was 60.2, August set an all-time record of 67.6, July registered 61.5 and June was 54.1.
Only the employment index continues to lag. Though September’s reading of 49.6 was the best level in 14 months, it is still below the 50 mark for expansion, even if just barely so.
Business mangers seem reluctant to hire despite four exceptionally strong months of new business. The pandemic remains a large factor even in the mostly reopened US economy.
Conclusion
The US is suffering from economic dysphoria. Attitudes and performance in some sectors, manufacturing and retail sales cited above, are at or above levels where they were before the lockdowns wrecked havoc.
The labor market, however, seems increasingly split between the areas that have resumed normal or almost normal functioning represented by the non-farm payrolls survey and those that continue to shed firms and jobs in the initial claims accounting.
The jobless numbers are the strongest evidence that for many millions of workers and many thousands of small business the switch in pandemic prevention from “bend the curve” to “we must find a vaccine to reopen” has been deadly.
The US economy is the American consumer. Twelve million unemployed will eventually, sooner if another support package is not passed by Congress, create a spending hole large enough for the entire economy to fall into.
The recovery cannot be successful until the majority of those unemployed millions are working again.
Author

Joseph Trevisani
FXStreet
Joseph Trevisani began his thirty-year career in the financial markets at Credit Suisse in New York and Singapore where he worked for 12 years as an interbank currency trader and trading desk manager.

















