Pound Sterling struggles to stabilize against US Dollar despite dovish Fed remarks
- The Pound Sterling posts a fresh two-month low to near 1.3280 against the US Dollar.
- Federal Reserve officials have delivered dovish remarks on the monetary policy outlook.
- BoE policymaker Catherine Mann supports higher interest rates for a longer period.
The Pound Sterling (GBP) strives to gain ground against the US Dollar (USD) during Friday's European trading session after posting a fresh two-month low around 1.3280 earlier in the day. The outlook of the GBP/USD pair remains vulnerable as the US Dollar trades firmly, with an increase in its safe-haven demand following political developments in Japan and France.
At the press time, the US Dollar Index (DXY), which tracks the Greenback’s value against six major currencies, clings to gains near a fresh two-month high of 99.56 posted on Thursday.
However, financial market participants remain cautious over the US Dollar’s outlook in the wake of firm expectations that the Federal Reserve (Fed) will cut interest rates again in both monetary policy meetings remaining this year.
According to the CME FedWatch tool, traders see an 81.5% chance that the Fed will cut interest rates by 50 basis points (bps) to 3.50%-3.75% by the year-end.
On Thursday, Federal Open Market Committee (FOMC) members, New York Fed President John Williams and San Francisco Fed President Mary Daly, cited that the current monetary policy stance is restrictive and the Fed needs to cut rates further this year amid deteriorating labor market conditions. On the contrary, Fed Governor Michael Barr expressed caution about further rate cuts as inflation is unlikely to return to the central bank’s target of 2% in the next two years.
In Friday’s session, investors will focus on the preliminary Michigan Consumer Sentiment Index and Consumer Inflation Expectations data for October, which will be published at 14:00 GMT.
Pound Sterling underperforms as UK Reeves likely raise taxes again
- The Pound Sterling continues to underperform its major currency peers on Friday as financial market participants expect the United Kingdom (UK) Chancellor of the Exchequer Rachel Reeves to raise taxes in the Autumn Statement again to address its ballooning fiscal debt, which is scheduled for late November.
- Investors worry that the announcement of fresh taxes, either on individuals’ wealth or a further increase in employers’ contribution to social security schemes, or a combination of both, would dampen the overall sentiment of households.
- The increase in employers’ contribution to National Insurance (NI) to 15% from 13.8% announced in the last budget resulted in a sharp slowdown in the labour demand. Business owners reduced their labour force to offset the impact of increased employment costs.
- An increase in tax burden on households or employers by the UK Labour government will raise questions over its credibility, after promising voters before the election not to raise taxes.
- In a speech on Thusday, Bank of England (BoE) Monetary Policy Committee (MPC) member Catherine Mann argued in favour of maintaining a restrictive monetary policy stance for longer, citing that the central bank still needs to address upside inflation risks. "The evidence from consumer behaviour is that we are not there yet,” Mann said.
Going forward, investors will focus on the UK employment data for the three months ending in August, which will be released on Tuesday.
Technical Analysis: Pound Sterling slides to near 200-day EMA
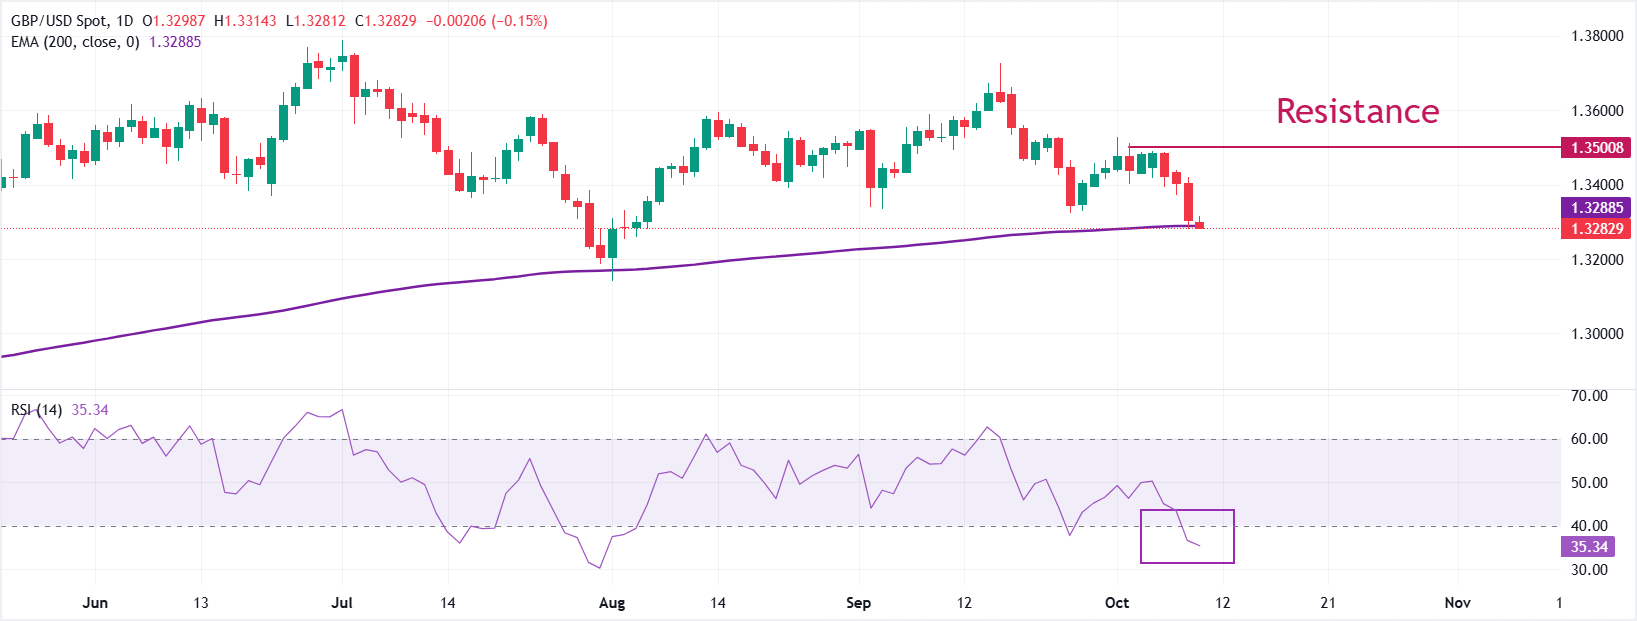
The Pound Sterling extends its downside to near 1.3300 against the US Dollar on Friday, the lowest level seen in a month. The overall trend of the GBP/USD pair has become uncertain as it drops to near the 200-day Exponential Moving Average (EMA), which trades around 1.3280.
The 14-day Relative Strength Index (RSI) slides below 40.00, suggesting the onset of a fresh bearish momentum.
Looking down, the August 1 low of 1.3140 will act as a key support zone. On the upside, the psychological level of 1.3500 will act as a key barrier.
Economic Indicator
Michigan Consumer Sentiment Index
The Michigan Consumer Sentiment Index, released on a monthly basis by the University of Michigan, is a survey gauging sentiment among consumers in the United States. The questions cover three broad areas: personal finances, business conditions and buying conditions. The data shows a picture of whether or not consumers are willing to spend money, a key factor as consumer spending is a major driver of the US economy. The University of Michigan survey has proven to be an accurate indicator of the future course of the US economy. The survey publishes a preliminary, mid-month reading and a final print at the end of the month. Generally, a high reading is bullish for the US Dollar (USD), while a low reading is bearish.
Read more.Next release: Fri Oct 10, 2025 14:00 (Prel)
Frequency: Monthly
Consensus: 54.2
Previous: 55.1
Source: University of Michigan
Consumer exuberance can translate into greater spending and faster economic growth, implying a stronger labor market and a potential pick-up in inflation, helping turn the Fed hawkish. This survey’s popularity among analysts (mentioned more frequently than CB Consumer Confidence) is justified because the data here includes interviews conducted up to a day or two before the official release, making it a timely measure of consumer mood, but foremost because it gauges consumer attitudes on financial and income situations. Actual figures beating consensus tend to be USD bullish.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.

















