USD/JPY sticks to intraday negative bias; BoJ rate hike bets could limit further losses
- The Japanese Yen attracts some sellers as a positive risk tone undermines safe-haven assets.
- Firming expectations for an imminent BoJ rate hike should help limit deeper losses for the JPY.
- Dovish Fed bets keep the USD bulls on the defensive and might contribute to capping USD/JPY.
The Japanese Yen (JPY) sticks to intraday losses heading into the European session on Tuesday amid a generally positive tone around the equity markets, which tends to undermine demand for traditional safe-haven assets. Any further JPY depreciation, however, seems elusive amid rising bets for an imminent rate hike by the Bank of Japan (BoJ), bolstered by Governor Kazuo Ueda's comments on Monday.
Furthermore, speculations that Japanese authorities would step in to stem further weakness in the domestic currency might hold back the JPY bears from placing aggressive bets. The US Dollar (USD), on the other hand, struggles to attract any meaningful buyers amid bets for another rate cut by the US Federal Reserve (Fed) this month, and might further contribute to capping the upside for the USD/JPY pair.
Japanese Yen remains depressed amid receding safe-haven demand; hawkish BoJ expectations favor bulls
- Asian stocks stage a modest recovery after the previous day's selloff, undermining traditional safe-haven assets and prompting some selling around the Japanese Yen during the Asian session on Tuesday. This, along with a modest US Dollar (USD) uptick, assists the USD/JPY pair in building on the overnight bounce from the 154.65 region, or a two-week low.
- Bank of Japan Governor Kazuo Ueda offered the strongest signal yet toward further normalization and said on Monday that the likelihood of the central bank's economic and price projections being met is rising. In fact, inflation in Japan has remained above the central bank’s 2% target for over three years, strengthening the case for policy tightening.
- Traders were quick to react and are pricing in a roughly 80% chance of a rate hike at the December 18-19 BoJ meeting, up from around 60% last week. The outlook pushed the rate-sensitive two-year Japanese government bond yield to 1% for the first time since June 2008 on Monday, and the 20-year yield to levels not seen since November 2020.
- Moreover, the 30-year government bond yields climbed to a record peak on Tuesday, and the 10-year yield reached a 17-year high, which, in turn, backs the case for the emergence of some dip-buying around the JPY.
- Japan’s Finance Minister Satsuki Katayama said on Sunday that recent erratic swings in the foreign exchange market and rapid JPY weakening are clearly not driven by fundamentals. It’s our position to issue warnings against such matters, Katayama added further, fueling speculations about the government intervention to stem any further JPY weakness.
- The US Dollar dived to a two-week low on Monday after the Institute for Supply Management’s (ISM) Manufacturing PMI fell to 48.2 in November, down from 48.7 in the previous month. The reading missed consensus estimates and comes on top of the recent tepid US economic data, suggesting that growth in the world's largest economy is cooling.
- Moreover, dovish signals from Federal Reserve officials fueled speculation for another rate reduction this month. In fact, the CME Group's FedWatch Tool indicates a nearly 88% chance of a quarter-point rate cut at the Fed’s December 9–10 meeting. This marks a big divergence in comparison to the BoJ's hawkish outlook and should cap the USD/JPY pair.
- Heading into next week's Fed rate decision, investors will confront the release of the US Personal Consumption Expenditure (PCE) Price Index – the central bank's preferred inflation gauge – for more cues about the future rate-cut path. The uncertainty, however, remains in the absence of the official jobs report because of the recent federal government shutdown.
USD/JPY approaches descending channel resistance, around 156.00; not out of the woods yet
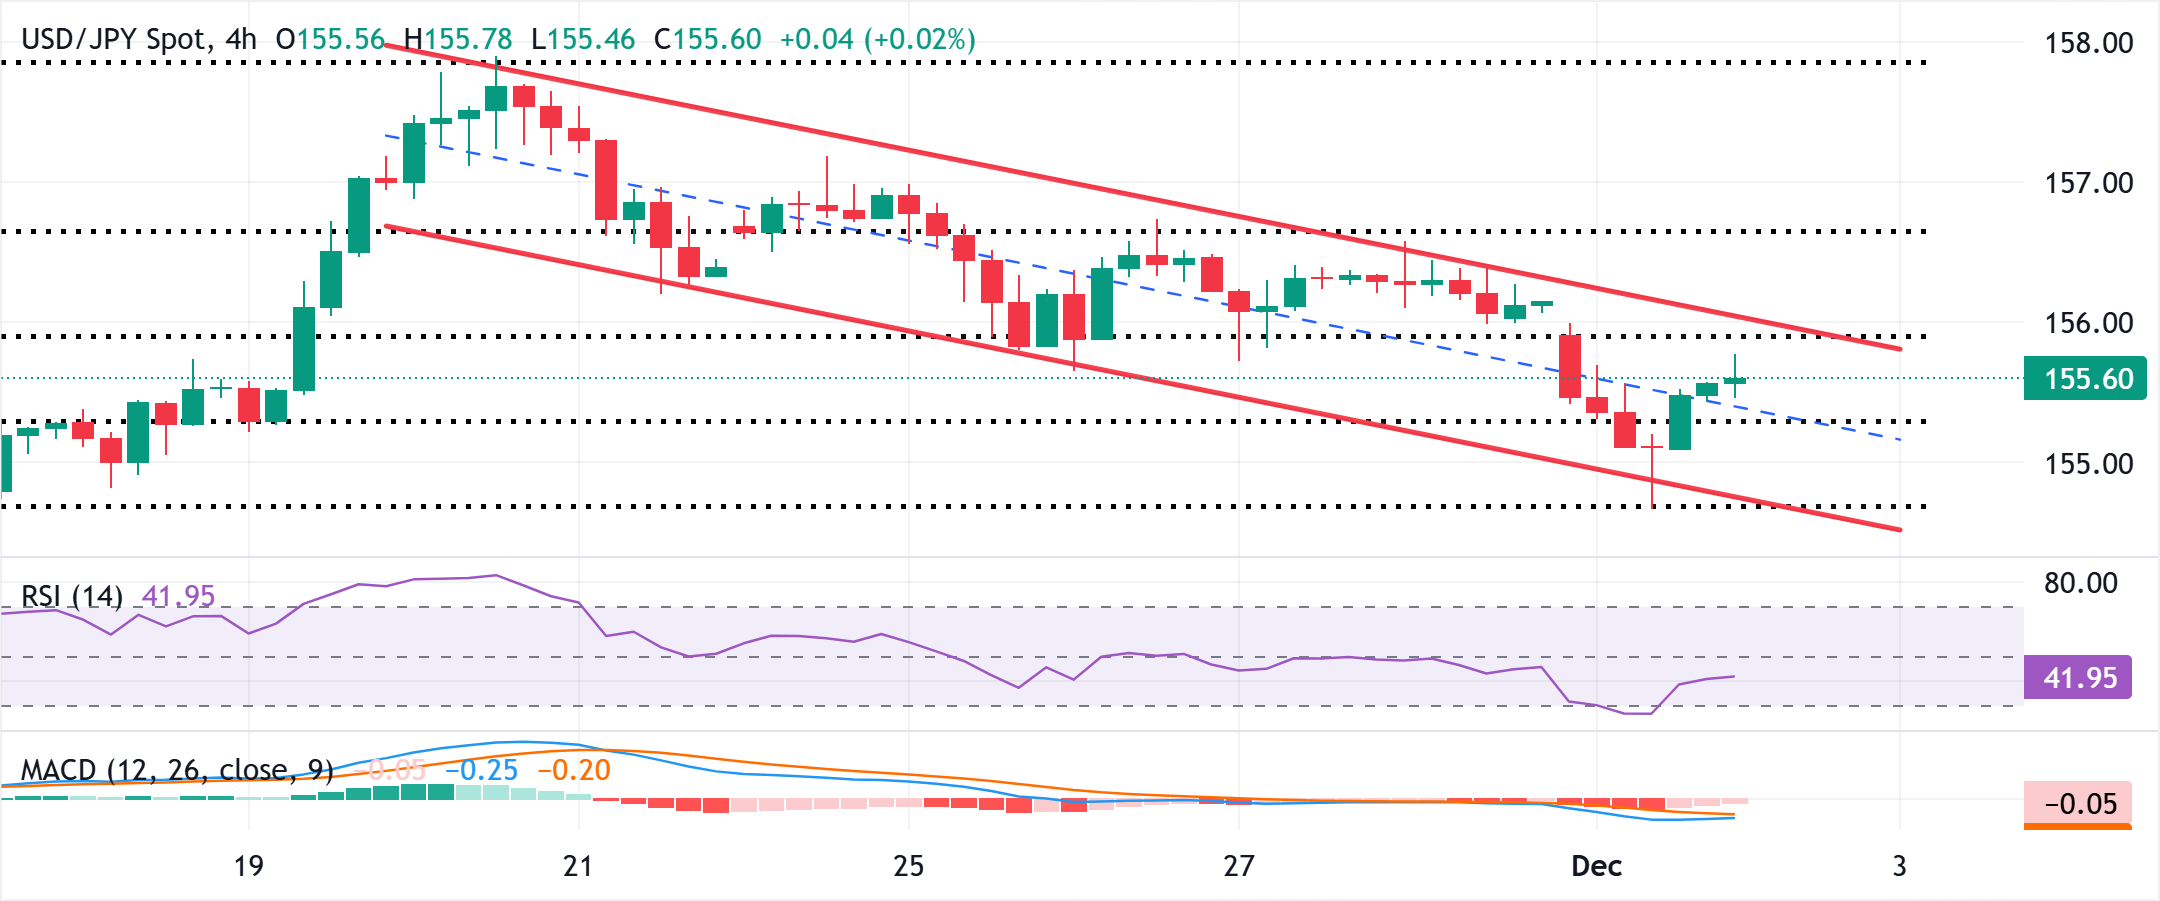
The USD/JPY pair's corrective slide from the 158.00 neighborhood, or the highest level since mid-January, touched last month, has been along a downward-sloping channel. The overnight bounce validates the trend-channel support, which coincides with the 61.8% Fibonacci retracement level of the November upswing and should now act as a key pivotal point. A convincing break below will be seen as a fresh trigger for bearish traders and pave the way for an extension of the pair's two-week-old downtrend. In the meantime, the 155.00 psychological mark could protect the immediate downside.
On the flip side, any subsequent move up is likely to confront stiff resistance around the 156.00 neighborhood, representing the top boundary of the aforementioned trend-channel. A sustained strength beyond could trigger a short-covering rally and lift the USD/JPY pair to the 156.60-156.65 intermediate hurdle en route to the 157.00 round figure. The momentum could extend further towards mid-157.00s before spot prices make a fresh attempt to reclaim the 158.00 mark.
US Dollar Price Last 7 Days
The table below shows the percentage change of US Dollar (USD) against listed major currencies last 7 days. US Dollar was the strongest against the Swiss Franc.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | -0.78% | -0.83% | -0.69% | -0.82% | -1.37% | -2.05% | -0.52% | |
| EUR | 0.78% | -0.05% | 0.11% | -0.04% | -0.59% | -1.29% | 0.26% | |
| GBP | 0.83% | 0.05% | 0.14% | 0.00% | -0.54% | -1.23% | 0.31% | |
| JPY | 0.69% | -0.11% | -0.14% | -0.14% | -0.68% | -1.39% | 0.16% | |
| CAD | 0.82% | 0.04% | -0.01% | 0.14% | -0.55% | -1.26% | 0.30% | |
| AUD | 1.37% | 0.59% | 0.54% | 0.68% | 0.55% | -0.70% | 0.85% | |
| NZD | 2.05% | 1.29% | 1.23% | 1.39% | 1.26% | 0.70% | 1.56% | |
| CHF | 0.52% | -0.26% | -0.31% | -0.16% | -0.30% | -0.85% | -1.56% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the US Dollar from the left column and move along the horizontal line to the Japanese Yen, the percentage change displayed in the box will represent USD (base)/JPY (quote).
Author

Haresh Menghani
FXStreet
Haresh Menghani is a detail-oriented professional with 10+ years of extensive experience in analysing the global financial markets.

















