|

Nonfarm Payrolls Preview: Dollar needs a strong number to keep rallying

  • The dollar strengthens ahead of the release amid stimulus hopes.
  • The US is expected to have recovered some 50K jobs’ positions in January.
  • The immunization campaign progress slowly, but hopes for an economic comeback persist.

The US monthly report for January will be out this Friday. The country is expected to have added 50K new positions in the month, after losing 140K in December. The cold weather brought a sharp increase in coronavirus cases, which in turn led to some restrictive measures in certain areas of the country. The situation receded as the government sped up vaccination, but the daily number of contagions remains high, and immunization slow. On Wednesday, the country reported 113K cases and roughly 4,000 deaths, a sign that they are far from over with the current situation.

The Unemployment Rate is expected to have remained steady at 6.7%. The Labor Force Participation Rate stood at 61.5% in December, while the underemployment rate was at 11.7%.

Slow progress out of the pandemic

The US has lost roughly 22 million jobs between March and April 2020, when the pandemic arrived in America. So far the country has recovered roughly 12 million, although the pace of jobs’ creation has been decreasing sharply as time went by, and as mentioned, the country actually lost positions. The services sector was the most hit by the pandemic and is still the weakest link in the chain.

At this pace is hard to predict when the employment sector will fully recover from the initial hit, but conservative estimates talk about four years. The global immunization campaign is moving quite slow, although, in the US, 35 million doses have been given.  Should the world approach head immunity, the time-frame could be reduced.

Leading Indicators provide mixed hints

 Data released ahead of the release was mostly encouraging, although there are a few downers. As said, the pandemic situation is the major drag which led to jobs’ losses in December. Additionally, Consumer Confidence remains subdued, with the CB indicator holding near its post-pandemic low and the University of Michigan estimate stuck around 80.

On a positive note, the ISM PMIs showed that sub-employment component improved in January. Still, worth remembering that these indexes are more about business sentiment than actual progress in the economy.

Initial Jobless Claims continue to retreat on a weekly basis but remain above the 800K threshold. As for the ADP survey, the private sector reported that it added 174K new jobs in January, quite a recovery from the previous -78K. Finally, planned job cuts announced by U.S.-based companies rose 3.3%, to 79,552, in January from 77,030 in December, according to the Challenger Job Cuts report.

US jobs report pre-release checklist – Feb 5th, 2021

Previous Non-Farm PayrollsNegativeThe US economy lost 140K jobs in December, way worse than the 71K gain expected, derailing the post-pandemic job market recovery.
Challenger Job CutsNeutralCorporate layoffs in the United States have stabilized just below 80K per month in the last two releases, just a bit over the usual pre-pandemic levels. 
Initial Jobless Claims NeutralFirst-time employment claims 4-week average has stabilized above 800K, halting the job recovery despite five of the last seven releases bettering expectations.
Continuing Jobless Claims PositiveThe unemployment-benefit claimants' downtrend is still relentless, falling below 5 million for the first time since COVID-19 halted the economic activity.
ISM Services PMI PositiveThe labor sub-index in the US main service survey rallied in January to 55.2, the highest level since last February.
ISM Manufacturing PMI PositiveThe employment sub-index in the US main manufacturing survey keeps rising, hitting 52.6 in January, the highest level since June 2019.
University of Michigan Consumer Confidence Index NegativeThe UMich consumer sentiment survey has remained stuck around the 80 mark since the pandemic struck, way below pre-covid levels.
Conference Board Consumer Confidence Index NeutralThe Conference Board Consumer Confidence Index® improved a bit in January from 88.6 to 89.3 but is still below 90, close to the post-covid bottom.
ADP Employment Report PositivePrivate sector employment bounced back in January, back in positive territory as it printed a 174K job gain. It is only the second better-than-expected release in the last seven for this highly correlated to NFP indicator.
JOLTS Job Openings PositiveHiring recovered in the last JOLTS release (October), although the lagging nature of this indicator makes it less decisive for evaluating NFP. 

Dollar’s possible reaction to different scenarios

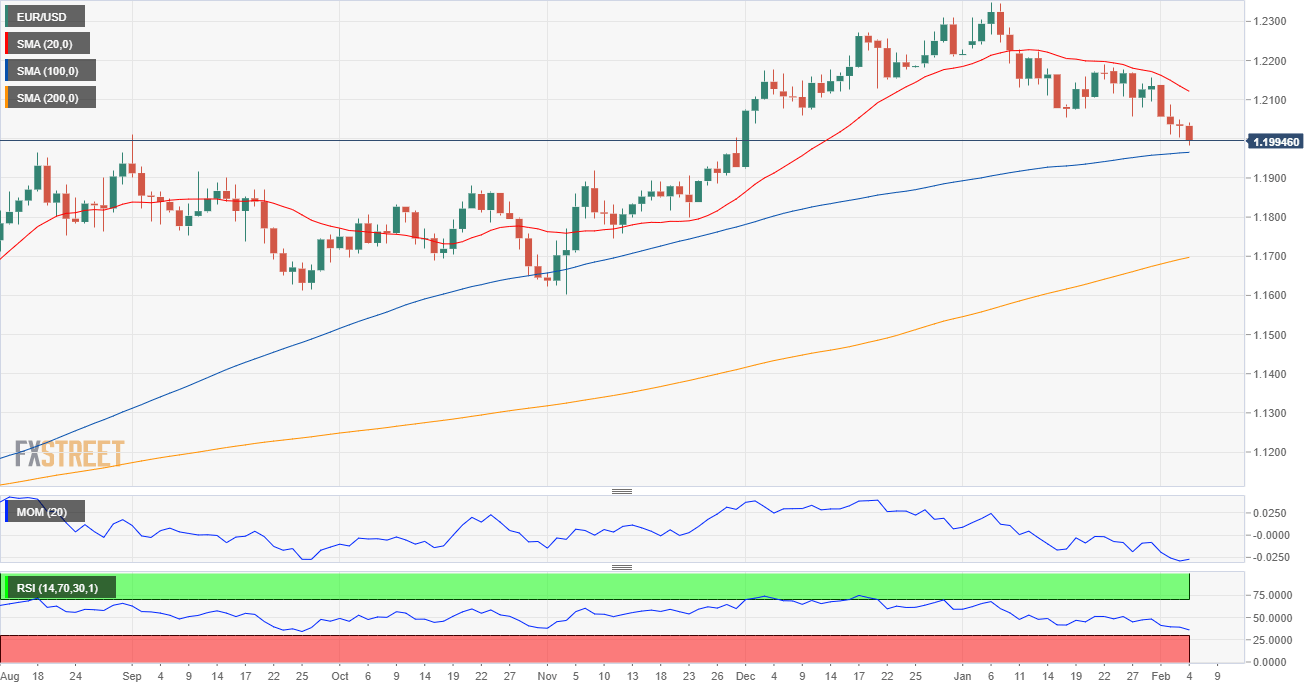
The greenback is strengthening ahead of the release, backed by hopes of another stimulus package in the US.  An upbeat report could further boost the dollar, regardless of equities’ behaviour, particularly against its European rivals. Among those, the EUR is the weakest, as the Sterling became more interesting after the BOE cooled negative rates’ hopes.

Commodity-linked currencies are more likely to fall against their American rival if Wall Street comes under selling pressure. Higher yields will push USD/JPY up, no matter the outcome of the report. 
Author

Valeria Bednarik

Valeria Bednarik was born and lives in Buenos Aires, Argentina. Her passion for math and numbers pushed her into studying economics in her younger years.


More from Valeria Bednarik
Share:

Editor's Picks

AUD/USD flirts with 0.7000, lowest since early August amid bullish USD

AUD/USD hits a fresh low since early August during the Asian session on Friday and looks vulnerable near 0.7000 after breaking below the 200-day SMA overnight. Against the backdrop of the hawkish Fed, a two-day rally in oil prices revives inflation fears and continues to push US bond yields to multi-year highs. Adding to this, geopolitical risks lift the US Dollar to a two-month high, overshadowing RBA rate hike bets and weighing on the pair.

USD/JPY pulls back from three-week high after failing near 159.00

USD/JPY edges lower during the Asian session on Friday, stalling its recent strong move to a three-week high of 159.00 as Japanese Yen bears turn cautious amid intervention fears. Meanwhile, the US Dollar retains a strong bullish undertone as the Fed's hawkish outlook and oil-driven inflation fears continue to push US bond yields to multi-year peaks. Furthermore, the BoJ's dovish rate hike last week might cap JPY and support spot prices.

Gold treads water below $4,300

Gold grabs some buying attention and advances marginally at the end of the week, partially retracing the weekly decline, although it is still navigating below the key $4,300 mark per troy ounce. The fresh selling bias on the Greenback and the modest decline in US Treasury yields appear to support the humble advance in the precious metal.

Week ahead: Rate hike bets face a crucial data week
Despite the solid drop from the mid-September high, oil prices remained in the driver’s seat for another week, setting the tone in financial markets. Six months have passed since the late-February start of the US-Iran conflict, and there is still no breakthrough in the stalled talks, despite pressure from regional leaders and the rest of the world.
CFTC Report: Defensive currency positioning takes hold
The week in one sentence: Sterling and Euro shorts deepened in the week to September 22, while Yen longs were cut sharply. Oil positioning improved despite a steep price decline, and Gold exposure remained crowded. The main signal was a more defensive currency positioning backdrop.
Fed vs BoJ: Both hiked. The market only believes one of them – and the chart shows which

The Fed and the BoJ have just done something remarkably similar. Both central banks raised interest rates by 25 bps last week, both are confronting inflation risks, and both signal that future decisions will depend on incoming economic data.














