EUR/USD Forecast: Euro retreats as markets turn risk-averse
- EUR/USD loses traction and declines toward 1.1500 on Friday.
- Escalating geopolitical tensions in the Middle East cause markets to turn risk-averse.
- The US economic calendar will feature the UoM Consumer Sentiment Index data for June.
EUR/USD gathered bullish momentum and climbed to its highest level since November 2021 above 1.1600 on Thursday. With markets turning risk-averse on Friday, the pair corrects lower but manages to hold above 1.1500.
Euro PRICE Today
The table below shows the percentage change of Euro (EUR) against listed major currencies today. Euro was the weakest against the US Dollar.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 0.44% | 0.40% | 0.36% | 0.18% | 0.74% | 0.94% | 0.28% | |
| EUR | -0.44% | -0.01% | -0.03% | -0.21% | 0.38% | 0.46% | -0.17% | |
| GBP | -0.40% | 0.00% | -0.10% | -0.28% | 0.30% | 0.46% | -0.14% | |
| JPY | -0.36% | 0.03% | 0.10% | -0.14% | 0.40% | 0.58% | -0.05% | |
| CAD | -0.18% | 0.21% | 0.28% | 0.14% | 0.54% | 0.77% | 0.14% | |
| AUD | -0.74% | -0.38% | -0.30% | -0.40% | -0.54% | 0.17% | -0.44% | |
| NZD | -0.94% | -0.46% | -0.46% | -0.58% | -0.77% | -0.17% | -0.61% | |
| CHF | -0.28% | 0.17% | 0.14% | 0.05% | -0.14% | 0.44% | 0.61% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the Euro from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent EUR (base)/USD (quote).
The soft producer inflation data for May and the disappointing weekly Initial Jobless Claims print from the US made it difficult for the US Dollar (USD), which suffered large losses against its rivals on weaker-than-expected May Consumer Price Index (CPI) data on Wednesday, to find demand on Thursday. As a result, EUR/USD extended its weekly rally.
In the early trading hours of the Asian session on Friday, news of Israel launching a military strike against Iran triggered an intense flight to safety. The USD benefited from safe-haven flows and caused EUR/USD to turn south.
In the second half of the day, the University of Michigan (UoM) will publish the Consumer Sentiment Index data for June. Investors are likely to ignore this report and remain focused on geopolitical headlines.
Market participants could remain interested in safer assets amid growing fears over a further escalation of the Israel-Iran conflict and force EUR/USD to stay on the back foot heading into the weekend. Israel's Prime Minister Benjamin Netanyahu said that the operation will continue for as many days as it takes.
EUR/USD Technical Analysis
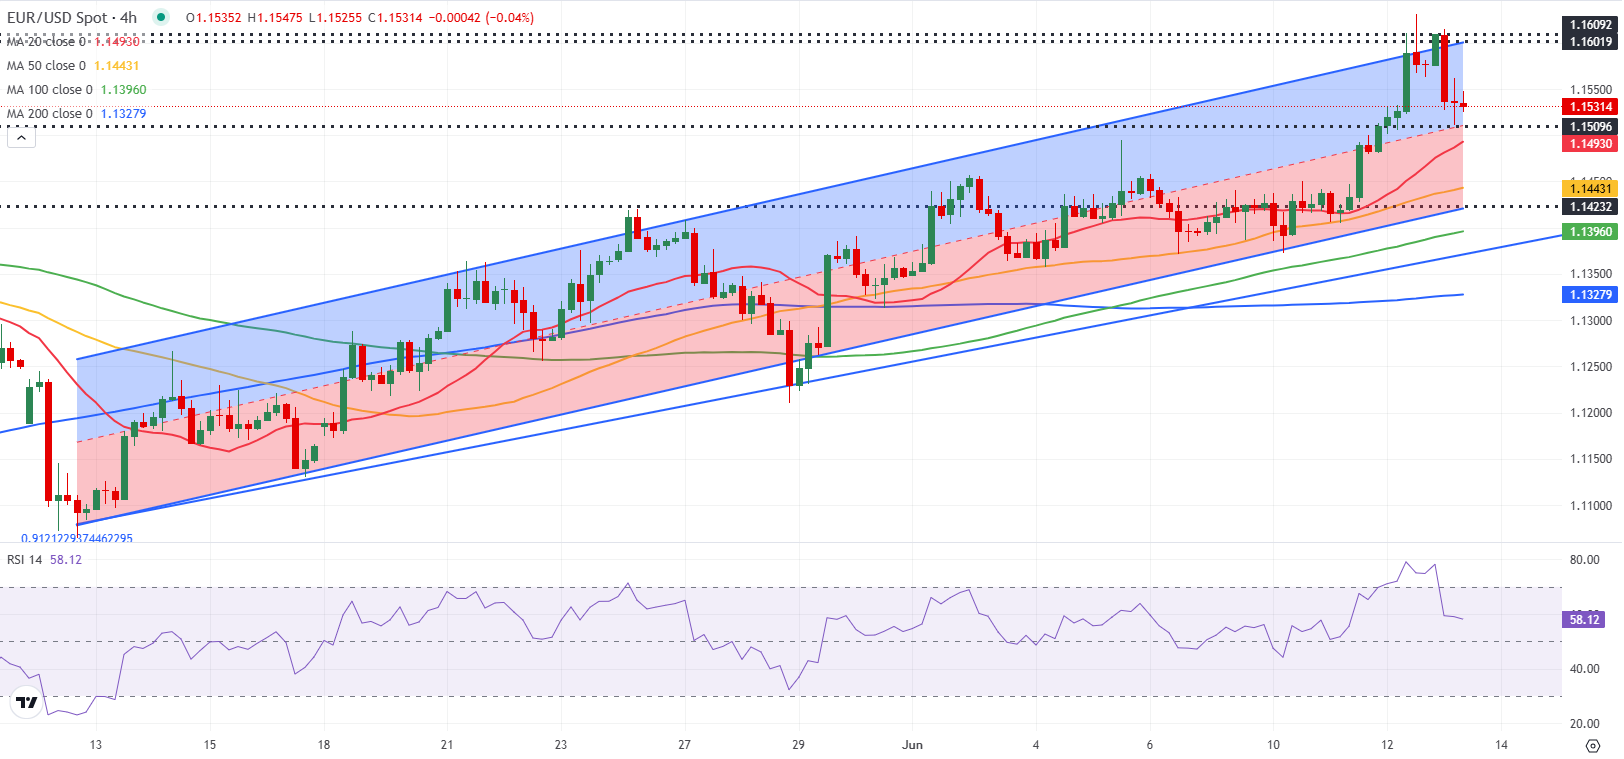
The Relative Strength Index (RSI) indicator on the 4-hour chart holds above 50 and EUR/USD continues to trade above the 20-period Simple Moving Average (SMA), suggesting that the bullish bias remains intact despite the recent pullback.
On the upside, 1.1600 (upper limit of the ascending channel) aligns as immediate resistance before 1.1660 (static level) and 1.1700 (static level, round level). Looking south, supports could be seen at 1.1500-1.1490 (static level, mid-point of the ascending channel, 20-period SMA), 1.1450 (50-period SMA) and 1.1420 (lower limit of the ascending channel).
Euro FAQs
The Euro is the currency for the 19 European Union countries that belong to the Eurozone. It is the second most heavily traded currency in the world behind the US Dollar. In 2022, it accounted for 31% of all foreign exchange transactions, with an average daily turnover of over $2.2 trillion a day. EUR/USD is the most heavily traded currency pair in the world, accounting for an estimated 30% off all transactions, followed by EUR/JPY (4%), EUR/GBP (3%) and EUR/AUD (2%).
The European Central Bank (ECB) in Frankfurt, Germany, is the reserve bank for the Eurozone. The ECB sets interest rates and manages monetary policy. The ECB’s primary mandate is to maintain price stability, which means either controlling inflation or stimulating growth. Its primary tool is the raising or lowering of interest rates. Relatively high interest rates – or the expectation of higher rates – will usually benefit the Euro and vice versa. The ECB Governing Council makes monetary policy decisions at meetings held eight times a year. Decisions are made by heads of the Eurozone national banks and six permanent members, including the President of the ECB, Christine Lagarde.
Eurozone inflation data, measured by the Harmonized Index of Consumer Prices (HICP), is an important econometric for the Euro. If inflation rises more than expected, especially if above the ECB’s 2% target, it obliges the ECB to raise interest rates to bring it back under control. Relatively high interest rates compared to its counterparts will usually benefit the Euro, as it makes the region more attractive as a place for global investors to park their money.
Data releases gauge the health of the economy and can impact on the Euro. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the single currency. A strong economy is good for the Euro. Not only does it attract more foreign investment but it may encourage the ECB to put up interest rates, which will directly strengthen the Euro. Otherwise, if economic data is weak, the Euro is likely to fall. Economic data for the four largest economies in the euro area (Germany, France, Italy and Spain) are especially significant, as they account for 75% of the Eurozone’s economy.
Another significant data release for the Euro is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought after exports then its currency will gain in value purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Eren Sengezer
FXStreet
As an economist at heart, Eren Sengezer specializes in the assessment of the short-term and long-term impacts of macroeconomic data, central bank policies and political developments on financial assets.
















