|

Wake Up Wall Street (SPY) (QQQ): Alphabet goes backwards as stocks hold gains for now

Here is what you need to know on Wednesday, October 26:

Equity markets rallied on Tuesday as investors remain confident of lower interest rates. We had the "Fed pause" article from The Wall Street Journal, which got the market's hopes up. This then has continued with some stronger-than-expected earnings.

Overall,129 companies have so far reported from the S&P 500, and 73.6% have beaten admitedly lowered estimates, according to Refinitiv. That view was challenged afterhours with a shocker from Alphabet (GOOGL), which is currently trading some 6.4% lower in the premarket. Stocks are less hopeful this morning based on that, especially the tech-heavy Nasdaq. The consumer remains in good shape, though it would appear at least at the lower end of the spectrum. Inflation is being passed on, and this is further reinforced by Kraft Heinz this morning posting solid earnings.

The dollar, meanwhile, continues to step back as a combination of sterling optimism (misplaced in my view), yen caution and hawkish Australian inflation all combine to send the dollar index back to 110.20. Oil is boosted by the weaker dollar to $86.20, while Bitcoin is the big mover up to $20,300. Gold too is taking the risk on the mandate and pushing to $1,670. 

See forex today

European markets are mixed: Eurostoxx is flat, FTSE -0.4%, and Dax +0.2%.

US futures are negative: Dow is flat, S&P -0.8%, and Nasdaq -1.8%.

Wall Street (SPY) (QQQ) top news

UK fiscal plan is delayed.

US mortgage demand continues to fall.

Boeing (BA) misses on top and bottom lines.

Alphabet (GOOGL) is down nearly 6% on poor earnings.

Microsoft (MSFT) posts strong cloud revenue as it beats on top and bottom lines but is dragged lower by PC demand and the dollar.

Kraft Heinz (KHC) beats on top and bottom lines.

Bed Bath & Beyond (BBBY) names CEO.

Hilton (HLT) travel remains strong as it lifts profit forecasts.

Visa (V) sees solid consumer spending as it beats on EPS and revenue.

Mobileye (MBLY) self-driving division of Intel (INTC) set to IPO today at $21.

Barclays (BCS) earnings are strong. 

Deutsche Bank (DB) also reported strong earnings.

Spotify (SPOT): EPS misses, revenue beats, mentions slow advertising growth.

Canopy Growth (CGC) to create a holding company to fast-track entry to US market.

Upgrades and downgrades
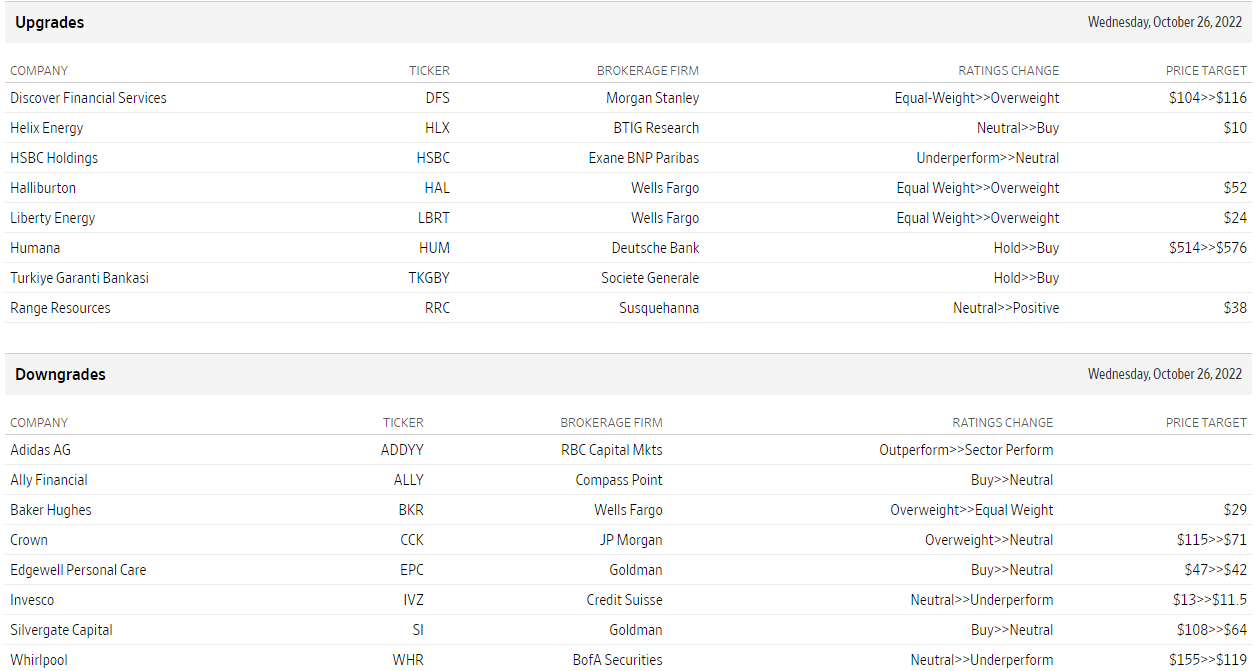
Source: WSJ.com

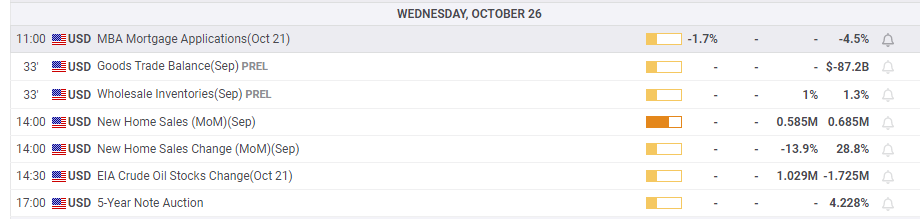
Economic releases
Author

Ivan Brian

Ivan Brian

FXStreet

Ivan Brian started his career with AIB Bank in corporate finance and then worked for seven years at Baxter. He started as a macro analyst before becoming Head of Research and then CFO.


More from Ivan Brian
Share:

Editor's Picks

AUD/USD edges higher above 0.7050 as hot CPI lifts RBA rate hike odds

The AUD/USD pair gathers strength to near 0.7055 during the Asian trading hours on Thursday. The Australian Dollar edges higher against the US Dollar as hotter inflation data bolsters expectations of Reserve Bank of Australia rate hikes. The US September Personal Consumption Expenditures inflation report will be in the spotlight later on Thursday.


USD/JPY retakes 158.00 as USD stalls the post-FOMC corrective slide

USD/JPY attracts some dip-buyers during the Asian session on Thursday, climbing back above 158.00 as the US Dollar reverses part of the post-FOMC pullback from a two-week high. Bulls, however, await key US macro data – the Advance Q3 GDP and the PCE Price Index – before positioning for further gains. Focus will then shift to the crucial BoJ policy update on Friday amid firming expectations for a December rate hike.

Gold weakens further below $4,050 amid Fed rate hike bets and Iran risks

Gold sticks to intraday losses below the $4,050 level heading into the European session ,and for now seems to have snapped a three-day winning streak to the weekly top set the previous day. The US Dollar attracts fresh buyers after Wednesday's post-FOMC corrective slide from a two-week high and is seen as a key factor weighing on the precious metal.

US GDP expected to grow at 3.2% in Q3

The United States Bureau of Economic Analysis is set to publish its preliminary estimate of the Gross Domestic Product for the July-September period on Thursday, with analysts expecting the data to show annualised growth at a solid 3.2%, a decent improvement from the 2.2% expansion recorded in the previous quarter. Markets brace for US growth and PCE data amid geopolitical jitters

European Central Bank is expected to hold interest rates despite high inflation pressures

The European Central Bank concludes its two-day monetary policy meeting on Thursday and will announce its decision at 13:15 GMT. The bank is widely expected to leave the interest rate on the Main Refinancing Operations and the Deposit Facility unchanged at 2.65% and 2.50%, respectively, after having raised both of them by 25 basis points in September.

Anthropic pledged $270 billion to Amazon, Google, and Microsoft. Here's who actually gets paid
Anthropic owes Amazon, Google, and Microsoft at least $269.4 billion for computing power, even if it uses less. All three sell its models and handle its billing, and Amazon and Google own stakes and lend it money, so they get paid regardless of how the IPO goes. The Dario Amodei-led Anthropic filed its initial public offering (IPO) on Monday, seeking a listing on the Nasdaq under the ticker ANT.