USD/INR gathers strength amid rising month-end US Dollar demand
- The Indian Rupee trades softer in Thursday's early European session.
- High USD bids for month-end payments and uncertainties surrounding Trump's trade policies undermine the INR.
- The RBI intervention might support the INR and cap the pair’s upside.

The Indian Rupee (INR) edges lower to near a recoed low on Thursday. The month-end US Dollar (USD) demand from importers weighs on the local currency. Additionally, the speculation over aggressive trade policies under Donald Trump’s presidency and the expectation that the Federal Reserve (Fed) might be cautious about further rate cuts could boost the USD against the INR in the near term.
On the other hand, the Reserve Bank of India (RBI) could step in to sell USD, which might help limit the INR’s losses. The US markets will be closed on Thursday in observance of the Thanksgiving holiday. Traders will keep an eye on the Indian Federal Fiscal Deficit for October and GDP growth data for the July-September 2024 quarter (Q2 FY25), which is set to be released on Friday.
Indian Rupee remains weak due to Trump-related policies, Dollar demand intensifies
- "Rupee lost all its sheen it had gained on Wednesday and fell to 84.48 before recovering as RBI sold dollars... but dollars were bought again on account of month-end demand and it (rupee) closed lower," said Anil Kumar Bhansali, Head of Treasury and Executive Director, Finrex Treasury Advisors LLP.
- Inflation in the US, as measured by the change in the Personal Consumption Expenditures (PCE) Price Index, rose to 2.3% YoY in October from 2.1% in September, the US Bureau of Economic Analysis (BEA) reported on Wednesday. This figure matched the expectation.
- The US core PCE Price Index, which excludes volatile food and energy prices, climbed 2.8% in the same period, compared to a 2.7% increase in September, in line with the market consensus. On a monthly basis, the core PCE Price Index increased 0.3% in October, as expected.
- The US economy grew at a 2.8% annual pace from July through September, the Commerce Department's Bureau of Economic Analysis reported in its second estimate of third-quarter Gross Domestic Product (GDP).
- Futures traders are now pricing in a 66.5% chance that the Fed will cut rates by a quarter point in December, up from 55.7% before the PCE data, according to the CME FedWatch Tool. However, they expect the Fed to leave rates unchanged at its January and March 2025 meetings.
USD/INR’s constructive outlook prevails
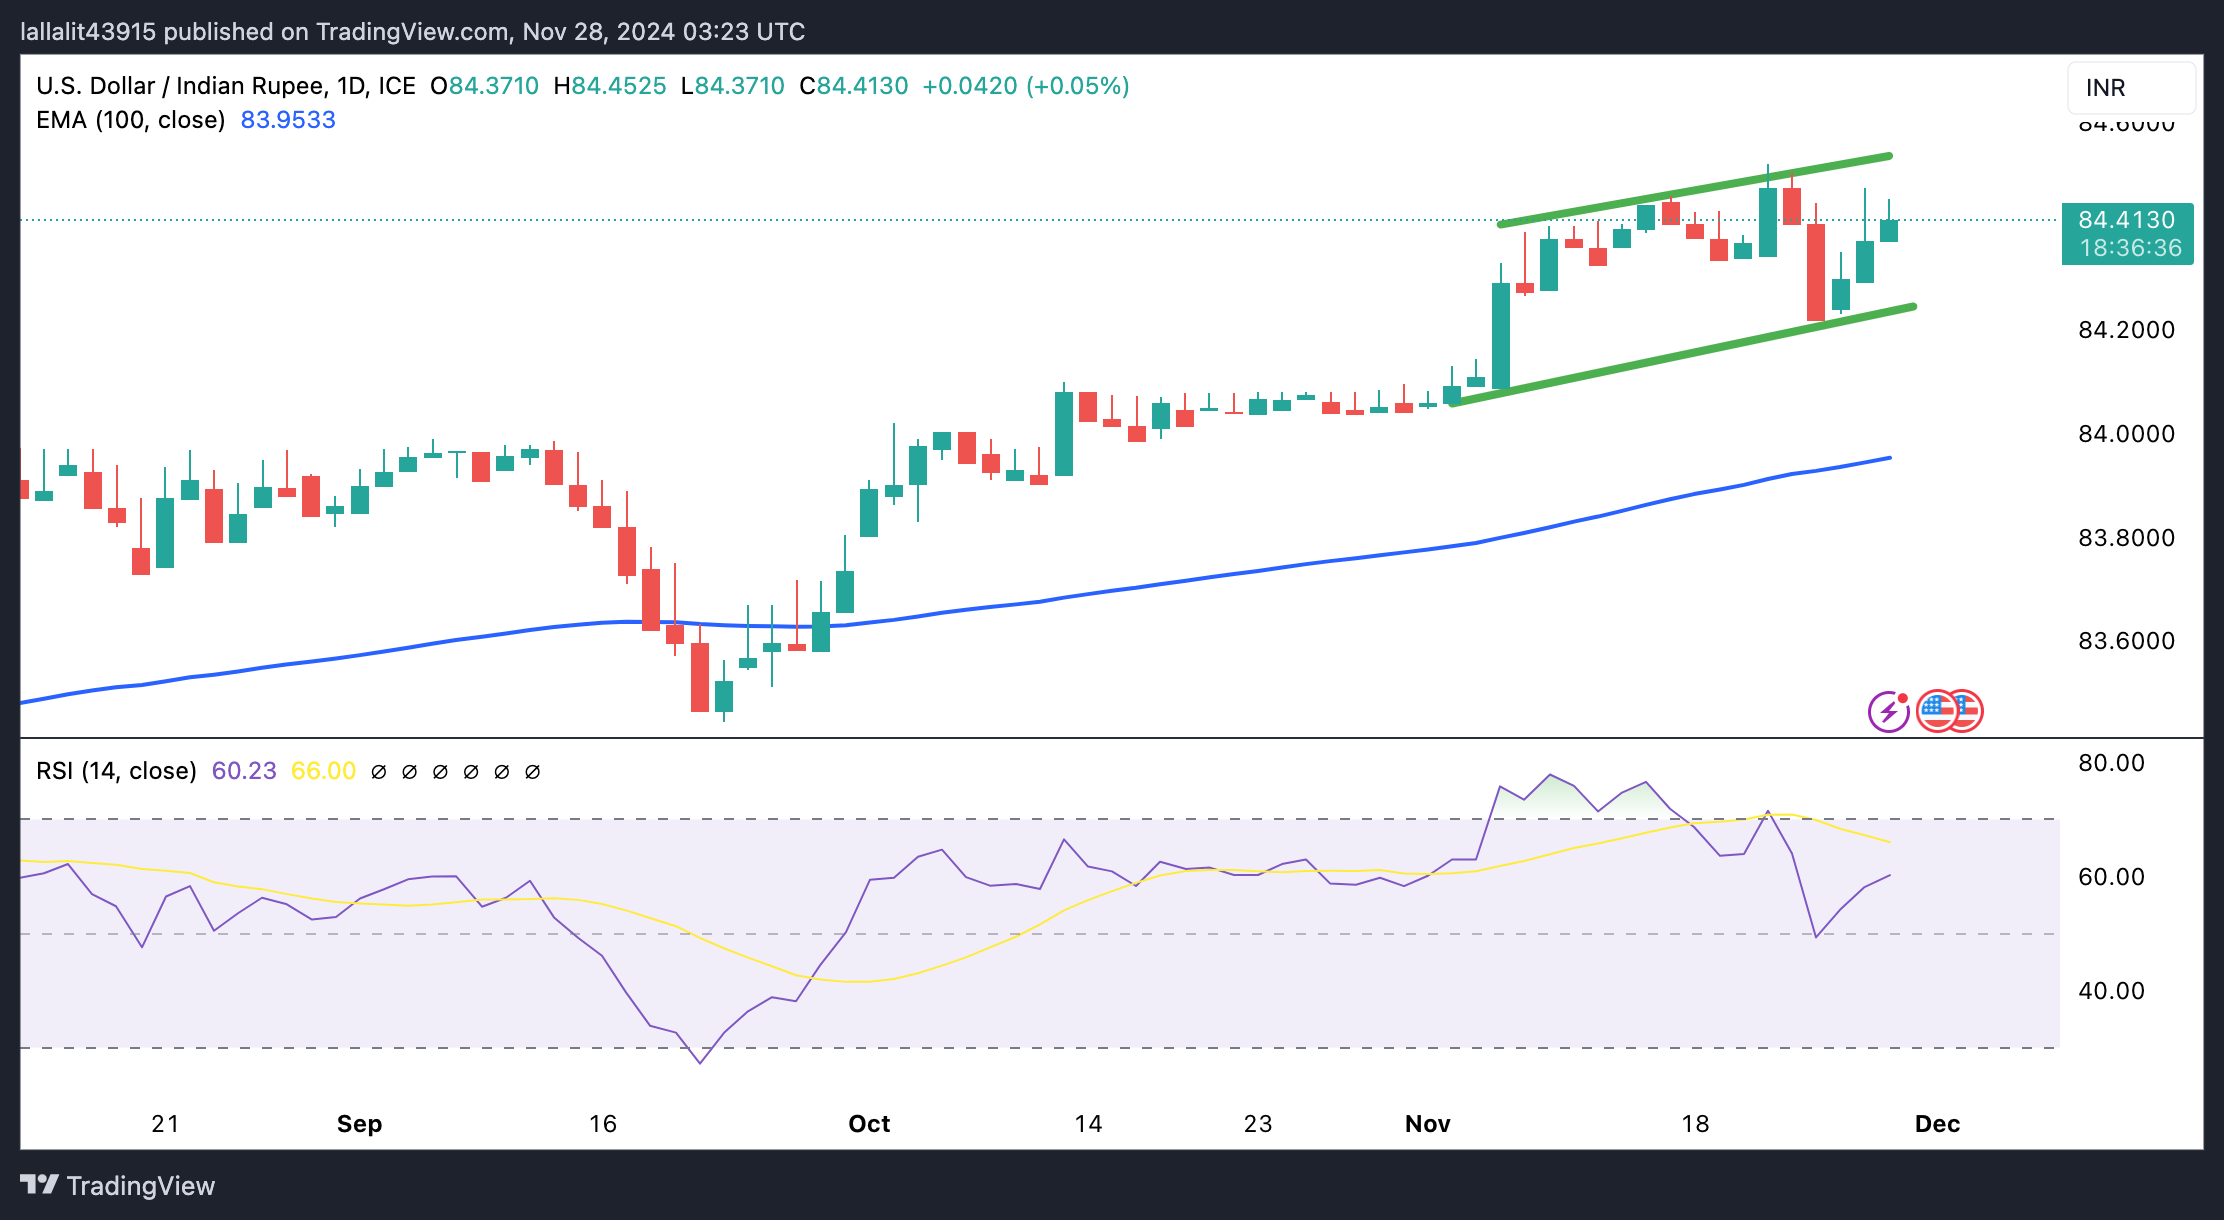
The Indian Rupee trades on a weaker note on the day. The uptrend of the USD/INR pair remains intact within an ascending trend channel on the daily chart, with the price holding above the key 100-day Exponential Moving Average (EMA). The path of least resistance is to the upside as the 14-day Relative Strength Index stands above the midline near 58.0, indicating bullish sentiment in the near term.
The key upside barrier for USD/INR is seen at the 84.50-84.55 region, representing the all-time high and the upper boundary of the trend channel. Extended gains above this level could attract some buyers to the 85.00 psychological mark.
In the bearish event, any follow-through selling below the lower limit of the trend channel of 84.24 could expose 83.95, the 100-day EMA. Further south, the next support level emerges at 83.65, the low of August 1.
Indian Rupee FAQs
The Indian Rupee (INR) is one of the most sensitive currencies to external factors. The price of Crude Oil (the country is highly dependent on imported Oil), the value of the US Dollar – most trade is conducted in USD – and the level of foreign investment, are all influential. Direct intervention by the Reserve Bank of India (RBI) in FX markets to keep the exchange rate stable, as well as the level of interest rates set by the RBI, are further major influencing factors on the Rupee.
The Reserve Bank of India (RBI) actively intervenes in forex markets to maintain a stable exchange rate, to help facilitate trade. In addition, the RBI tries to maintain the inflation rate at its 4% target by adjusting interest rates. Higher interest rates usually strengthen the Rupee. This is due to the role of the ‘carry trade’ in which investors borrow in countries with lower interest rates so as to place their money in countries’ offering relatively higher interest rates and profit from the difference.
Macroeconomic factors that influence the value of the Rupee include inflation, interest rates, the economic growth rate (GDP), the balance of trade, and inflows from foreign investment. A higher growth rate can lead to more overseas investment, pushing up demand for the Rupee. A less negative balance of trade will eventually lead to a stronger Rupee. Higher interest rates, especially real rates (interest rates less inflation) are also positive for the Rupee. A risk-on environment can lead to greater inflows of Foreign Direct and Indirect Investment (FDI and FII), which also benefit the Rupee.
Higher inflation, particularly, if it is comparatively higher than India’s peers, is generally negative for the currency as it reflects devaluation through oversupply. Inflation also increases the cost of exports, leading to more Rupees being sold to purchase foreign imports, which is Rupee-negative. At the same time, higher inflation usually leads to the Reserve Bank of India (RBI) raising interest rates and this can be positive for the Rupee, due to increased demand from international investors. The opposite effect is true of lower inflation.
Author

Lallalit Srijandorn
FXStreet
Lallalit Srijandorn is a Parisian at heart. She has lived in France since 2019 and now becomes a digital entrepreneur based in Paris and Bangkok.

















