US Dollar goes nowhere while markets write off Fed as non-event
- The US Dollar Index trades broadly flat after dipping to a five-day low on Tuesday around 99.20.
- Geopolitical headlines took over in early trading with China and the US to meet this weekend in Switzerland, and Pakistan-India conflict flaring up.
- The US Dollar Index remains stuck in a wait-and-see range as the Federal Reserve rate decision is just around the corner.
The US Dollar Index (DXY), which tracks the performance of the US Dollar (USD) against six major currencies, trades broadly flat to marginally higher on Wednesday at around 99.40. That level just a few percentage points away from the fresh five-day low from Tuesday. Traders are meanwhile assessing news about progress between China and the US regarding trade talks and brace for the Federal Reserve (Fed) interest-rate decision later this Wednesday.
Not much is expected from this rate decision as markets almost fully price in that the Fed will keep rates stable despite pressure from US President Donald Trump to cut them.
On the geopolitical front, tensions flared up between Pakistan and India. Pakistan said it shot down five Indian airplanes and took soldiers prisoner in retaliation for Indian military strikes early on Wednesday. The prospect of a war between the nuclear-armed neighbors should see some safe haven inflow towards US bonds or Gold, for example, although any added haven demand is, at this stage, being canceled out by the trade talks optimism, Bloomberg reports.
Daily digest market movers: Nothing new to report for Powell
- US Treasury Secretary Scott Bessent and US Trade Representative Jamieson Greer will travel to Switzerland for trade talks with the Chinese delegation, led by Vice Premier He Lifeng, this weekend. Both parties are seeking to de-escalate a tariff standoff that has threatened to hammer both economies. In this first phase, no trade talks as such will be held, though rather talks to de-escalate the situation, according to Bessent on Fox News.
- At 18:00 GMT, the Fed rate decision will be released with a joint statement. Expectations are for the Fed to maintain its policy rate at the 4.25%-4.50% range.
- At 18:30 GMT, Fed Chairman Powell will take the stage to comment on the recent policy rate decision and take questions from reporters in the room.
- Equities in Europe have rolled over and are trading near 0.5% losses on the day near their closing bell. US equities are doing a bit better, with the Dow Jones leading the surge, up around 0.5%.
- The CME FedWatch tool shows the chance of an interest rate cut by the Federal Reserve in June’s meeting at 28.3%. Further ahead, the July 30 decision sees odds for rates being lower than current levels at 74.2%.
- The US 10-year yields trade around 4.28%, steady for now after a four-day straight rally higher.
US Dollar Index Technical Analysis: Big break starts to take shape
The US Dollar Index (DXY) is not really moving or responding to the surprise headline and communication from the China and US administrations on trade talks set to start on Saturday. Markets probably quickly read through the headlines and behind the news that these talks are instead to be seen as two desperate parties joining each other to see how to ease the impacts on the economy. This also shows how the US economic performance is probably starting to struggle because it lacks China’s supplies, which might filter through in another leg lower in the DXY once US economic data confirms it.
On the upside, the DXY’s first resistance comes in at 100.22, which supported the Index back in September 2024, with a break back above the 100.00 round level as a bullish signal. A firm recovery would be a return to 101.90, which acted as a pivotal level throughout December 2023 and again as a base for the inverted head-and-shoulders (H&S) formation during the summer of 2024.
On the other hand, the 97.73 support could quickly be tested on any substantial bearish headline. Further below, a relatively thin technical support comes in at 96.94 before looking at the lower levels of this new price range. These would be at 95.25 and 94.56, meaning fresh lows not seen since 2022.
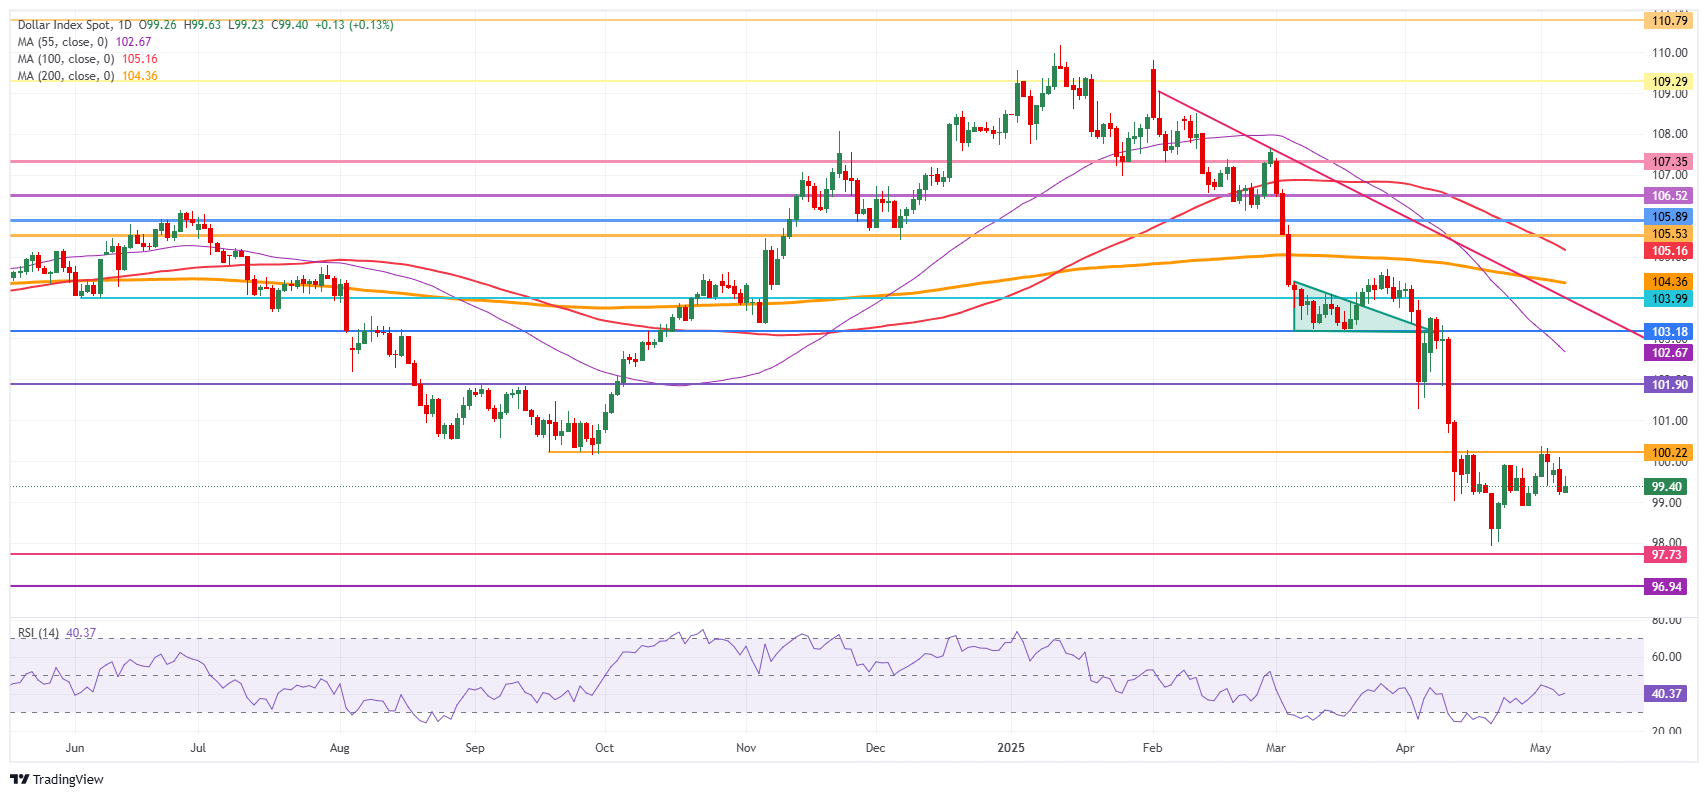
US Dollar Index: Daily Chart
Central banks FAQs
Central Banks have a key mandate which is making sure that there is price stability in a country or region. Economies are constantly facing inflation or deflation when prices for certain goods and services are fluctuating. Constant rising prices for the same goods means inflation, constant lowered prices for the same goods means deflation. It is the task of the central bank to keep the demand in line by tweaking its policy rate. For the biggest central banks like the US Federal Reserve (Fed), the European Central Bank (ECB) or the Bank of England (BoE), the mandate is to keep inflation close to 2%.
A central bank has one important tool at its disposal to get inflation higher or lower, and that is by tweaking its benchmark policy rate, commonly known as interest rate. On pre-communicated moments, the central bank will issue a statement with its policy rate and provide additional reasoning on why it is either remaining or changing (cutting or hiking) it. Local banks will adjust their savings and lending rates accordingly, which in turn will make it either harder or easier for people to earn on their savings or for companies to take out loans and make investments in their businesses. When the central bank hikes interest rates substantially, this is called monetary tightening. When it is cutting its benchmark rate, it is called monetary easing.
A central bank is often politically independent. Members of the central bank policy board are passing through a series of panels and hearings before being appointed to a policy board seat. Each member in that board often has a certain conviction on how the central bank should control inflation and the subsequent monetary policy. Members that want a very loose monetary policy, with low rates and cheap lending, to boost the economy substantially while being content to see inflation slightly above 2%, are called ‘doves’. Members that rather want to see higher rates to reward savings and want to keep a lit on inflation at all time are called ‘hawks’ and will not rest until inflation is at or just below 2%.
Normally, there is a chairman or president who leads each meeting, needs to create a consensus between the hawks or doves and has his or her final say when it would come down to a vote split to avoid a 50-50 tie on whether the current policy should be adjusted. The chairman will deliver speeches which often can be followed live, where the current monetary stance and outlook is being communicated. A central bank will try to push forward its monetary policy without triggering violent swings in rates, equities, or its currency. All members of the central bank will channel their stance toward the markets in advance of a policy meeting event. A few days before a policy meeting takes place until the new policy has been communicated, members are forbidden to talk publicly. This is called the blackout period.
BRANDED CONTENT
Choosing a broker that aligns with your trading needs can significantly impact performance. Our list of the best regulated brokers highlights the best options for seamless and cost-effective trading.
Author

Filip Lagaart
FXStreet
Filip Lagaart is a former sales/trader with over 15 years of financial markets expertise under its belt.

















