US Dollar flattens after soft CPI does not change intraday's narrative
- The US Dollar flat as dust settles over US CPI release on Wednesday.
- Traders saw inflation roll off quicker than expected in February.
- The US Dollar Index holds in the mid-103.00 area with markets digesting the recent inflation reading.
The US Dollar Index (DXY), which tracks the performance of the US Dollar (USD) against six major currencies, is little changed on the day after the United States (US) Consumer Price Index (CPI) release for February. Both yearly and montly numbers for the core and headline inflation came in below expectations, which means that inflation was still slowing in February ahead of the tariffs US President Donald Trump imposed at the start of March.
On the geopolitical front, China again vowed to retaliate on US tariffs. Meanwhile, Europe is set to issue countermeasures on April 13, European Union (EU) leader Ursula Von Der Leyen said this Wednesday. Overnight headlines emerged on the Ukraine-Russia war, where a ceasefire truce is on the table after Ukraine agreed to a brokered deal by the US. The ball is now in the court of Russia to support or refuse it.
Daily digest market movers: Very little reaction
- The US Consumer Price Index (CPI) report for February has been released:
- The monthly headline inflation came in at 0.2%, below the 0.3% consensus and further down from 0.5% in January. Core inflation eased to 0.2%, a touch softer than the expected 0.3% and from 0.4% previously.
- The yearly headline reading came in at 2.8%, just below the 2.9% consensus and down from 3.0% in January. The core gauge softens to 3.1%, below the 3.2% estimate and down from 3.3% in the previous month.
- A much softer reading in inflation data should boost rate-cut bets for the Federal Reserve (Fed) and result in another drop in the US Dollar.
- Around 17:00 GMT, the US Treasury will auction a 10-year Note.
- At 17:35 GMT, St. Louis Fed President Alberto Musalem will speak at the NABE Economic Policy Conference in Washington, D.C.
- Equities are seeing overall more than 1% gains with European and US equity indices rallying higher after the US CPI release.
- The CME Fedwatch Tool projects a 97.0% chance for no interest rate changes in the upcoming Fed meeting on March 19. The chances of a rate cut at the May 7 meeting stand at 37.6% and 81.7% at June’s meeting.
- The US 10-year yield trades around 4.31%, off its near five-month low of 4.10% printed on March 4.
US Dollar Index Technical Analysis: A storm in a glass of water
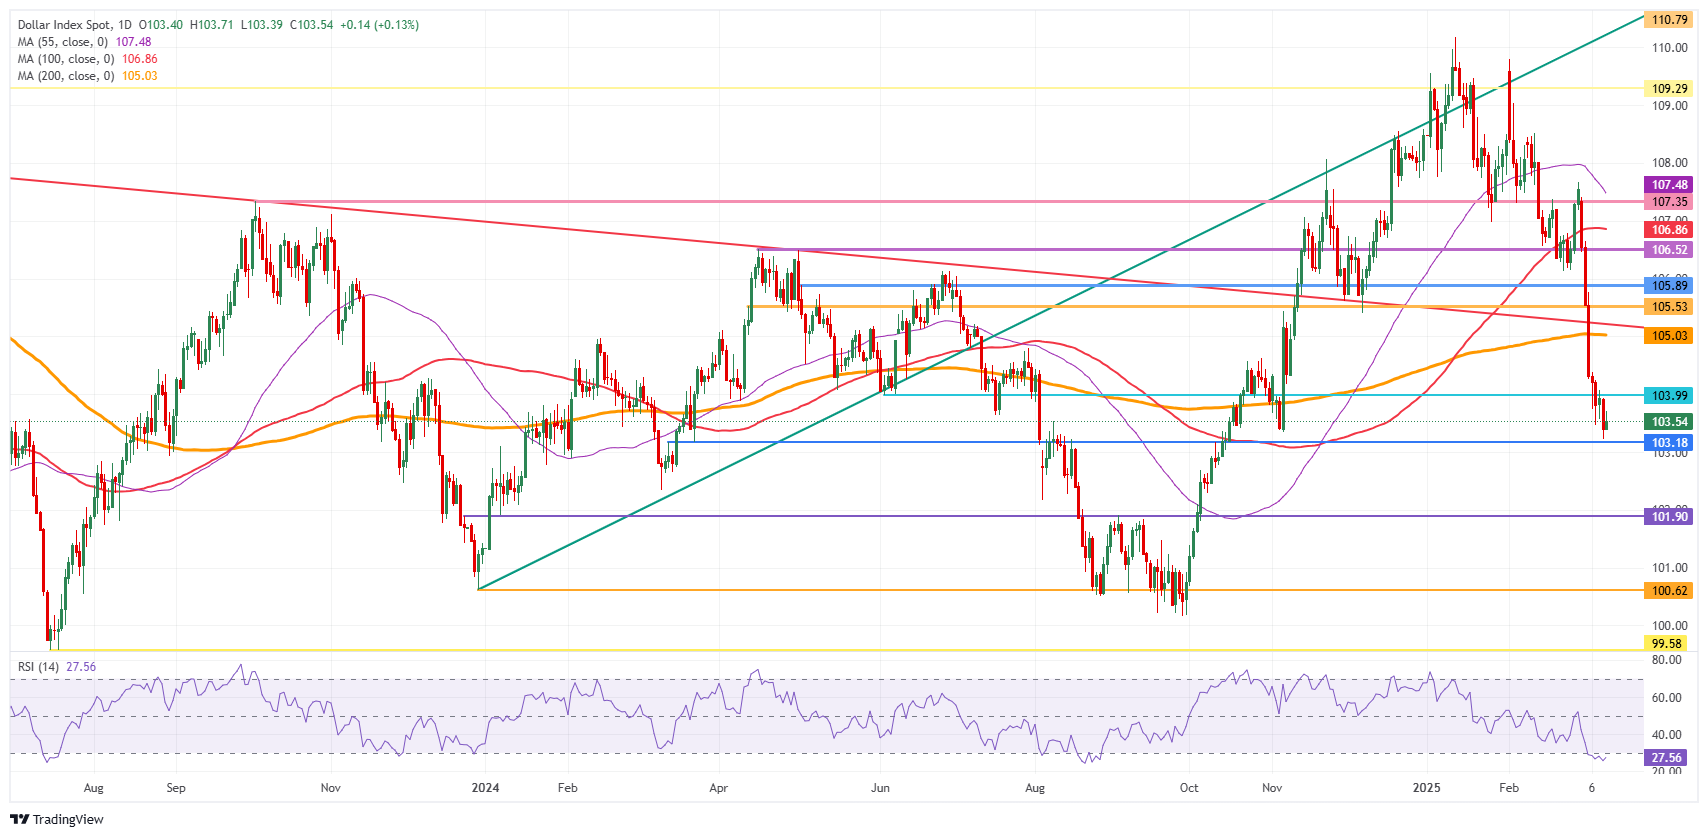
The US Dollar Index (DXY) still faces potential selling pressure as recession fears remain. Traders are concerned about tariffs’ impact and uncertainty on the US economy. A softer inflation reading could help take away the recession fear, though it would still result in a weaker US Dollar with an increasing Federal Reserve’s rate cut bets and a declining rate differential with other countries as main drivers.
Upside risk is the fear of a rejection at 104.00 that could result in more downturn. If bulls can avoid that, look for a large sprint higher towards the 105.00 round level, with the 200-day Simple Moving Average (SMA) at 105.03. Once broken through that zone, a string of pivotal levels, such as 105.53 and 105.89, will present as caps.
On the downside, the 103.00 round level could be considered a bearish target in case US yields roll off again, with even 101.90 not unthinkable if markets further capitulate on their long-term US Dollar holdings.
US Dollar Index: Daily Chart
Fed FAQs
Monetary policy in the US is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability and foster full employment. Its primary tool to achieve these goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, it raises interest rates, increasing borrowing costs throughout the economy. This results in a stronger US Dollar (USD) as it makes the US a more attractive place for international investors to park their money. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates to encourage borrowing, which weighs on the Greenback.
The Federal Reserve (Fed) holds eight policy meetings a year, where the Federal Open Market Committee (FOMC) assesses economic conditions and makes monetary policy decisions. The FOMC is attended by twelve Fed officials – the seven members of the Board of Governors, the president of the Federal Reserve Bank of New York, and four of the remaining eleven regional Reserve Bank presidents, who serve one-year terms on a rotating basis.
In extreme situations, the Federal Reserve may resort to a policy named Quantitative Easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used during crises or when inflation is extremely low. It was the Fed’s weapon of choice during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy high grade bonds from financial institutions. QE usually weakens the US Dollar.
Quantitative tightening (QT) is the reverse process of QE, whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing, to purchase new bonds. It is usually positive for the value of the US Dollar.
Author

Filip Lagaart
FXStreet
Filip Lagaart is a former sales/trader with over 15 years of financial markets expertise under its belt.

















