S&P 500 Forecast: With Credit Suisse buyout behind it, market focuses on Wednesday FOMC
- S&P 500 gained 2.2% last week despite banking weakness.
- Swiss government organized UBS takeover of Credit Suisse over the weekend.
- FOMC meeting on Wednesday has folks expecting 25 basis points.
The S&P 500 on Monday seems a little more optimistic after last week's travails. The S&P 500 opened up 0.4% before the open, while the Dow advanced 1% and the NASDAQ lost 0.4%. This demonstrates the market's interest in value stocks ahead of growth after last week saw a major sell-off in banking stocks. On Sunday the Swiss government and central bank organized a buyout of Credit Suisse by UBS. The combination creates a financial behemoth with about $5 trillion in assets worldwide and $1.5 trillion in Europe alone.
The NASDAQ 100 is down by half a percentage point in early trading as the market exits riskier stocks ahead of Wednesday's interest rate announcement by the Federal Reserve with consensus still at 25 basis points.
S&P 500 news: Powell expected to still raise rates by 25 basis points
Depsite quite a few commentators making the rounds last week with their view of a Fed halt to interest rate hikes, the odds still favor a 25-basis-point hike on Wednesday at the Federal Open Market Committee meeting. Two weeks ago, before Silicon Valley Bank failed, Powell's aggressive comments in front of Congress drew expectations of a 50-basis-point hike. Now that the banking industry is viewed as unstable, there is a much better chance that Powell takes a more dovish tone in his Wednesday press conference.
This is where some of the optimism regarding the S&P 500 index is coming from. Traders are selling out of riskier growth stocks and doubling down on more blue chips, guessing that the interest rate announcement may provoke a bounce mid-week. The US Dollar has been gaining for much of Monday morning, which is also aiding the equity market. Besides the FOMC meeting, traders will watch for existing home sales data on Tuesday, which is expected to reveal 4.2 million sales in the US during February.
Other than that, Tuesday's 20-year US Treasury auction will give the market more insight into the banking sector. The last auction came in just below a 4% yield. If Tuesday's auction sees the 20-years sell for more than 4%, it probably tells us that the worst is over for banks. A yield below 3.977% will tell us that the flight to safety is still underway.
UBS takes over Credit Suisse for $3.25 billion
The Swiss government is a major part of the hopeful feeling on Monday after pulling out all the stops to get UBS to take over the embattled lender Credit Suisse. The latter had been reeling for a long time, delivering losses of $1.65 billion and $7.3 billion in 2020 and 2021, respectively. The bank also lost out in a major way almost exactly two years ago when Bill Hwang's Archegos Capital left it holding the bag when the hedge fund collapsed and could not repay its derivative contracts. UBS stock is up more than 4% on Monday, so it seems the market has generally accepted the deal. The deal is quite generous to UBS, since the Swiss central bank will bear as much as 50% of the downside risk and has wiped out more than $17 billion worth of Credit Suisse bonds.
In the US, however, First Republic Bank (FRC) has sold off 13.4% on Monday after its announcement on Friday that it would be suspending its dividend hurt sentiment. Additionally, Moody's downgraded the bank once again, saying that last week's vote of confidence by the largest US banks to deposit $30 billion in cash has not stemmed the tide of deposit losses.
"The deterioration in the bank's financial profile and the significant challenges First Republic faces over the medium term in light of its increased reliance on short-term and higher cost wholesale funding due to deposit outflows," Moody's wrote.
Earnings of the week
Monday, March 20 - Foot Locker (FL)
Tuesday, March 21 - Tencent Music (TME), Nike (NKE), GameStop (GME)
Wednesday, March 22 - EVgo (EVGO), Cassava Sciences (SAVA), KB Home (KBH), Chewy (CHWY)
Thursday, March 23 - Accenture (ACN), Darden Restaurants (DRI), General Mills (GIS)
S&P 500 quote
Mohamed El-Erian, former CEO of PIMCO, spoke on Bloomberg's Surveillance podcast about the UBS government-back buyout of Credit Suisse on Sunday:
“Look, this was not the best solution, but it dominated the other two – which were nationalization or trying to wind down the bank."
S&P 500 technical analysis
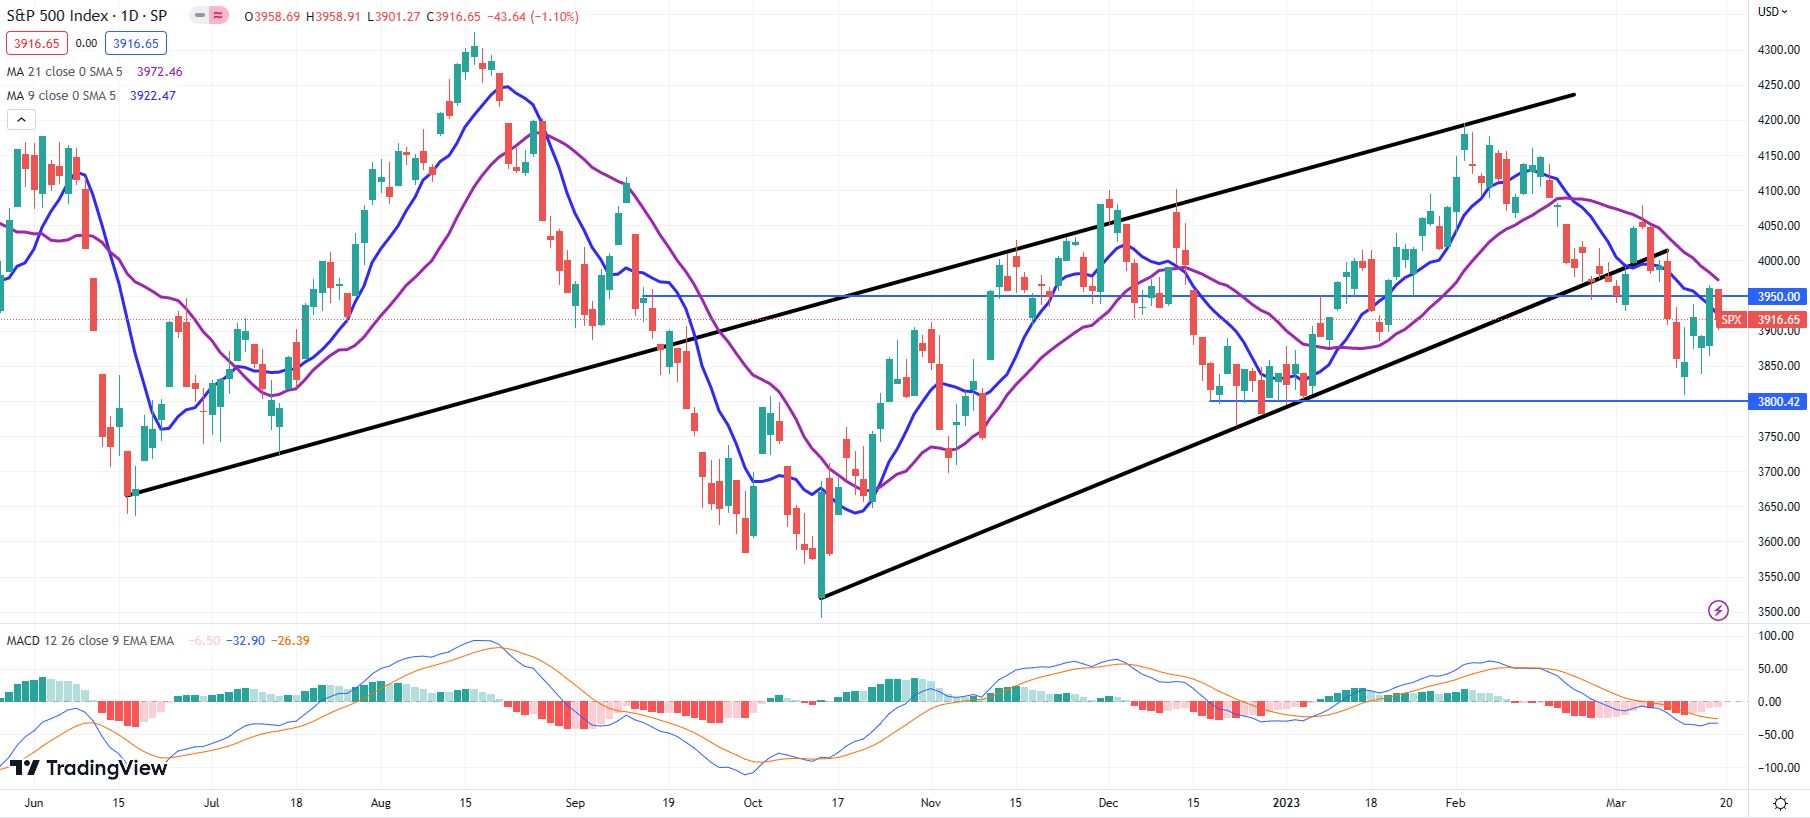
The S&P 500 is back just under the 3,950 level of resistance that we pinpointed last week. A close above here may not be decisive however. That already happened last Thursday, and the index still pulled back on Friday. This time it is best to watch the 21-day moving average, which is currently at 3,965. A close above there on the daily chart will likely lead bulls to make a run at 4,000. This latter price level is the real prize that everyone is watching. Still there will be much less movement before Wednesday's interest rate announcement.
Overall, the S&P 500 remains in a downtrend since breaking the lower ascending trendline in early March. However, the Moving Average Convergence Divergence (MACD) sure looks like a bullish crossover is imminent. The safer move is just to wait on the Fed however!
S&P 500 daily chart
Author

Clay Webster
FXStreet
Clay Webster grew up in the US outside Buffalo, New York and Lancaster, Pennsylvania. He began investing after college following the 2008 financial crisis.