|

Sellers returning fast
NFPs weren‘t weak at first glance, but the buying squeeze anticipated, was really short-lived, and shifting rate cut odds influenced. In spite of Waller opening the 50bp Sep cut possibility, the real odds didn‘t go up and remained at 30% only, and that‘s after Williams quite confirming 25bp cut. This comes after the (in my view clear) policy mistake in Jul of not cutting, and then we had the early Aug Monday with Siegel calling for 75bp emergency cut and then 75bp more in Sep.

While disinflation lasts and the Jackson Hole inflation victory lap is over, the job market is quite steadily deteriorating, and for all the orderly assurances would require energetic Fed action even if it doesn‘t come in my view in Sep (yeah, only 25bp), but only later (the bigger cut).

It wasn‘t the job market data that brought the stock market down after the swing higher, it was about acceleration of selling into (receding bout of) strength following the 50bp cut statement by Waller before EST lunch time. Remember my extensive analysis a week ago where I discussed hard landing as an underappreciated risk to stock market upswing – the data this week weren‘t stellar.

And that implies certain confusion about how the upcoming cut (25bp or 50bp) will be perceived by the market – reassuring and calming, or rushed and belated.
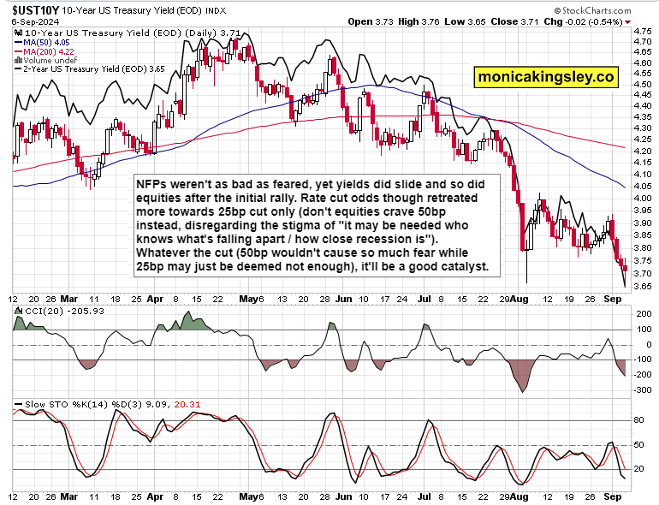
Market rates are reflecting the deteriorating but not yet recessionary (not declared as such) data, and 25bp cut isn‘t in sync, meaning the necessity to cut more, is underappreciated in the now even if 125bp cut till Dec is the mainstream expectation. Sep 25bp just doesn‘t go far enough given the job market challenges, that‘s what the market rates are saying.

We have continued Nasdaq underperformance lasting weeks, with S&P 500 being propped up by financials, defensives and generally income and interest rate sensitive plays. Smallcaps and equal weighted S&P 500 are doing a bit better, and next week we have to pay close attention to how banks big and small are doing – together with AAPL reaction inspiring a tech reprieve or not.

Inverted head and shoulders in the making in S&P 500? Well, that would be a premature call, now at the right head top, wouldn‘t it. The right shoulder wouldn‘t be carved out of nowhere, and Wednesday‘s CPI is still far away – but way more details are discussed below for clients, looking at VIX and upcoming data.

Author

Monica Kingsley

Monica Kingsley

Monicakingsley

Monica Kingsley is a trader and financial analyst serving countless investors and traders since Feb 2020.


More from Monica Kingsley
Share:

Editor's Picks

AUD/USD drops to two-week low, further below 0.7000 after RBA's less hawkish rate hike

AUD/USD drifts lower for the second straight day on Tuesday, hitting a fresh two-week low during the Asian session after the Reserve Bank of Australia's (RBA) widely expected 25 bps rate hike. The decision was far from unanimous, with three members preferring to hold rates at 4.60%. This tempers expectations of further tightening, which, along with modest US Dollar strength, weighs on the currency pair.


USD/JPY fails near 159.00 amid weak USD, intervention risks

USD/JPY edges lower during Tuesday’s Asian session, reversing part of the previous day's gains to 158.00 as the US Dollar remains depressed amid hopes for Iran diplomacy and ahead of US midterm elections. Meanwhile, intervention risks support the Japanese Yen, though the uncertainty over the timing of the next BoJ rate hike caps gains. This keeps the pair confined within a familiar range and warrants caution before placing directional bets.


Gold struggles below $3,950 amid Fed hike bets, ahead of US midterm elections

Gold weakens further below $3,950 during the Asian session, reversing part of the previous day's recovery from a one-year low set last week. Data released on Monday showed that US manufacturing sector business activity expanded for the 10th straight month in October. The Institute for Supply Management's Manufacturing PMI came in higher than consensus estimates and rose to 55.5 in October from 54.5 in the previous month. This reaffirms hawkish US Federal Reserve expectations, which along with rebounding US bond yields, prompt fresh selling around the non-yielding yellow metal.

Cardano extends losses as sellers stay in control

Cardano (ADA) extends correction, trading below $0.189 on Tuesday after losing key support zone the previous day. Mixed derivatives data and cautious on-chain metrics continue to weigh on bullish sentiment, while weakening technical indicators suggest further downside risks for ADA.

What a split Congress means for the US Dollar

The United States is going to the polls on Tuesday, and much is at stake. The mid-term elections mean the renovation of roughly one-third of the Senate and all 435 of the House seats. Additionally, special elections in Florida and Ohio will be held to fill the seats vacated by US Secretary of State Marco Rubio and Vice President JD Vance.

The 2% inflation target came from a throwaway remark. It now moves trillions
The Federal Reserve's 2% inflation goal grew out of an off-the-cuff remark by a New Zealand politician in 1988. Bond investors still price long-term US debt as if 2% holds, so a change in how the Fed measures inflation would move markets.















