|

GBP/USD rallies on soft US Dollar, eyes on 1.2500

  • GBP/USD pops higher as the US Dollar comes under pressure. 
  • US debt ceiling risks and Treasury yields falling are weighing on the greenback. 

GBP/USD is 0.29% higher on the day after rallying from a low of 1.2410 and reaching a high of 1.2478. The US Dollar has been sold off as US yields sink at the start of the week. 

The US Dollar, as measured by the DXY index, has fallen from a high of 101.909 and has reached a low of 101.369 in recent trade. US Treasury yields are down, with the 2-year losing 1.12% and the 10-year down 1.7%. Further in, the yield of the 1-month Treasury, which started the month near 4.7%, fell to 3.30% as investors appeared to grow increasingly concerned about a potential standoff over the US debt ceiling. 

The House of Representatives is expected to vote on a Republican-led debt and spending bill this week. Additionally, until rate cuts this year are finally priced out, the US Dollar is likely to remain vulnerable.  Also, a closely watched part of the US Treasury yield curve measuring the gap between yields on two- and 10-year Treasury notes, seen as an indicator of economic expectations, was at -62.9 basis points.

All eyes on the US data ahead of the FOMC

Meanwhile, we have entered the quiet period for the Fed ahead of the May 2-3 Federal Open Market Commmittee meeting and all eyes are on the data between now and then. ´´Recent resilience in the US economy helped push US Treasury yields higher and we look for that process to continue,´´ analysts at Brown Brothers Harriman explained. ´´If so, the dollar should continue to gain as well,´´ they said.

In the data at the start of the week, the Chicago Fed National Activity Index fell 0.19 in March, beating market expectations for a 0.20 decline. The April reading of the Dallas Fed Manufacturing Index, however, was -23.4, way worse than the -12.0 economists were predicting, down from -15.7 in March. 

´´The continued resilience in the economy is noteworthy and suggests the Fed still has a lot more work to do in getting to the desired sub-trend growth,´´ analysts at Brown Brothers Harriman said.

Between now and next Wednesday’s Fed decision, we will have the first quarter Gross Domestic Product this week and then Personal Consumption Expenditure. The following week, ISM manufacturing PMI, then next Tuesday brings JOLTS data and next Wednesday brings ADP private sector jobs. The Nonfarm Payrolls will come after the Fed. 

´´ To us, a hike next week is a done deal,´´ the analysts at BBH said.  ´´There are about 15% odds of another 25 bp hike in June. At this point, a pause in June might just be the most likely outcome but it really will depend on how all that data come in.  After all that, one cut is still priced in by year-end vs. two at the start of last week.  In that regard, Powell has said that Fed officials “just don’t see” any rate cuts this year.  We concur.´´

GBP/SD technical analysis
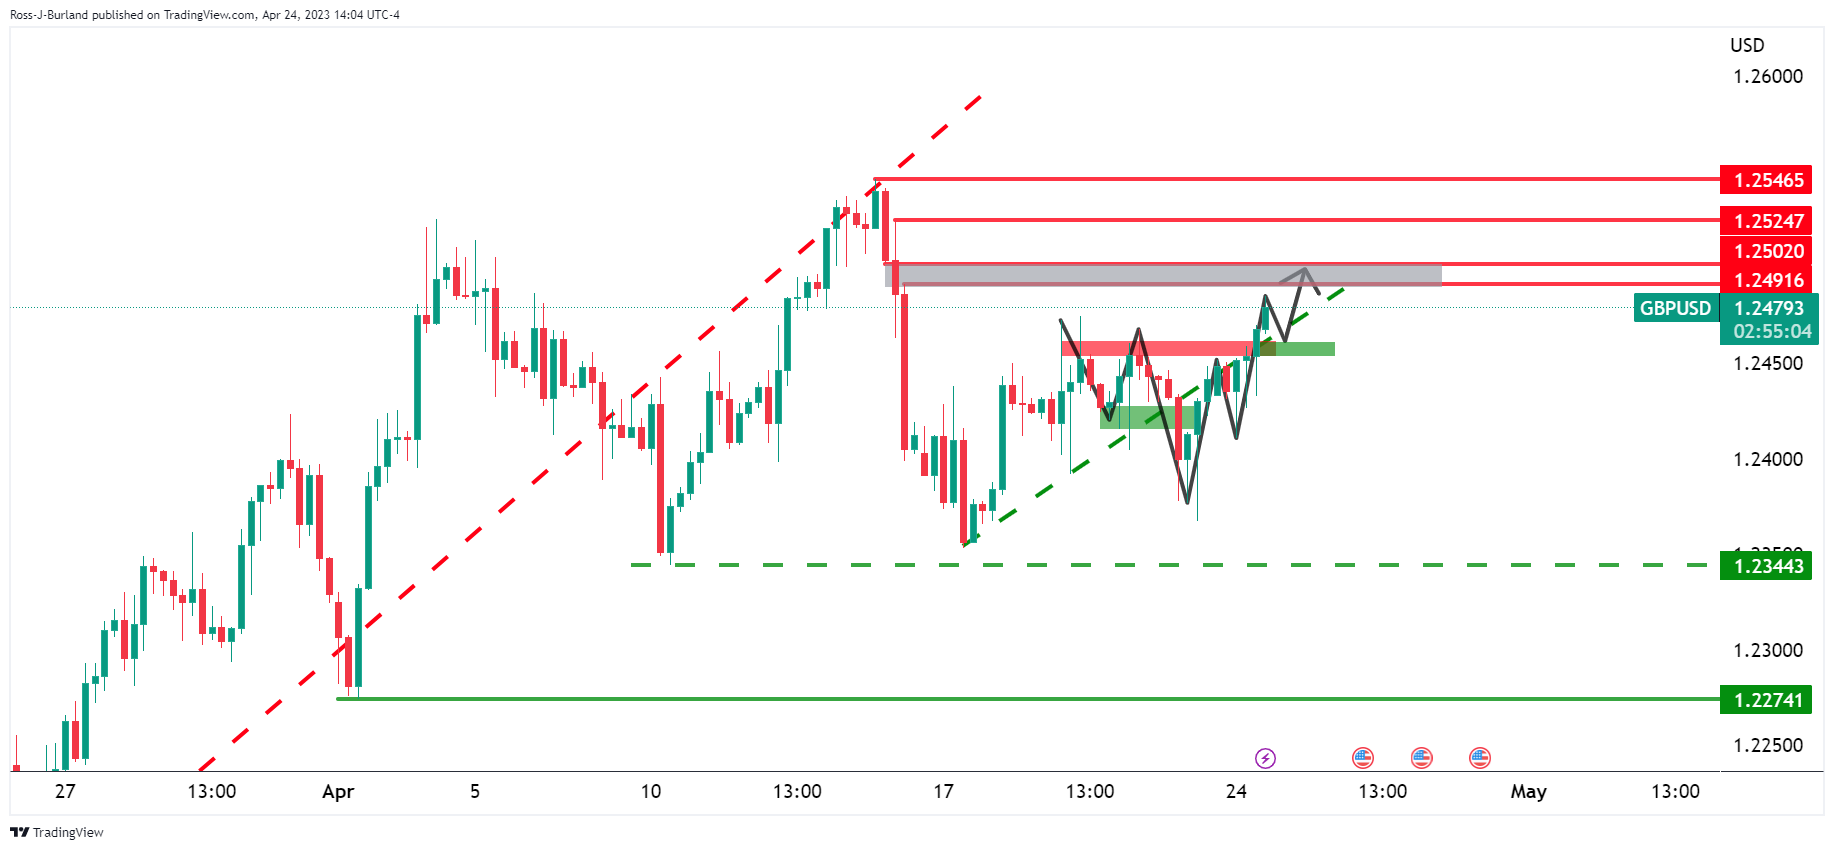
GBP/USD bulls are in the market, eyeing a run to test 1.2500 within the breakout of the inverse head and shoulders pattern on the 4-hour chart. 


Overview
Today last price1.248
Today Daily Change0.0039
Today Daily Change %0.31
Today daily open1.2441
 
Trends
Daily SMA201.2413
Daily SMA501.221
Daily SMA1001.2198
Daily SMA2001.1927
 
Levels
Previous Daily High1.2448
Previous Daily Low1.2367
Previous Weekly High1.2474
Previous Weekly Low1.2354
Previous Monthly High1.2424
Previous Monthly Low1.1803
Daily Fibonacci 38.2%1.2398
Daily Fibonacci 61.8%1.2417
Daily Pivot Point S11.239
Daily Pivot Point S21.2338
Daily Pivot Point S31.2308
Daily Pivot Point R11.2471
Daily Pivot Point R21.25
Daily Pivot Point R31.2552

Author

Ross J Burland

Ross J Burland, born in England, UK, is a sportsman at heart. He played Rugby and Judo for his county, Kent and the South East of England Rugby team.


More from Ross J Burland
Share:

Editor's Picks

AUD/USD consolidates above 0.7000; remains close to monthly top

AUD/USD holds steady above 0.7000 during the Asian session on Friday, trading just below the previous day's monthly low amid diverging forces. A hawkish RBA continues to support the Aussie, while the recent decline in US bond yields keeps the US Dollar depressed near a three-week low. However, oil-driven inflation fears reinforce Fed hike bets, which, along with geopolitical risks, could benefit the safe-haven buck and cap the currency pair.

USD/JPY drops to an over one-month low, around 156.00 after Japan's CPI report

USD/JPY attracts heavy follow-through selling on Friday, dropping to the 156.00 neighborhood, a one-month low, as Japan's National CPI report reaffirms bets for an imminent BoJ rate hike and boosts the Japanese Yen. Moreover, the recent steep fall in US bond yields counters hawkish Fed expectations and geopolitical risks, undermining the US Dollar and exerting additional pressure on the currency pair.

Gold seems vulnerable near August lows; eyes $4,000 break amid Fed hike bets

Gold touches a fresh low since early August during the Asian session on Friday, eyeing the key $4,000 psychological mark. Oil-driven inflation fears reinforce December Fed hike bets and continue to undermine the non-yielding bullion, which fails to benefit from the recent steep fall in US bond yields and the prevailing US Dollar selling bias. Moreover, the overnight breakdown below a trading-range support backs the case for further depreciation.


Bitcoin falls 4% as chip stocks plunge 6.7% and oil surges
Bitcoin (BTC) fell below $82,000 on Thursday as the crypto market joined a broader market sell-off driven by concerns over artificial intelligence (AI) spending, rising oil prices and escalating geopolitical tensions involving the US and Iran. The top crypto fell 4% to $81,130 as macro fears weighed on prices across the digital asset market.
The Bank of England just got its clearest reason to hike. Here's what it's really watching

UK inflation as measured by the CPI accelerated to 3.5% YoY in September, up from 3.1% in August, according to the Office for National Statistics. This is the highest level since October 2025, exceeding economists' expectations of 3.4% and pushing inflation further from the BoE's 2% target.

What November 3 means for the Fed's rate path and the US Dollar

The USD faces a decisive period ahead of the November 3 midterm elections. While markets anticipate another interest rate increase from the Fed in December, the battle for control of Congress could reshape fiscal policy expectations and, indirectly, the path of US monetary policy in 2027.















